
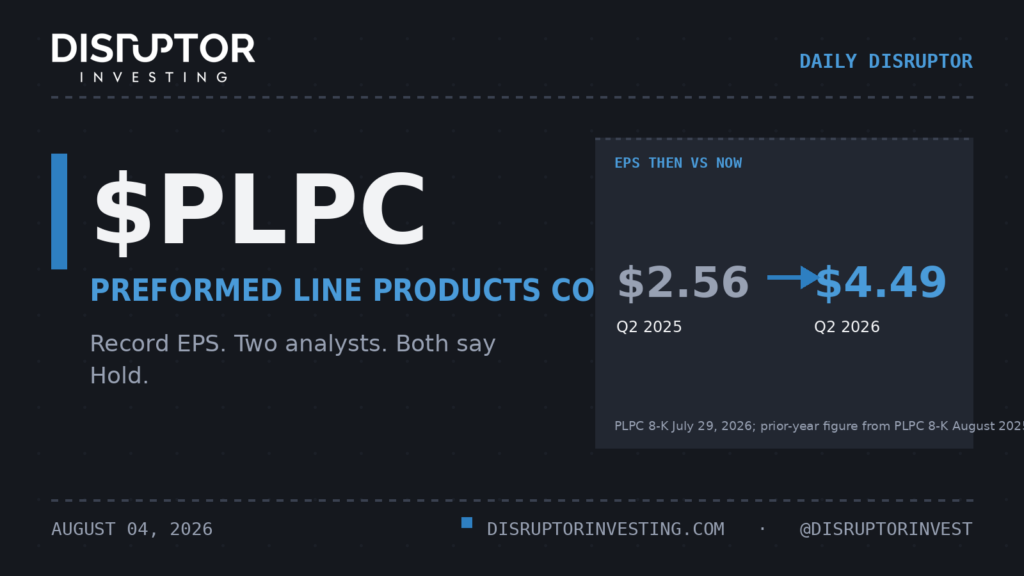
The highest quarterly earnings per share in a 79-year history landed six days ago. The stock barely moved. That is the setup this morning.
Preformed Line Products Company (NASDAQ: PLPC) reported Q2 2026 diluted EPS of $4.49, a 75% jump from $2.56 a year earlier and the best single quarter in the company’s existence. Revenue came in at $212.7 million, up 25% year over year and 21% sequentially from Q1. The consensus estimate for EPS was $2.41. The company beat it by $2.08, an 86% surprise. Two analysts cover PLPC. Both still rate it Hold. Their combined price target is $275. The stock closed near $356.
The 30 second version
- PLPC makes the connectors, string hardware, and substation fittings that hold transmission lines together, in 20 countries
- Q2 2026 EPS was $4.49, up 75% year over year, beating the only two analyst estimates by 86% on July 29, 2026
- Catalyst: analyst revision cycle begins now; Q3 results due November 4, 2026
- Main risk: thin float of roughly 4.88 million shares; tariffs on steel and aluminum squeeze margins
- Market cap approximately $1.75 billion; shares repurchased, not diluted
What just happened
The Q2 print landed July 29. USA sales grew 32% year over year, driven almost entirely by energy market demand, and every international segment posted year on year growth. Gross margin reached 34.3%, up 300 basis points from Q1 and 160 basis points from a year earlier. The company is generating operating leverage: fixed costs are spread across a larger base, pricing from 2025 is flowing through, and the tariff headwinds that plagued the prior two quarters are now partially offset by those same price increases. Net income for the first half of 2026 was $32 million, or $6.62 per diluted share, compared with $4.89 for the same period in 2025.
One day after reporting, on July 28, PLPC acquired a Canadian facility and partly financed it with a new term loan of approximately $9.7 million. That purchase is not yet in the numbers. The company also bought Delta Star Conetores Eletricos, a Brazilian substation connector maker, in May for roughly $11.1 million net. Together, these moves extend PLPC’s reach into high voltage and extra high voltage substation work, the fastest growing slice of grid spending.
The business
Preformed Line Products was founded in 1947 and makes the hardware that nobody thinks about until the grid goes down. The products include helical armor rods, splice closures, substation connectors, spacer dampers, and Optical Ground Wire, which does double duty as a lightning shield and a fiber optic cable. Utilities buy these products because they are mission critical and because switching costs after a line crew has been trained on one system are prohibitive. That stickiness is why the energy division has held margins above 30% for most of the past three years, even as commodities and tariffs pushed costs up.
The detail most filings readers will notice: PLPC does not break out backlog quarterly, but at December 31, 2025, the order book stood at $232.8 million, a 22% increase from the prior year. Given Q2 energy demand was described by the chairman as exceptional, there is no public signal that bookings have slowed. The company is also building a new manufacturing facility in Poland, expanding in Spain, and now adding Canadian capacity, all commitments that only make sense if order flow remains strong.
The numbers
Revenue in the first half of 2026 was $389 million, up 22% from $318.1 million in the same period of 2025. Full year 2025 revenue was $669.3 million, growing 13% from 2024. The acceleration from 13% annual growth to 22% in a half year is the inflection. Gross margin is expanding: 34.3% in Q2 2026, versus 31.3% in Q1 and 32.7% in Q2 2025. The balance sheet is clean. At June 30, PLPC held $76.2 million in cash, total debt of $42.8 million, and only $6.7 million drawn on a $60 million credit facility. Shares outstanding fell slightly from 4.91 million at year end 2025 to 4.88 million at June 30, 2026, as buybacks modestly offset new grants.
Two analysts cover this stock. The consensus revenue estimate for Q3 2026 is $205 million and consensus EPS is $2.84. Given that Q2 just came in at $212.7 million and $4.49, those numbers are stale before the ink is dry. Management does not issue formal numerical guidance. The next formal earnings event is November 4, 2026. The revision cycle between now and then is where the asymmetry sits.
Why the market has not caught up
PLPC has roughly 4.88 million shares outstanding and 41% institutional ownership. Dimensional Fund Advisors filed a 4.5% passive stake in July. Wasatch Advisors added 264,478 shares in Q2 2026, a 234% increase in their position. Smart money is accumulating quietly. The analyst community has not followed. Two researchers cover the stock, both at Hold, with a combined price target of $275. The stock is at $356. That is not a slight mismatch, it is a structural gap born from neglect: small float, no quarterly guidance, an Ohio manufacturer that makes products most fund managers have never heard of.
The filing that explains the gap better than anything else is the Q1 2026 10-Q, which notes that PLP USA alone generated more energy product revenue in Q1 than the whole Americas segment did a year earlier. That kind of internal reshuffling is invisible to someone reading a headline. It takes reading the segment disclosures to see that PLPC’s core business has repriced itself against a backdrop of sustained grid spending. At six times trailing twelve month earnings, the stock is not expensive relative to what it is producing.
What breaks it
The float is the first problem. With fewer than 5 million total shares outstanding, a large institutional move in either direction can gap the stock significantly. Thin volume days are common. Anyone sizing into this needs to account for that. The second problem is tariffs: Section 232 steel and aluminum duties are a persistent headwind, and if they escalate materially or if PLPC cannot pass through future cost increases the way it did in 2025, margin expansion stalls. The company is also carrying the early stage integration costs of two acquisitions, Delta Star and the Canadian facility, both of which were closed in 2026 and whose full contribution is unknown. And the Q3 estimate revision cycle requires at least one analyst to publish a new model, which in a two analyst world is not guaranteed to happen quickly.
What we are watching
- Analyst estimate revisions: any upgrade or price target increase before September 2026 would force institutional attention onto a very thin float
- Q3 2026 earnings, November 4, 2026: the quarter that either confirms the H1 acceleration or reveals whether Q2 was a peak
- Backlog disclosure: PLPC does not report backlog quarterly, but any investor presentation or conference appearance between now and November could reveal the order book trajectory
Not financial advice.
The setup
Pilgrim Power and Light sits at $356.98, holding well above its 200 day moving average by 26.3% but essentially flat against its 50 day, just 0.6% below it. That puts it in a muddled near term position: the longer trend is clearly up, but the shorter trend has stalled. At 80% of its 52 week range and 13.1% off the high, the stock has pulled back from its peak without giving up much of the base. The six month return of 42.3% means a lot of the move is already in the price, and the one month return of negative 3.2% confirms the recent softness. Volume is running only marginally above normal at 1.07 times the 50 day average, so there is no clear surge of buying pressure to point to. The three month relative strength against the market is a modest positive at 3.3 points, meaning the stock has not been dramatically outperforming, but it has not been losing ground to the broader market either.
The historical base rate on this ticker, drawn from 185 prior days when PLPC sat in a comparable technical position, showed a median one month move of positive 6.8% and a median quarterly move of 24.0%. The stock was higher a month later 71% of the time and a quarter later 77% of the time, though quarterly outcomes ranged from negative 26.6% to positive 76.0%. That spread is wide enough to matter. The sample covers 185 days on one ticker, which gives it more weight than a handful of observations, but it is still one company, one history, and the range of outcomes shows the distribution is far from tight. Past behavior on this ticker is not a guide to what comes next, and the base rate should inform context, not confidence.
References
- Preformed Line Products Company. Form 8-K, Exhibit 99.1: Record Second Quarter 2026 Financial Results. US Securities and Exchange Commission. Published July 29, 2026. Accessed August 4, 2026. https://www.sec.gov/Archives/edgar/data/0000080035/000008003526000028/plpc-10qxexx991x2026q2.htm
- Preformed Line Products Company. Form 10-Q for the quarterly period ended June 30, 2026. US Securities and Exchange Commission. Published July 29, 2026. Accessed August 4, 2026. https://www.stocktitan.net/sec-filings/PLPC/10-q-preformed-line-products-co-quarterly-earnings-report-d21881753f7e.html
- Preformed Line Products Company. Form 8-K, Exhibit 99.1: Fourth Quarter and Full Year 2025 Financial Results. US Securities and Exchange Commission. Published March 4, 2026. Accessed August 4, 2026. https://www.sec.gov/Archives/edgar/data/80035/000008003526000004/plpc-10qxexx991x2025q4.htm
- Preformed Line Products Company. Form 8-K, Exhibit 99.1: First Quarter 2026 Financial Results. US Securities and Exchange Commission. Published April 29, 2026. Accessed August 4, 2026. https://www.sec.gov/Archives/edgar/data/0000080035/000008003526000015/plpc-10qxexx991x2026q1.htm
- Preformed Line Products Company. Record Second Quarter 2026 Financial Results. PR Newswire. Published July 29, 2026. Accessed August 4, 2026. https://www.prnewswire.com/news-releases/preformed-line-products-announces-record-second-quarter-2026-financial-results-302837970.html
- The Markets Daily. Preformed Line Products (NASDAQ:PLPC) Posts Earnings Results, Beats Estimates By $2.08 EPS. Published July 30, 2026. Accessed August 4, 2026. https://www.themarketsdaily.com/2026/07/30/preformed-line-products-nasdaqplpc-posts-earnings-results-beats-estimates-by-2-08-eps.html
- Dimensional Fund Advisors LP. Schedule 13G/A Amendment No. 9 for Preformed Line Products Company. US Securities and Exchange Commission. Published July 14, 2026. Accessed August 4, 2026. https://www.stocktitan.net/sec-filings/PLPC/schedule-13g-a-preformed-line-products-co-amended-passive-investment–4197ee659542.html
- Quiver Quantitative. Preformed Line Products Posts Record Q2 Sales and $4.49 Diluted EPS. Published July 29, 2026. Accessed August 4, 2026. https://www.quiverquant.com/news/Preformed+Line+Products+Posts+Record+Q2+Sales+and+$4.49+Diluted+EPS
- TradingView. Preformed Line Products Company Next Earnings Date November 4, 2026. Accessed August 4, 2026. https://www.tradingview.com/symbols/NASDAQ-PLPC/