
← All sectors / The AI transformation
087 · Industrial distribution & MRO supply
The parts that keep plants running
Curve position
Binding constraint
Data quality across millions of unstructured part numbers.
Why this sector sits at Orbit
We place industrial distribution and MRO supply at Orbit. Digital ordering and on-site inventory technology are already mainstream. Fastenal's digital share reached 61.4% of sales in Q3 2026, with more than 143,000 vending and bin devices installed. The winners, including Grainger and Fastenal, have long been clear.
Growth has sped up: Grainger's daily organic sales rose 13.7% in Q2 2026, against 4.6% in Q4 2025, and Fastenal's daily sales rose 15.5% in Q3 2026. We don't read that as Flight. Fastenal credits share gains, pricing and broad demand, and Grainger's margin included tariff refunds. That is a business cycle, not a jump in adoption.
We would reconsider only if a new distribution model started taking share at startup speed.
Reviewed on a two month cycle. The position moves only when a dated, verifiable change in the binding constraint justifies it.
Heatmap / How this sector's stocks are moving
| Stock | Price | 1 Day | 1 Week | 1 Month | Year to date |
|---|---|---|---|---|---|
| $GWW | $1,489.39 | +6.54% | +11.09% | +16.76% | +47.60% |
| $FAST | $53.21 | +1.68% | +3.42% | +4.72% | +32.59% |
| $MSM | $116.06 | −3.52% | −5.33% | −10.94% | +38.00% |
| $WCC | $316.72 | −9.92% | −8.78% | −17.54% | +29.46% |
| $DXPE | $158.38 | −11.76% | −5.55% | −17.36% | +44.26% |
| Sector average | −3.40% | −1.03% | −4.87% | +38.38% |
Prices as of November 5, 2026. The sector's move is the equal-weighted average of these listed companies, a market proxy for context, not recommendations. See it on the full heatmap →
Sentiment / The mood in this sector's stocks
Since 2018, Industrial distribution & MRO supply has been in Skepticism and falling 34 separate times. After those, its stocks beat their usual three months 16 times (47%), by a median of −0.6 points.
Confidence: low, a split like this is common by chance, so no edge is called.
Industrial distributors sell the fasteners, bearings, motors, and consumables that keep factories running. It is an unglamorous, fragmented, enormous business, and the distributors sit on demand data spanning thousands of manufacturers.
Historically the model was catalogues, branch inventory, and relationships. Digital ordering arrived slowly, and most transactions still involve a phone call or a counter visit somewhere in the process.
The structural driver is that customers want predictive rather than reactive supply. A plant that knows which bearing will fail next month orders differently than one that discovers it during a breakdown.
The technology layer spans product data normalization across millions of unstructured part numbers, search that understands industrial specifications, vending and inventory management placed at customer sites, predictive replenishment, and marketplace platforms.
Adoption economics work through downtime avoidance and inventory reduction. A plant carrying less safety stock while experiencing fewer stockouts is a direct and measurable win.
The beneficiaries include the large distributors investing in digital capability, product data and taxonomy vendors, inventory management technology firms, and the manufacturers whose products get specified through digital channels.
The value chain runs from manufacturers through distributors to plant maintenance teams. Distributors occupy the demand aggregation point, which is where the useful data sits.
The overlooked layer includes regional distributors consolidating locally, product data management vendors, industrial vending and inventory technology firms, and the software providers serving maintenance departments.
Competitive dynamics favor scale in inventory and density in branch coverage, with consolidation continuing as smaller distributors struggle to fund digital investment.
Risks: industrial production cycles drive volumes directly, manufacturers can sell direct and bypass distributors, price transparency compresses margins, and digital investment is expensive for mid sized players.
What to watch: digital order share at distributors, inventory turns, vending installation counts, and consolidation activity among regional players.
Coverage / Daily Disruptor issues in this sector
October 29, 2026
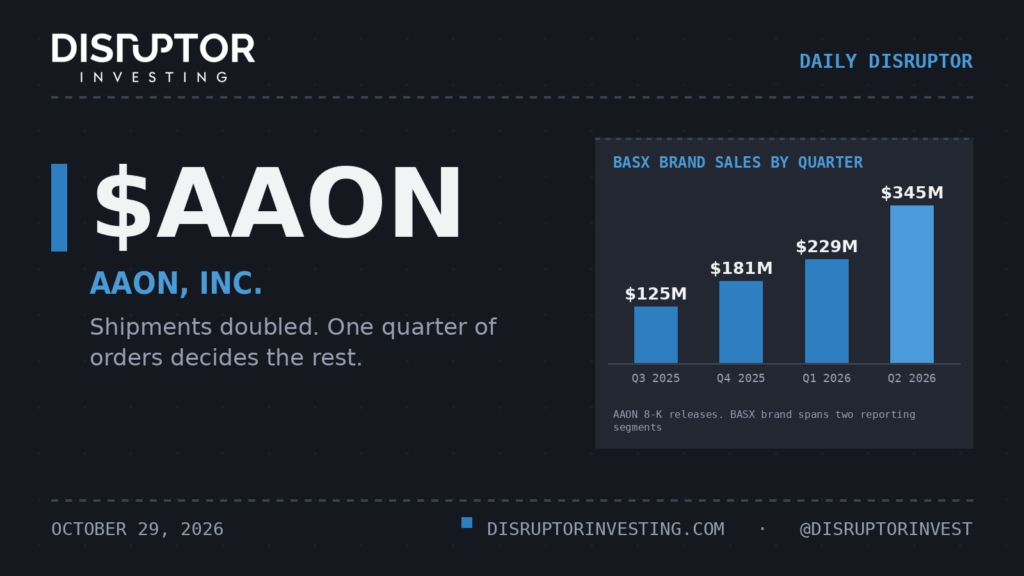
Daily Disruptor: $AAON, the factory caught up, now the orders have to
AAON's BASX data centre cooling business has broken its factory limit, but a thin June order book means November's report is the real test.
Read the issue →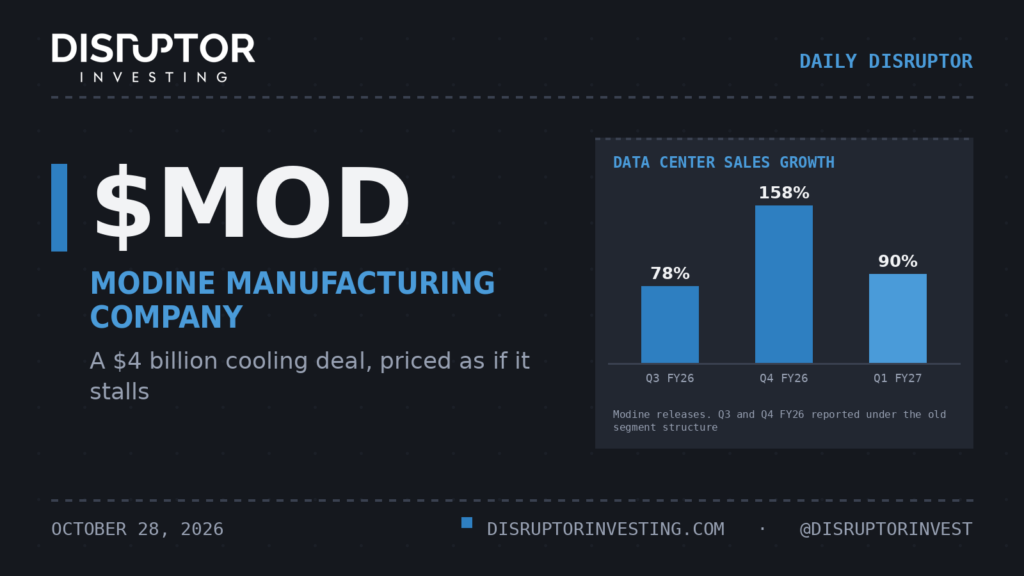
October 28, 2026
Daily Disruptor: $MOD, booked through 2029 and priced for a stall
A customer paid Modine $165 million in cash to reserve more than $4 billion of cooling output for 2027 to 2029, and next Tuesday's results show…
Read the issue →