
← All sectors / The AI transformation
050 · Autonomous laboratories & AI for science
Machines that run the experiment
Curve position
Binding constraint
Instrument integration: most lab equipment was never designed to be driven by software.
Why this sector sits at Launch Pad
Revenue is still dominated by grants and national-lab pilots (PNNL, CMU/Argonne, August 2026), with Automata's $45M Series C (February 2026) representing early commercial deployment—reproducible commercial-scale autonomous lab services do not yet exist at scale.
Reviewed on a two month cycle. The position moves only when a dated, verifiable change in the binding constraint justifies it.
Heatmap / How this sector's stocks are moving
| Stock | Price | 1 Day | 1 Week | 1 Month | Year to date |
|---|---|---|---|---|---|
| $RXRX | $3.88 | +5.43% | −10.80% | −16.20% | −5.13% |
| $SDGR | $28.52 | +4.93% | −7.61% | −1.31% | +59.51% |
| $ABSI | $10.48 | +4.80% | −11.78% | +2.04% | +200.29% |
| $TMO | $706.16 | +1.12% | +0.29% | +7.55% | +21.87% |
| $A | $177.17 | +0.97% | −2.37% | +4.63% | +30.21% |
| Sector average | +3.45% | −6.45% | −0.66% | +61.35% |
Prices as of November 5, 2026. The sector's move is the equal-weighted average of these listed companies, a market proxy for context, not recommendations. See it on the full heatmap →
Sentiment / The mood in this sector's stocks
Since 2018, Autonomous laboratories & AI for science has been in Optimism and rising 28 separate times. After those, its stocks beat their usual three months 14 times (50%), by a median of +0.4 points.
Confidence: low, a split like this is common by chance, so no edge is called.
The bottleneck in materials and chemistry research has always been the speed of physical experiments. Self driving laboratories close the loop: a model proposes a candidate, robotics execute the synthesis and measurement, and the result retrains the model, running continuously without a human at the bench.
Historical context: laboratory automation has existed in pharmaceutical high throughput screening for decades, but it executed fixed protocols rather than deciding what to try next. Adding a model that chooses the next experiment turns automation into discovery.
The structural driver is the sheer size of chemical and materials space. The number of possible compounds vastly exceeds what human led experimentation can explore, so the constraint has always been sampling. Closed loop systems attack exactly that.
The technology layer spans laboratory robotics and liquid handling, analytical instruments with programmatic control, orchestration software that sequences the work, active learning models that select experiments, and the data infrastructure that makes results machine readable.
Adoption economics work first where experiments are cheap, fast, and parallel: formulations: catalysts, battery electrolytes, coatings, and specialty chemicals. Slow or expensive experiments benefit less, because the loop cannot iterate.
The beneficiaries include laboratory automation and robotics suppliers, analytical instrument makers with programmable interfaces, informatics and orchestration software vendors, consumables suppliers whose volumes rise with experiment counts, and the contract research organizations deploying it.
The value chain runs from instruments and robotics through orchestration software to the research organizations using them. Instruments and consumables capture value regardless of which discovery program succeeds.
The overlooked layer includes analytical instrument makers, laboratory consumables suppliers, robotics integrators specializing in lab environments, and the scientific data management vendors making legacy instruments addressable.
Competitive dynamics favor instrument vendors who open their equipment to software control, since closed instruments get designed out of automated workflows. That is quietly reshaping purchasing decisions across research budgets.
Risks: capital intensity is high for the labs themselves, integration with legacy instruments is genuinely difficult, research budgets are cyclical and grant dependent, and the discovery claims in this field frequently outrun the reproducible results.
What to watch: instrument vendors adding programmatic control, consumables volume growth at automation adopters, published closed loop discovery results, and contract research organizations offering autonomous capability.
Coverage / Daily Disruptor issues in this sector
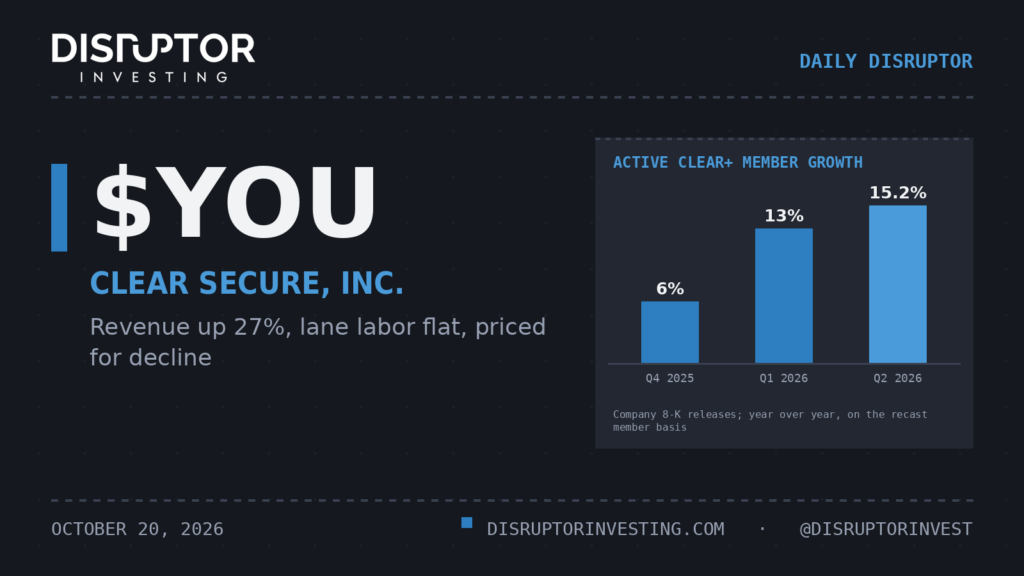
October 20, 2026
Daily Disruptor: $YOU, revenue up 27% while lane labor stayed flat
CLEAR's eGates are letting airport revenue grow on flat staffing costs, and the share price still assumes free cash flow shrinks, two weeks before the Q3…
Read the issue →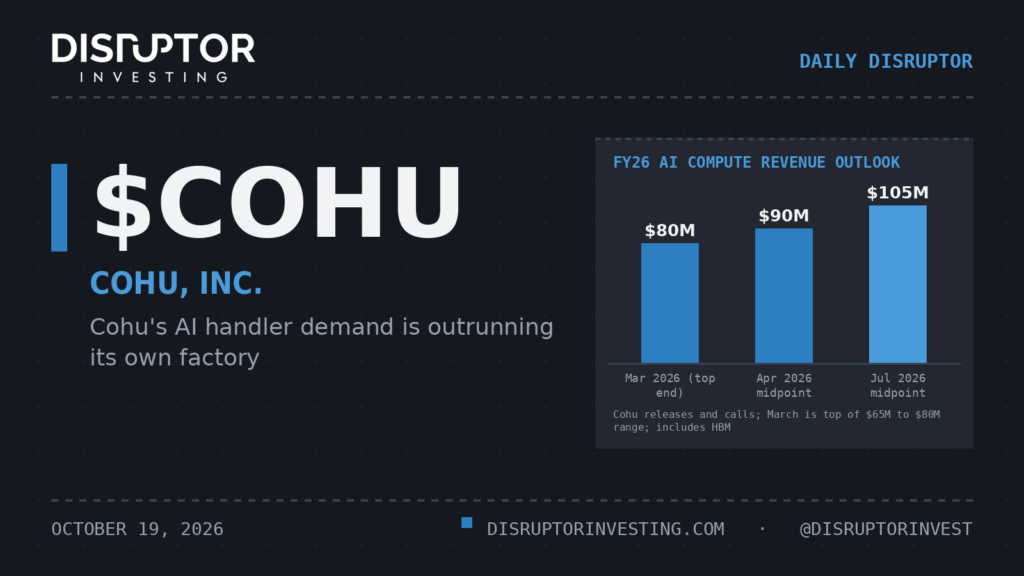
October 19, 2026
Daily Disruptor: $COHU, the AI test handler its own factory is holding back
Cohu's Eclipse handler for AI processors is sold out for 2026 and doubling capacity, and results land October 28.
Read the issue →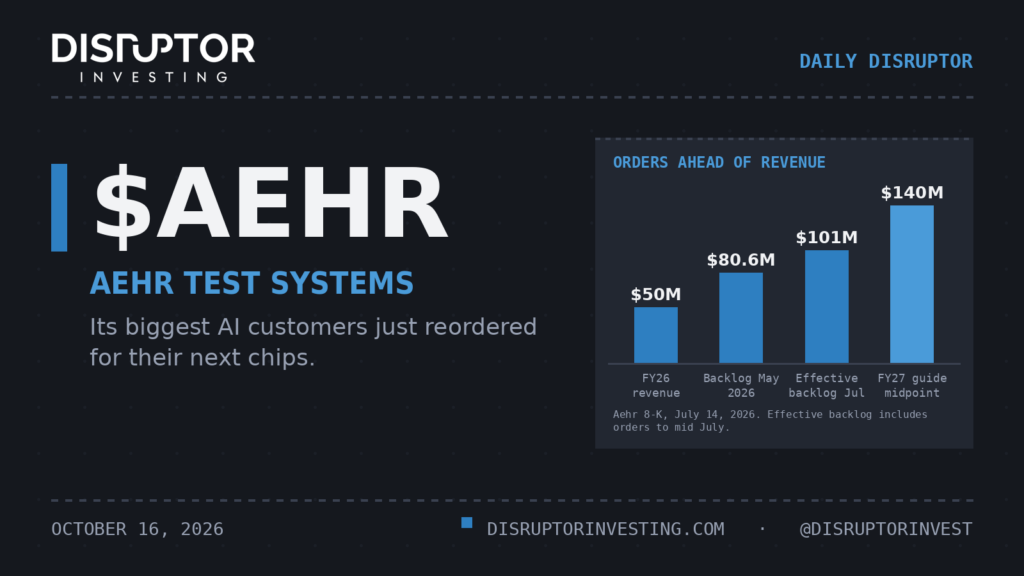
October 16, 2026
Daily Disruptor: $AEHR, the AI chip stress test with $100M already booked
Aehr holds AI burn in orders worth twice last year's revenue, its lead hyperscaler just picked it for a second chip, and the backlog faces its…
Read the issue →