← All sectors / The AI transformation
040 · Geothermal & next generation baseload
Drilling for always on power
Curve position
Binding constraint
Cost per well, which decides whether the resource is economic outside prime geology.
Why this sector sits at Liftoff
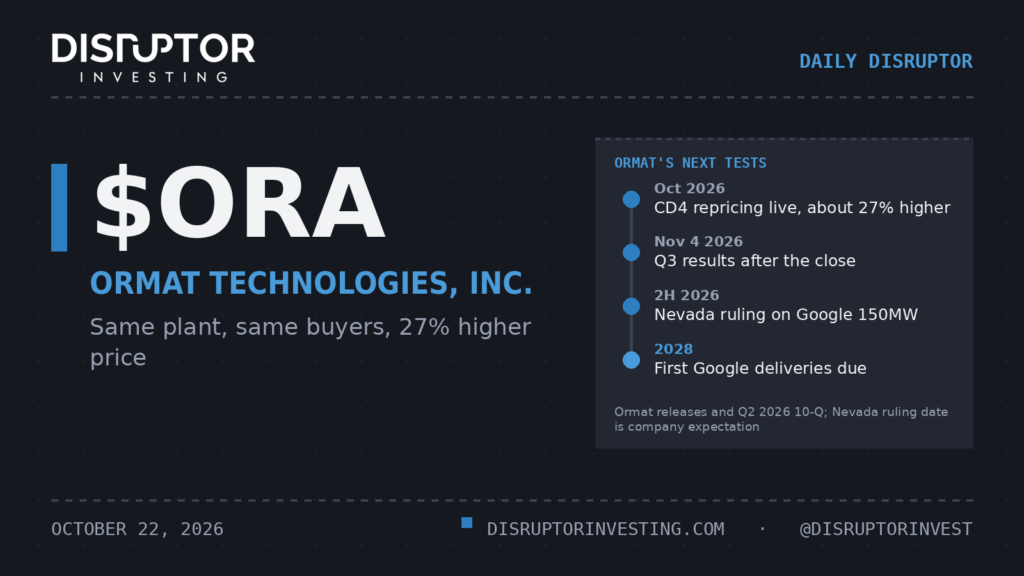
The binding constraint for next-generation geothermal has been proving that enhanced geothermal can deliver contracted power at utility scale, on schedule. On September 30, 2026, Cape Station's first 33 MW GeoBlock reached commercial operation, one day early. It is earning revenue under a PPA, with about 900 MW of Cape Station offtake signed, including Southern California Edison.
The market has not priced this in. Fervo listed at $27 in May 2026, peaked above $42, and now trades in the low teens with scattered analyst targets. The real risk is a short report Morpheus Research published on October 6, 2026. It alleges thermal decline, water loss and earthquake-related equipment damage, which goes straight to whether the constraint has truly eased.
If those claims hold up, we would move the sector back to Launch Pad. Our evidence covers geothermal only, not advanced nuclear.
Reviewed on a two month cycle. The position moves only when a dated, verifiable change in the binding constraint justifies it.
Heatmap / How this sector's stocks are moving
| Stock | Price | 1 Day | 1 Week | 1 Month | Year to date |
|---|---|---|---|---|---|
| $ORA | $94.28 | +0.10% | +2.86% | +1.30% | −14.66% |
| $FLR | $47.61 | −0.79% | +1.36% | −8.44% | +20.14% |
| $BKR | $49.87 | −5.53% | −8.76% | −12.71% | +9.51% |
| $HAL | $33.00 | −3.14% | −7.72% | +0.86% | +16.77% |
| $SLB | $51.56 | −1.09% | −4.07% | +3.12% | +34.34% |
| Sector average | −2.09% | −3.27% | −3.17% | +13.22% |
Prices as of November 5, 2026. The sector's move is the equal-weighted average of these listed companies, a market proxy for context, not recommendations. See it on the full heatmap →
Sentiment / The mood in this sector's stocks
Since 2018, Geothermal & next generation baseload has been in Skepticism and steady 25 separate times. After those, its stocks beat their usual three months 12 times (48%), by a median of −1.2 points.
Confidence: low, a split like this is common by chance, so no edge is called.
Geothermal has always worked. It just only worked in a handful of places with unusually accessible heat. Enhanced and closed loop techniques, many borrowed directly from two decades of shale drilling, are extending the resource to ordinary geology, and that changes the addressable market from niche to continental.
Historical context explains the neglect. Conventional geothermal required rare geology, so it stayed a rounding error in the energy mix while wind and solar scaled. The drilling revolution that unlocked American shale never got pointed at heat until recently, and the learning curve is now compressing fast.
The structural driver is the specific shape of AI demand. Data centers need firm power around the clock in the same locations for decades. Geothermal produces exactly that profile with no fuel cost and a small footprint, which is why hyperscalers have started contracting for it directly rather than waiting for utilities.
The technology layer covers enhanced geothermal systems that fracture hot dry rock, closed loop designs that circulate fluid through sealed wellbores, advanced drill bits and directional tools that survive high temperature, and the subsurface modeling that decides where to drill. AI is central to that last piece.
Adoption economics hinge on one number: cost per well. Each project drilled teaches the next, and the trajectory so far mirrors the early shale learning curve. When cost per megawatt crosses the threshold utilities pay for firm capacity, the resource opens up across enormous geography at once.
The beneficiaries include drilling contractors and oilfield service companies redeploying idle capability, drill bit and downhole tool manufacturers, turbine and heat exchange suppliers, and the developers holding leases in favorable geology.
The value chain runs from subsurface exploration through drilling and completion to surface power generation and offtake. The drilling tier is where existing public companies already have skills, equipment, and crews, which makes them the fastest exposure to the thesis.
The overlooked layer is unusually rich because the skills are hiding in a disliked sector: small and mid cap oilfield service firms, drill bit and tool specialists, high temperature electronics and instrumentation makers, and the engineering firms designing surface plants.
Competitive dynamics favor whoever accumulates drilling data fastest, since each well improves the model that sites the next one. Federal permitting reform and tax credit eligibility are the policy variables that decide project pace.
Risks: drilling is capital intensive and results vary by site, induced seismicity is a real permitting obstacle, projects can fail on subsurface surprises after significant spend, and the technology has to keep beating a falling cost curve in solar plus storage to stay relevant.
What to watch: cost per well disclosures, hyperscaler power purchase agreements with geothermal developers, permitting reform progress, and drilling contractor backlog shifting toward geothermal. The research follows the learning curve, because that is what decides the market size.
Coverage / Daily Disruptor issues in this sector