← All sectors / The AI transformation
109 · Grid scale energy storage
Holding the electron until it is needed
Curve position
Binding constraint
Cell supply and interconnection, not the case for storage itself.
Why this sector sits at Liftoff
Storage economics crossed the threshold where it competes with peaking generation on cost rather than on subsidy, and interconnect reform gave it dated access.
We move this back from Flight to Liftoff because the repricing has been narrow, concentrated in a few names, while the underlying constraint change applies broadly.
Reviewed on a two month cycle. The position moves only when a dated, verifiable change in the binding constraint justifies it.
Heatmap / How this sector's stocks are moving
| Stock | Price | 1 Day | 1 Week | 1 Month | Year to date |
|---|---|---|---|---|---|
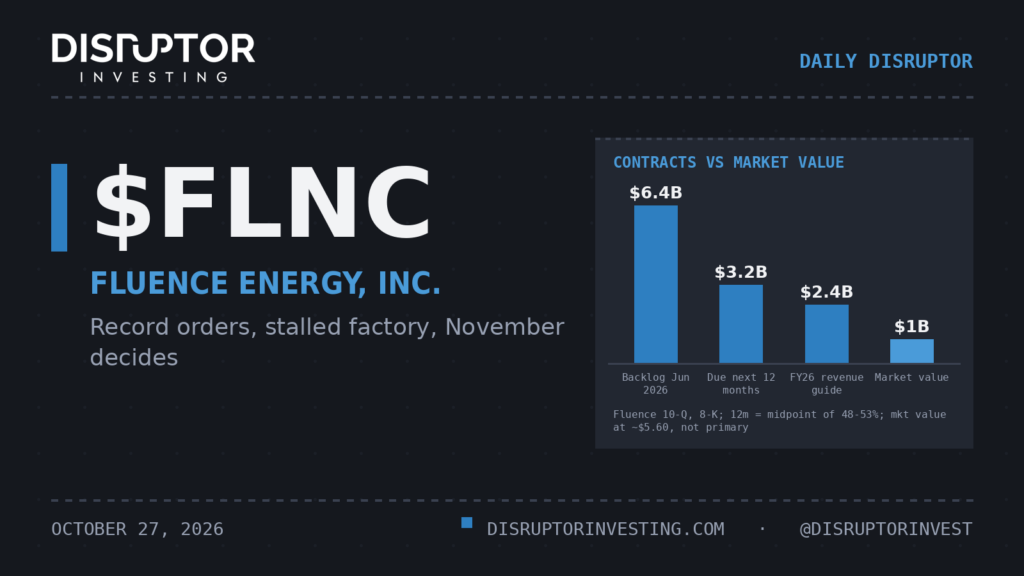
| $FLNC | $6.06 | +10.18% | −2.10% | −24.53% | −69.36% |
| $EOSE | $2.14 | +12.63% | +9.74% | −34.36% | −81.33% |
| $TSLA | $385.19 | −3.34% | −4.71% | +1.18% | −14.35% |
| $GEV | $832.83 | −9.30% | −5.15% | −19.08% | +27.43% |
| $STEM | $2.88 | +21.52% | +12.50% | −39.62% | −80.86% |
| Sector average | +6.34% | +2.06% | −23.28% | −43.69% |
Prices as of November 5, 2026. The sector's move is the equal-weighted average of these listed companies, a market proxy for context, not recommendations. See it on the full heatmap →
Sentiment / The mood in this sector's stocks
Since 2021, Grid scale energy storage has been in Capitulation and steady 6 separate times. After those, its stocks beat their usual three months 4 times (67%), by a median of +11.4 points.
Confidence: low, too few past episodes to call an edge.
Solar produces at midday and wind produces when it wants to. Storage is the piece that turns both into something a grid operator can dispatch, and in several markets it now pays for itself on arbitrage and capacity payments alone.
Historically storage meant pumped hydro, which requires specific geography and decades of permitting. Lithium cells changed that by making storage a manufactured product that can be sited almost anywhere in months.
The structural driver is duck curve economics. As solar penetration rises, midday power becomes worthless and evening power becomes expensive, and the spread between them is what storage monetises.
The technology layer spans lithium iron phosphate cells favoured for stationary use, battery management systems, power conversion equipment, thermal management, long duration chemistries including flow and iron air, and the software that bids storage into markets.
Adoption economics are now attractive in markets with volatile pricing and capacity payments. Where those mechanisms do not exist, projects still depend on incentives.
The beneficiaries include cell manufacturers focused on stationary applications, system integrators, power conversion equipment makers, developers with interconnection positions, and the software firms optimising market bidding.
The value chain runs from cells through integration and installation to market operation. Interconnection rights and market bidding software are where the least appreciated value sits.
The overlooked layer includes power conversion equipment makers, fire suppression and safety specialists, thermal management suppliers, and the trading software that decides when to charge and discharge.
Competitive dynamics favour integrators with proven safety records, since a battery fire is an existential event for a project developer and increasingly for a permitting authority.
Risks: cell pricing is volatile and supply is concentrated, interconnection queues delay projects for years, safety incidents attract regulatory response, and market rules can change to reduce arbitrage opportunity.
What to watch: cell pricing trends, interconnection queue positions held by developers, capacity market rule changes, and storage additions by market.
Coverage / Daily Disruptor issues in this sector