← All sectors / The AI transformation
102 · Rare earth magnets & motor supply
The magnet in everything that moves
Curve position
Binding constraint
Separation and metallisation capacity outside the dominant producer.
Heatmap / How this sector's stocks are moving
| Stock | Price | 1 Day | 1 Week | 1 Month | Year to date |
|---|---|---|---|---|---|
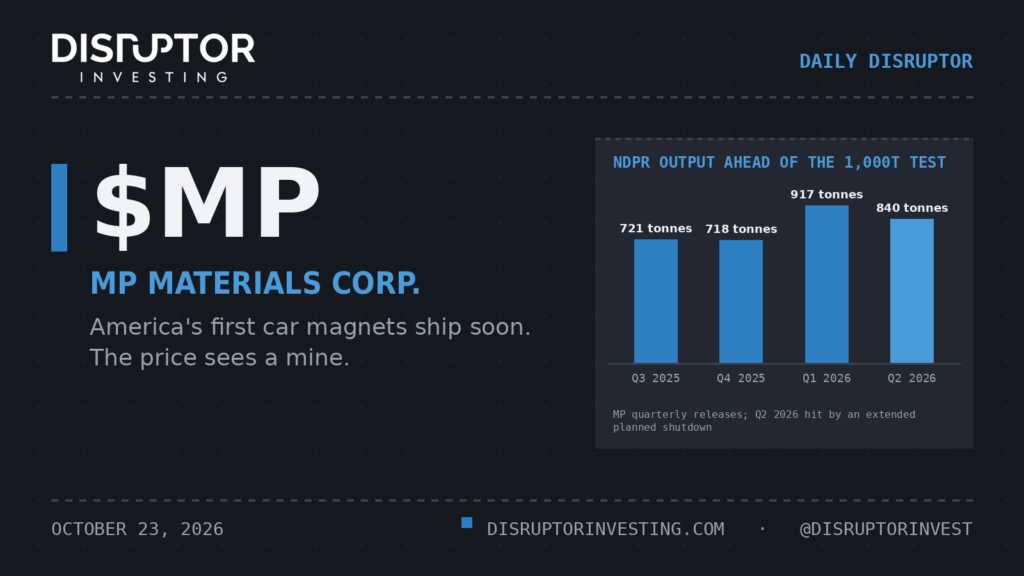
| $MP | $35.91 | −5.08% | −12.54% | −26.00% | −28.92% |
| $USAR | $8.20 | −5.86% | −21.76% | −40.32% | −31.09% |
| $LYSDY | $8.55 | −0.47% | −5.52% | −3.50% | +3.39% |
| $ARRNF | $0.20 | −3.61% | −8.50% | −15.97% | −4.76% |
| Sector average | −3.75% | −12.08% | −21.45% | −15.35% |
Prices as of November 5, 2026. The sector's move is the equal-weighted average of these listed companies, a market proxy for context, not recommendations. See it on the full heatmap →
Sentiment / The mood in this sector's stocks
Since 2019, Rare earth magnets & motor supply has been in Capitulation and steady 11 separate times. After those, its stocks beat their usual three months 5 times (45%), by a median of −1.9 points.
Confidence: low, a split like this is common by chance, so no edge is called.
Permanent magnets sit inside electric motors, wind turbines, hard drives, robotics, and defence systems. The supply chain for them is concentrated in a way that few industrial inputs are, and every electrification forecast assumes magnets that do not yet have diversified supply.
Historically the West mined rare earths and then ceded processing on cost grounds. Mining is the easy part; separation, metallisation, and magnet manufacture are the hard parts, and those capabilities atrophied.
The structural driver is demand growth from motors and turbines colliding with export controls and industrial policy. Governments now treat magnet supply as a security matter rather than a procurement one.
The technology layer spans separation chemistry, metal and alloy production, sintered and bonded magnet manufacture, recycling from end of life motors and drives, and the magnet free motor designs that sidestep the problem entirely.
Adoption economics are policy assisted. Domestic magnet production is more expensive, and it happens where subsidy, offtake agreements, or defence requirements close the gap.
The beneficiaries include magnet manufacturers building capacity outside the dominant producer, separation and processing firms, magnet recyclers, and the motor designers reducing or eliminating rare earth content.
The value chain runs from ore through separation and metal to magnet and motor. Separation is the genuine bottleneck, not mining, which is where most public attention wrongly goes.
The overlooked layer includes separation technology licensors, magnet recycling firms, alloy producers, and the specialist equipment makers for sintering and machining.
Competitive dynamics are shaped almost entirely by policy. Where governments fund capacity and guarantee offtake, projects proceed; where they do not, the cost gap prevents it.
Risks: the dominant producer can move prices to make new entrants uneconomic, projects have long build times, demand forecasts assume electrification rates that may not materialise, and magnet free designs could reduce the addressable market.
What to watch: separation capacity commissioned outside the dominant producer, export control announcements, offtake agreements with automakers and defence primes, and magnet recycling volumes.
Coverage / Daily Disruptor issues in this sector