
The 30 second version
- Ultralife (ULBI) designs and manufactures defense batteries and tactical communications hardware for military and government customers worldwide
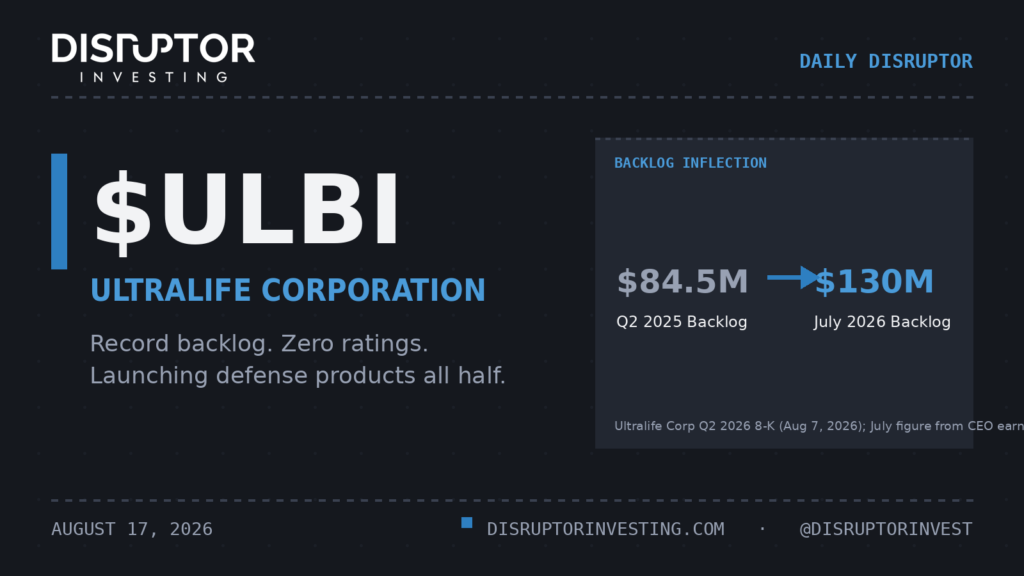
- Backlog hit a record $117.5 million at June 30, up 39% year over year, and had already grown to nearly $130 million by July, the CEO said so on the August 7 call
- Communications Systems revenue jumped 39.3% in Q2; gross margin expanded 500 basis points year over year to 28.9%; adjusted EBITDA rose from $4.1M to $6.1M
- Catalyst: multiple new defense product launches in H2 2026, including StrikeHub, the Crescent edge compute wearable, and a 20-watt amplifier under global evaluation; Q3 earnings expected November
- Main risk: thin cash ($6.7M) against $44.6M in debt, and revenue has yet to catch up to the backlog build; market cap is roughly $110M
There is exactly one formal analyst rating on Ultralife Corporation. One. The stock has a micro cap market value of roughly $110 million, trades about 50,000 shares a day, and is covered by nobody at the major banks. That gap between what the filings show and what the Street has priced in is the entire trade.
The Q2 earnings dropped August 7, and the stock jumped 19% the same morning. Most of the people who bought that day have already moved on. They saw the pop, missed the setup, and will not look again until the Q3 print in November. That is where we come in.
What just happened
Ultralife reported Q2 2026 results on August 7. Revenue of $47.9 million was slightly softer than a year ago, which is the number casual screeners will remember. Everything else pointed in the other direction. Gross margin expanded from 23.9% to 28.9% year over year. Adjusted EBITDA rose 49%, from $4.1 million to $6.1 million. Operating income climbed to $3.4 million despite $0.9 million in one time charges. GAAP EPS tripled, from $0.05 to $0.15.
The more consequential figure was the backlog. $117.5 million at June 30, the highest in the company’s history and 39% above where it stood twelve months earlier. Then CEO Mike Manna gave analysts a live update: by July, the backlog had grown to nearly $130 million. That is not steadiness. That is acceleration, and it means Q3 revenue has a foundation that Q2 did not have when it opened.
The company also confirmed that the Falcon manpack battery program, awarded to L3Harris by the U.S. Army for Next Generation Command and Control, will use Ultralife components. The company expects to supply batteries and related systems as L3Harris ramps production. That program was not in the backlog number. It is incremental.
The business
Ultralife makes two things. The larger segment, Battery and Energy Products, produces lithium ion cells and packs, primary lithium batteries, and specialty power systems for defense, medical, and industrial customers. The smaller segment, Communications Systems, designs and sells ruggedized tactical hardware including vehicle mount networking gear, amplifiers, edge compute solutions, and the new StrikeHub product line targeting Special Operations Forces and Army Next Gen Command and Control. Battery revenue runs around $44 million per quarter; Communications is only $3 to 4 million per quarter but growing fast and carrying a different margin profile.
The detail most readers will not find: the company acquired Electrochem Solutions in November 2024 specifically to gain internal cell production capability. Most battery companies buy cells externally and assemble them. Ultralife is now vertically integrating the cell itself, which means gross margin in the Battery segment has structural room to expand as Electrochem’s cell output feeds internal production rather than being sourced from outside. Management quantified two specific manufacturing improvements at the Newark and Raynam facilities that together are expected to save $600,000 to $800,000 annually in gross margin, with the second initiative beginning to contribute in mid Q3.
The numbers
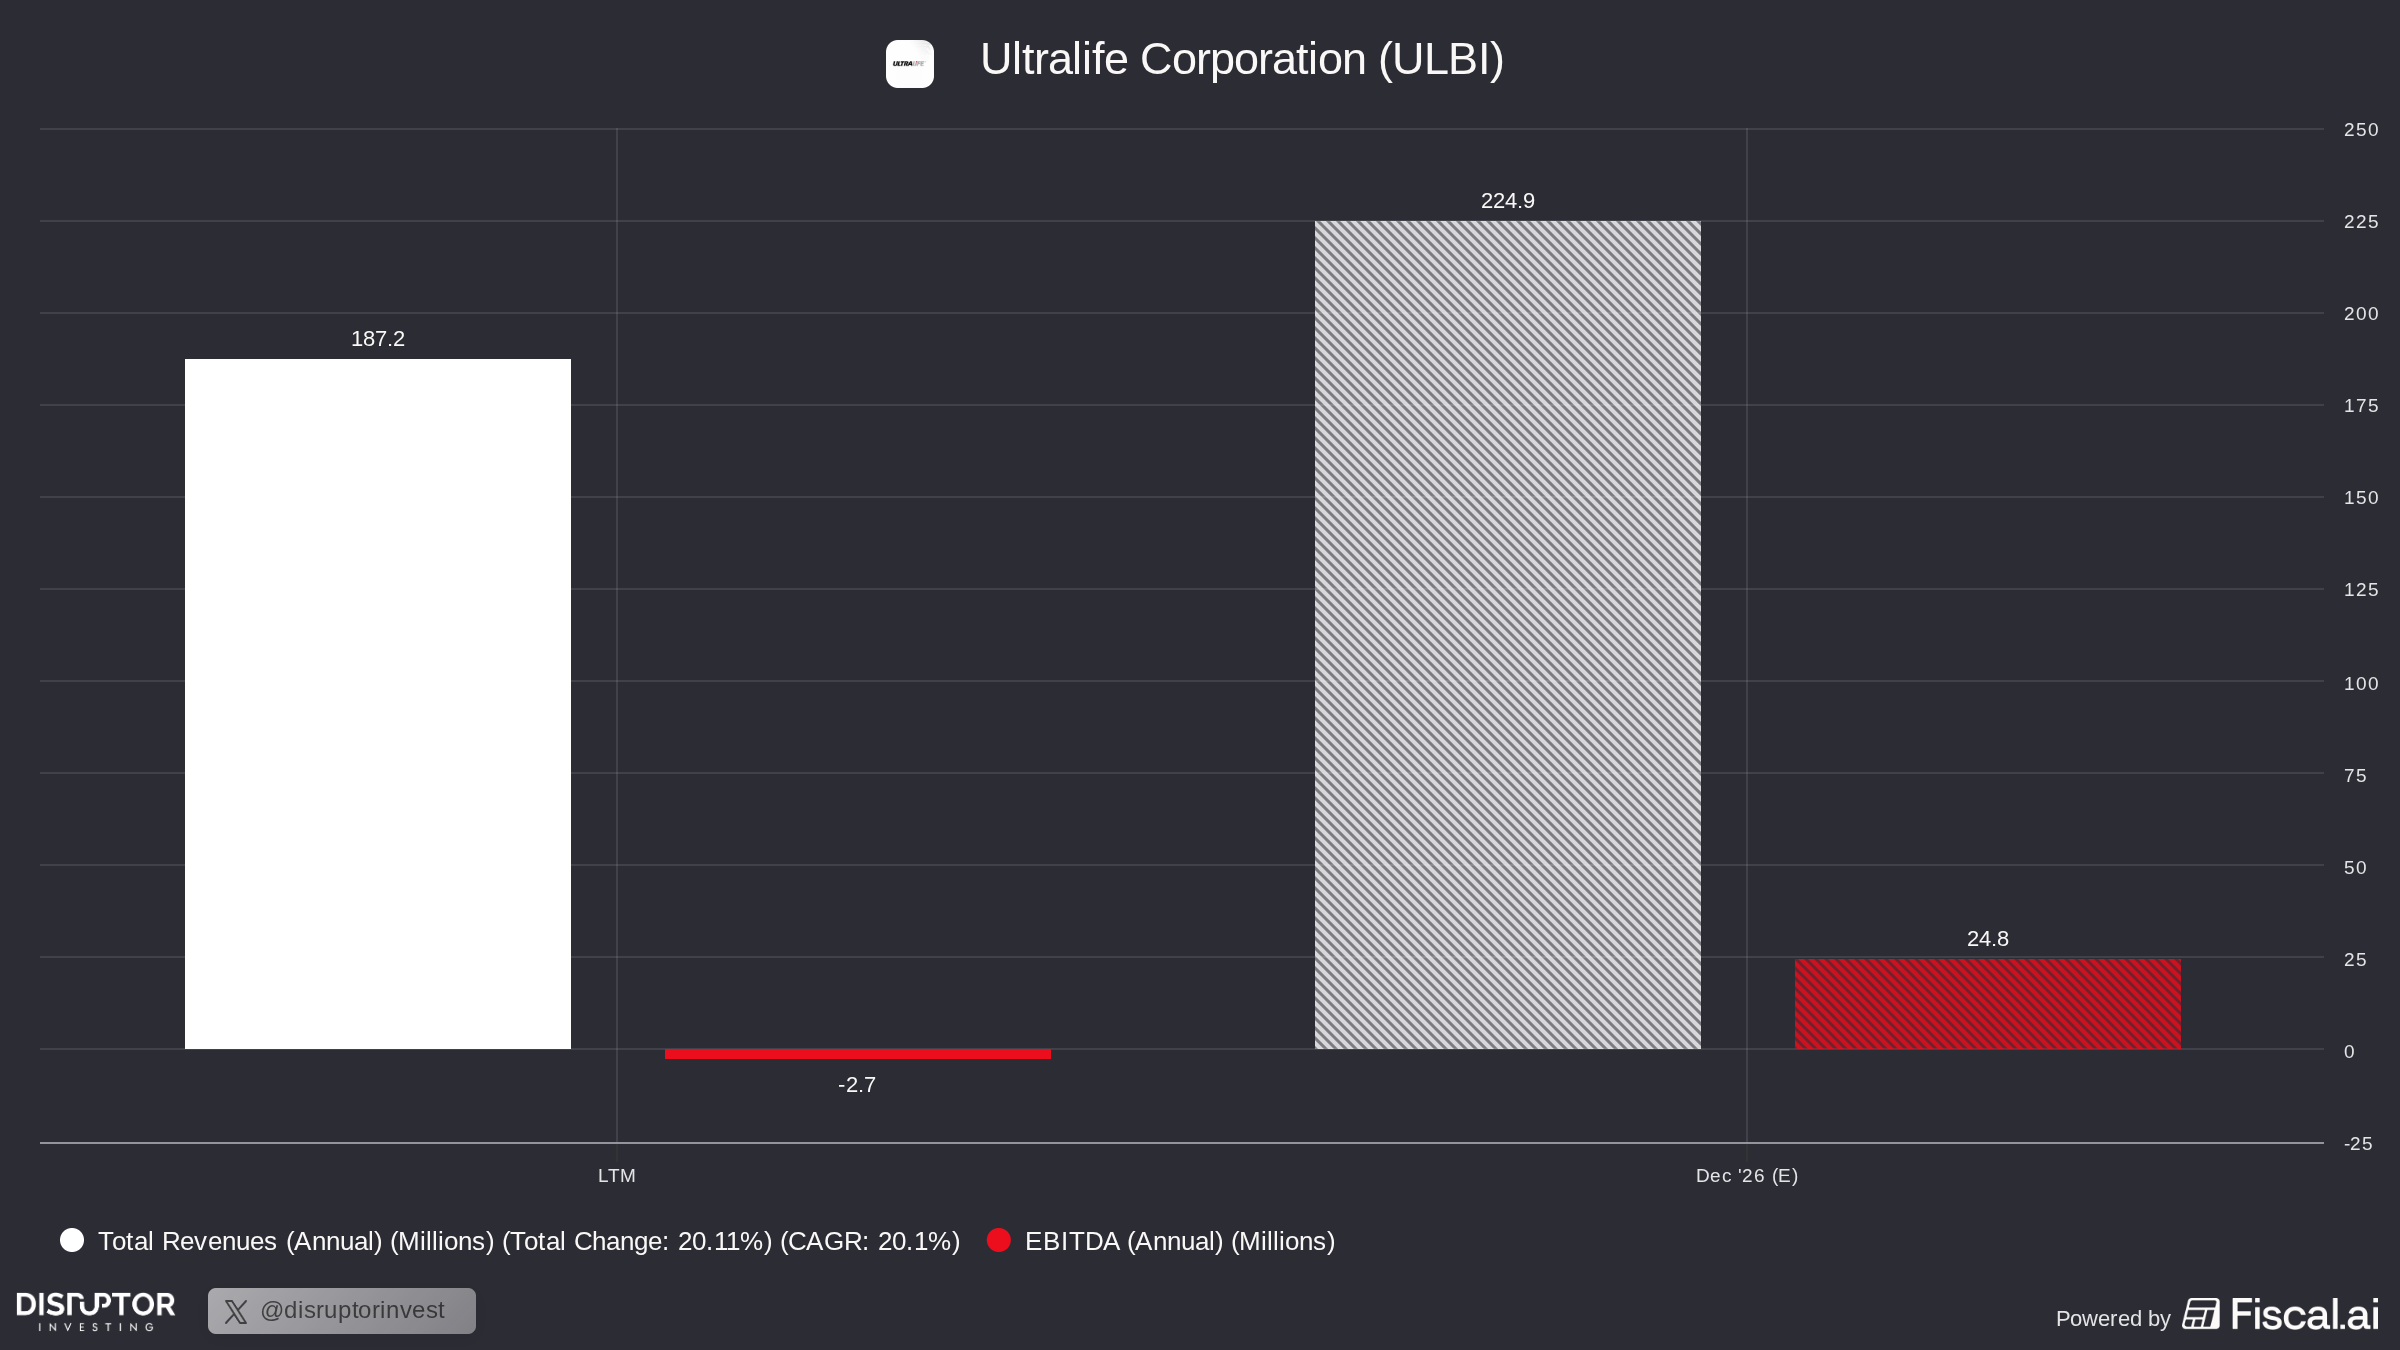
For the first half of 2026, revenue was $95.4 million against $99.3 million in the same period of 2025. That trailing number looks soft. The forward picture does not. Consensus for full year 2026 sits at $229.4 million in revenue and $0.95 in EPS, compiled from only three analysts, with no formal guidance issued by management. The company would need roughly $134 million in H2 revenue to reach that number. Given a backlog of $130 million already on hand, the math is at least plausible, and Q2 showed the margin structure improving fast enough to make the earnings number meaningful when revenue converts.
On the balance sheet, cash was $6.7 million and total debt was $44.6 million at June 30. That is tight, and we are not pretending otherwise. Management has a revolving credit facility and guided to positive operating cash flow for the year. Adjusted EBITDA of $6.1 million in a single quarter, annualized, covers interest comfortably. The company is not diluting to survive: share count has been essentially flat. Director Bradford Whitmore bought 108,878 shares in the 90 days through May at an average near $6.81. Insiders do not typically do that when they expect a capital raise.
Why the market has not caught up
The positioning is almost comically thin. Institutional ownership sits at just 30.7%, and the most recent 13F data shows net accumulation rather than distribution. There are zero formal price targets from major brokers. The one existing rating, from Josh Sullivan at Benchmark, carries a $14 target against a current price around $6.50 to $7. The stock screen that most fundamental investors run, which sorts by revenue direction, would still flag ULBI as a revenue decliner because the trailing six months are below the prior year. Nobody running that screen will find this name until the H2 numbers print. That is the information gap.
The specific mismatch is this: a company with a backlog worth more than its entire market cap, a gross margin that just inflected 500 basis points in one year, a communications business growing at 39%, new defense programs entering the revenue stream in the second half, and essentially zero sell side coverage. At roughly 0.5 times trailing revenue and less than 1 times the backlog, the valuation is not asking you to trust a forecast. It is asking you to notice that the orders are already booked.
What breaks it
The balance sheet is the primary risk and we will not soften it. Cash of $6.7 million against $44.6 million in total debt means any operational disruption, like the Q1 power outage at the Newark facility that cost several production days, hits the P&L before there is a liquidity cushion to absorb it. Revenue has to show up in H2 or the full year consensus number becomes a problem. The Communications Systems business is also inherently lumpy: it depends on defense program timing, and a slip in a contract award or a delivery push out will compress that 39% growth rate fast. Revenue was still modestly below year ago levels in Q2 despite everything else going right. The backlog converts eventually. The question is the quarter it does.
What we are watching
- H2 2026 product launches: StrikeHub, the Crescent wearable edge compute system, and the 20-watt amplifier are all in commercial capture phase; first meaningful orders or formal program wins would confirm the Communications segment inflection before the Q3 print
- Q3 earnings (est. November 2026): this is the first quarter where the backlog growth, the second manufacturing fix, and the new product launches should all appear in the revenue line simultaneously; the spread between $84.5M backlog a year ago and $130M today has to show up somewhere
- OEM rechargeable power pack certification (Q4 2026): management said certifications are on track for Q4, with deliveries beginning early 2027; a confirmed certification removes one more binary from the forward revenue picture
Not financial advice.
References
- Ultralife Corporation. Form 8-K, Second Quarter 2026 Operating Results (Exhibit 99.1). US Securities and Exchange Commission. Published August 7, 2026. Accessed August 17, 2026. https://www.globenewswire.com/news-release/2026/08/07/3341025/18622/en/ultralife-corporation-reports-second-quarter-results.html
- Ultralife Corporation. Form 10-Q for the quarterly period ended June 30, 2026. US Securities and Exchange Commission. Accessed August 17, 2026. https://www.sec.gov/Archives/edgar/data/0000875657/000143774926026432/ulbi20260630_10q.htm
- StockTitan. Ultralife Q2 Earnings: $0.15 EPS, $117.5M Backlog. Published August 7, 2026. Accessed August 17, 2026. https://www.stocktitan.net/news/ULBI/ultralife-corporation-reports-second-quarter-ol1w1nqqkmfq.html
- Investing.com. Earnings call transcript: Ultralife posts Q2 2026 profit gain, shares rise premarket. Published August 7, 2026. Accessed August 17, 2026. https://ca.investing.com/news/transcripts/earnings-call-transcript-ultralife-posts-q2-2026-profit-gain-shares-rise-premarket-93CH-4786990
- Yahoo Finance. Ultralife Corp (ULBI) Q2 2026 Earnings Call Highlights. Published August 7, 2026. Accessed August 17, 2026. https://finance.yahoo.com/markets/stocks/articles/ultralife-corp-ulbi-q2-2026-190154876.html
- Gurufocus. Ultralife Corp (ULBI) Q2 2026 Earnings Call Highlights: Record Backlog and Margin Expansion Drive Optimism. Published August 2026. Accessed August 17, 2026. https://www.gurufocus.com/news/9017960/ultralife-corp-ulbi-q2-2026-earnings-call-highlights-record-backlog-and-margin-expansion-drive-optimism
- The Stock Observer. Ultralife Q2 Earnings Call Highlights. Published August 7, 2026. Accessed August 17, 2026. https://www.thestockobserver.com/2026/08/07/ultralife-q2-earnings-call-highlights.html
- ChartMill. Ultralife Corporation (NASDAQ:ULBI) Plunges 8% on Q1 2026 Revenue and Earnings Miss. Published May 8, 2026. Accessed August 17, 2026. https://www.chartmill.com/news/ULBI/Chartmill-48016-Ultralife-Corporation-NASDAQULBI-Plunges-8-on-Q1-2026-Revenue-and-Earnings-Miss
- MarketBeat. Ultralife (ULBI) Institutional Ownership. Accessed August 17, 2026. https://www.marketbeat.com/stocks/NASDAQ/ULBI/institutional-ownership
- TickerNerd. ULBI Stock Forecast 2026, Ultralife Price Targets & Predictions. Accessed August 17, 2026. https://tickernerd.com/stock/ulbi-forecast/
- StockAnalysis. Ultralife (ULBI) Stock Forecast & Analyst Price Targets. Accessed August 17, 2026. https://stockanalysis.com/stocks/ulbi/forecast/