
The 30 second version
- What it does: Designs mixed signal semiconductors and perception software for automotive ADAS, humanoid robotics, and quantum systems.
- The number: Q3 2026 revenue guided to $70M at the midpoint, implying 30% year over year growth, accelerating from 24% in Q2.
- The catalyst: Q3 earnings on November 5, 2026, plus a pending $135M Wuxi divestiture close that would dramatically extend the balance sheet runway.
- The main risk: Chinese regulatory approval for the Wuxi sale could slip or fail, leaving a lower margin segment on the books and a tighter cash position.
- Market cap: Roughly $880M, trading about 44% below its 52-week high despite accelerating top line growth.
There is a chip company in Aliso Viejo, California, whose non GAAP operating loss fell 39% year over year in the most recent quarter, even as revenue grew 24%. The market has not moved. The stock sits at roughly $3.35, miles from its $6.05 high twelve months ago. That is the setup.
What changed this week is that we are now less than two months from a Q3 earnings print that management guided to 30% year over year growth. The quarter has almost certainly already closed. The results are sitting in a spreadsheet somewhere. That print lands November 5, and the stock has barely reacted to any of the positive operating news that has accumulated since August.
What just happened
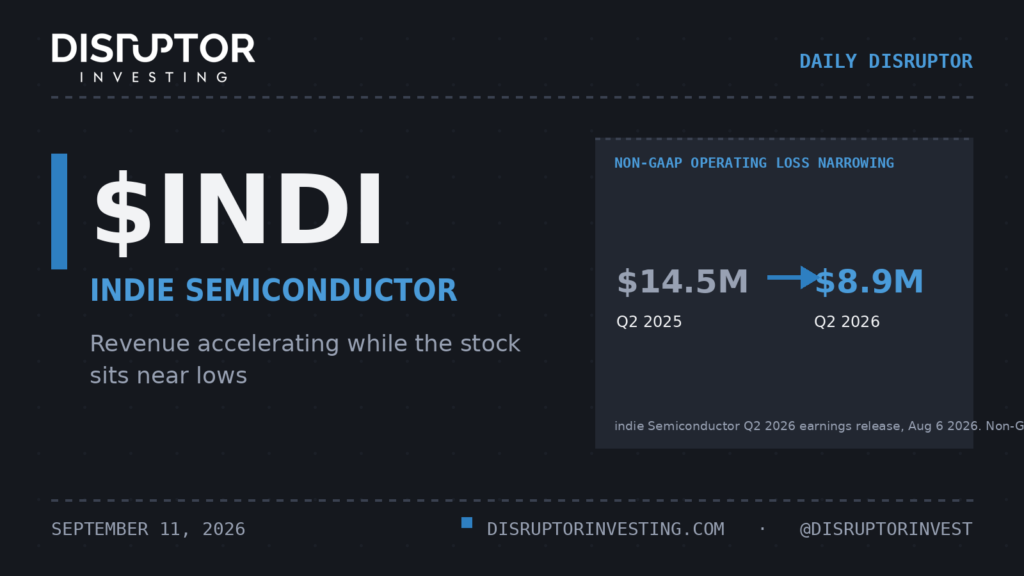
indie Semiconductor’s Q2 2026 results, published August 6, beat the revenue consensus. The company reported $64 million in revenue, up 24% from a year earlier and $2 million above the midpoint of its own guidance. Non GAAP operating loss narrowed to $8.9 million from $14.5 million in Q2 2025. That is a 39% improvement on the loss line while the top line was growing. Both things moving in the right direction at once.
Management then guided Q3 revenue to $67 to $73 million, with a midpoint of $70 million. That implies 30% year over year growth, faster than Q2’s 24%, and faster than Q1’s 3%. The growth rate is accelerating quarter by quarter. The Q2 earnings release also confirmed a new radar design win with a Tier 1 supplier supporting Volvo, alongside physical AI design wins at humanoid robotics companies Unitree and Agibot, opening a line of business that did not exist two years ago.
The business
indie designs and sells semiconductors, photonics chips, and perception software to automotive OEMs and Tier 1 suppliers, targeting the ADAS systems that give cars the ability to see, sense, and react. Its flagship products cover radar at 77GHz, vision processing via the iND880 and iND881 SoCs, LiDAR signal processing, and an emerging photonics line that includes what the company claims is the world’s first commercially available 399nm ultraviolet DFB laser, aimed at quantum computing platforms. The same silicon that gives a car front facing radar is now being shipped into humanoid robots made by Unitree and Agibot in China.
The detail that only shows up if you read the filings: indie does not report a separate GAAP or non GAAP gross margin line, because some manufacturing costs are expensed inside research and development rather than cost of goods sold. That makes the company harder to compare to peers on a margin basis, which is one reason the market tends to overlook it. What you can track is the non GAAP operating loss trajectory, which has been improving consistently for six quarters. The company also holds over 600 patents, has shipped more than 550 million SoCs in total, and supplies product into every top global OEM.
The numbers
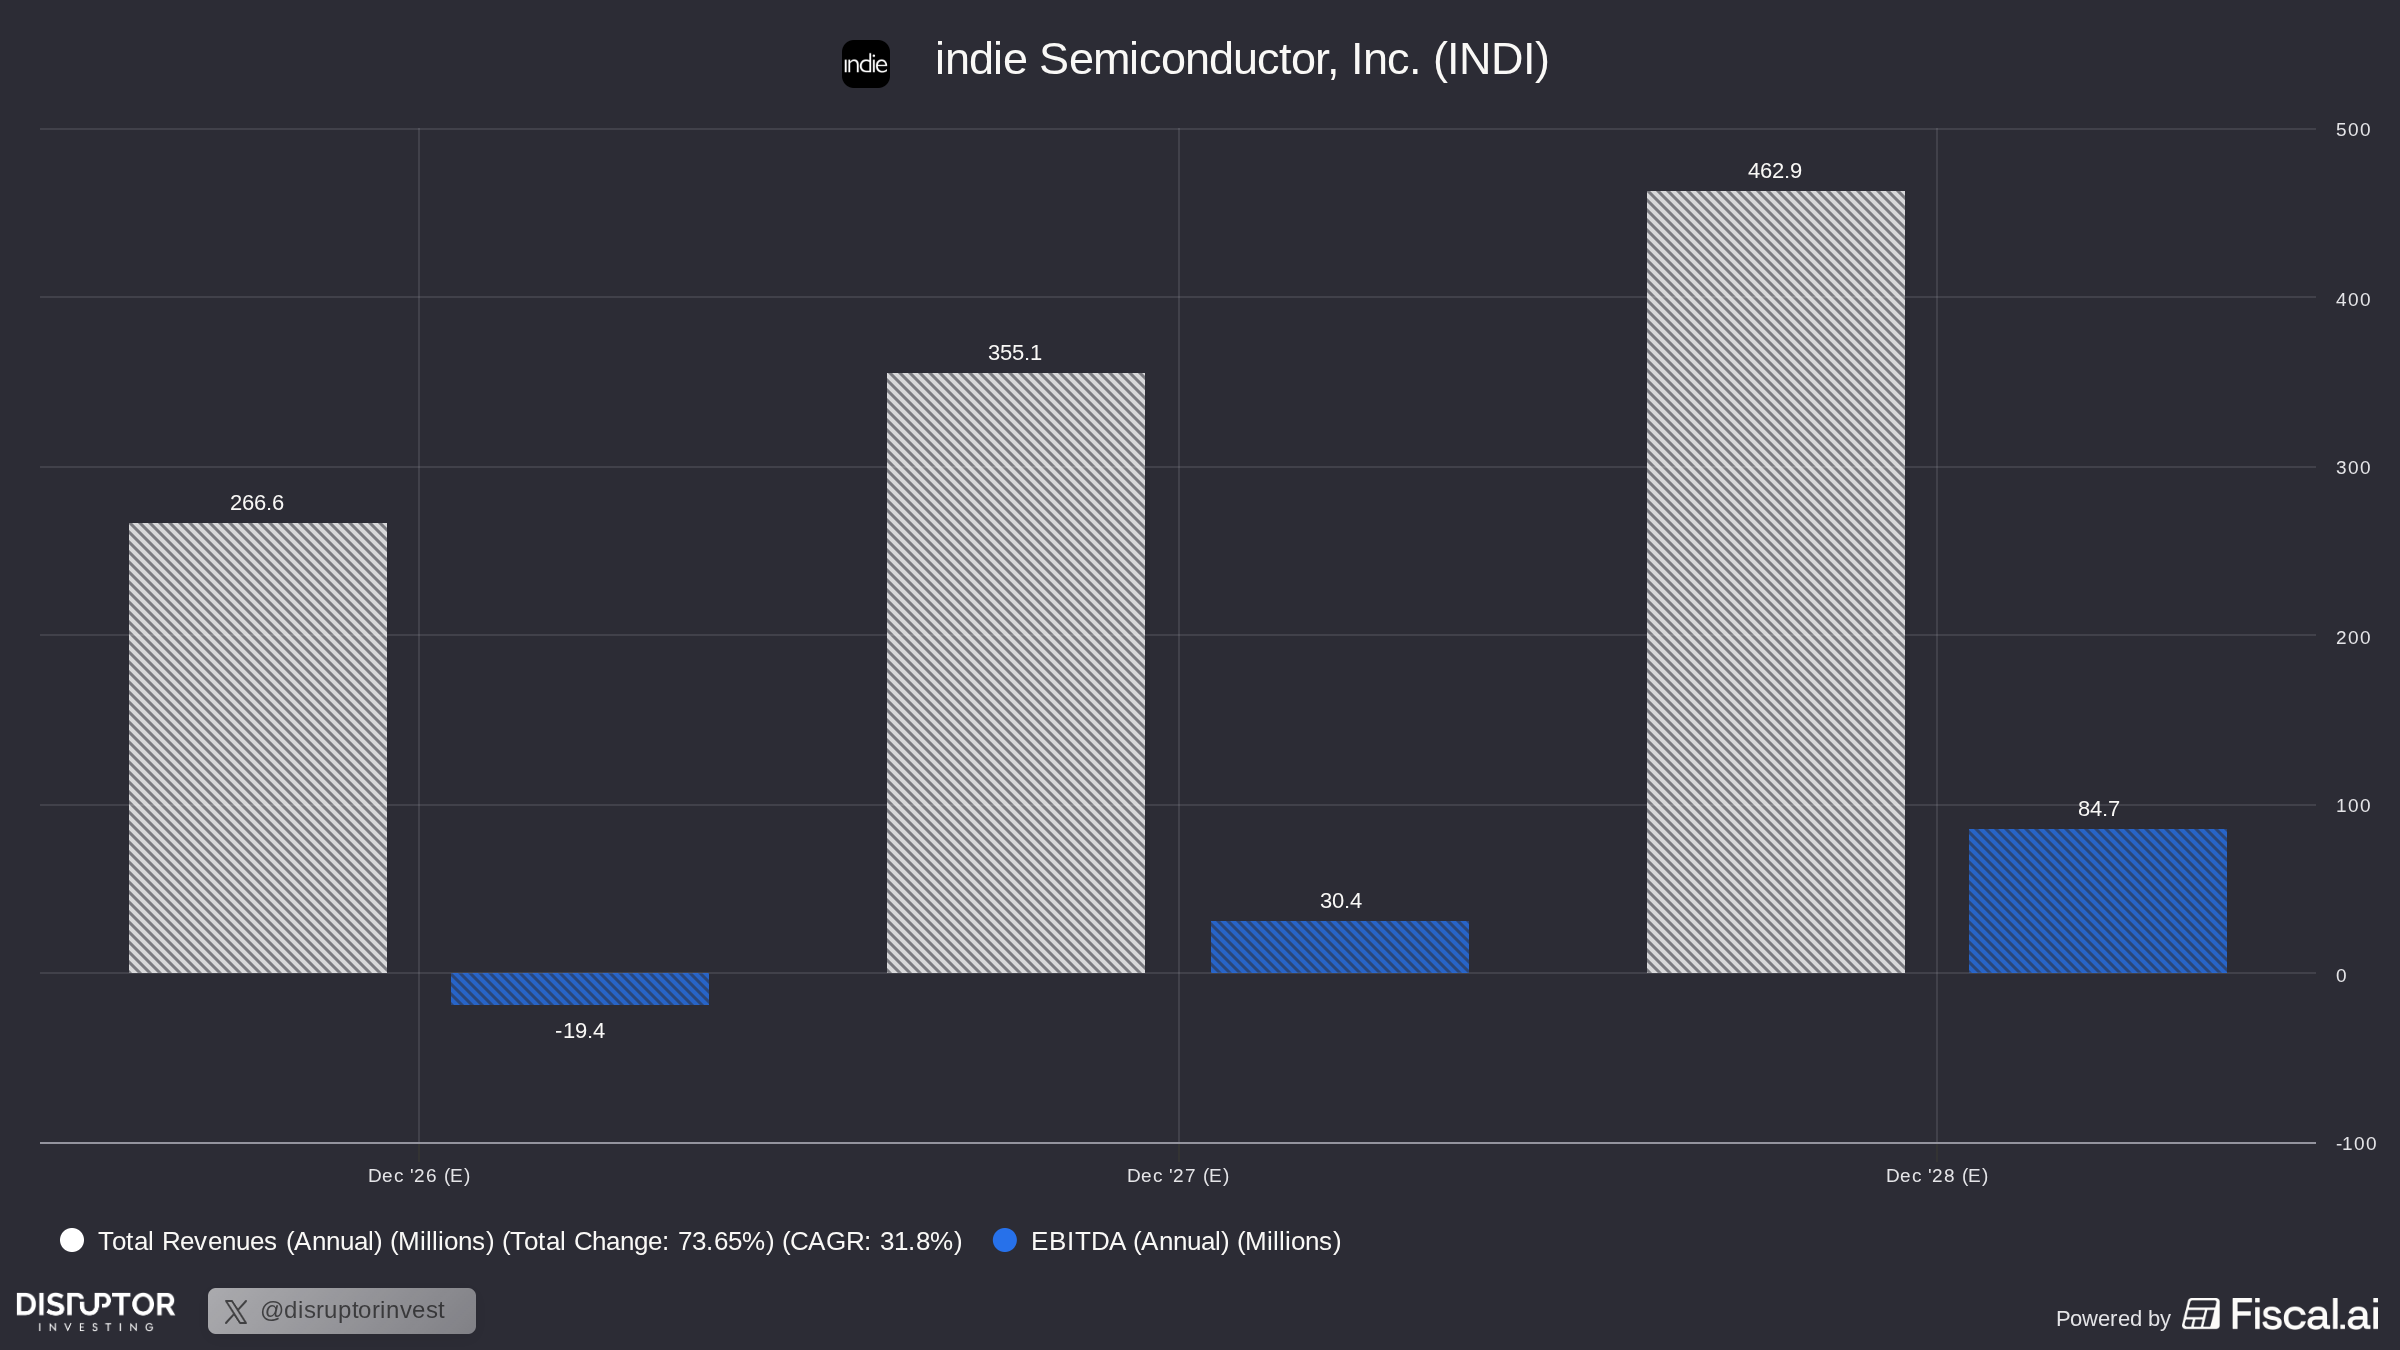
Revenue grew 24% in Q2 and is guided to grow 30% in Q3. The full year 2026 consensus across eight analysts sits at roughly $268 million, which would represent approximately 23% growth over FY2025’s $217 million. Analysts have trimmed revenue forecasts modestly, down about 0.86% over the past three months, and six negative EPS revisions have landed versus zero positive ones. The guidance midpoint for Q3 of $70 million lines up almost exactly with the consensus of $70.4 million, meaning there is no large gap between what management said and what the street is modeling. Upside comes from execution, not from an estimate reset.
On the balance sheet, cash and equivalents stood at $149 million including restricted cash at the end of Q2, down from $184.7 million at Q1 end. Operating cash burn was roughly $51 million for the first half. At that run rate, the company has roughly three to four quarters of runway before the Wuxi proceeds become critical. The good news is that the $135 million Wuxi divestiture, if it closes, addresses that gap directly. In March, indie also refinanced its near term debt by issuing $170.5 million of 4% convertible notes due 2031, pushing out the nearest major maturity by four years. Stock based compensation ran at $17.9 million in Q2 alone, a meaningful drag that is rising, and dilution is real: the company had roughly 232 million shares outstanding as of early August. That figure will keep creeping up.
Why the market has not caught up
The short interest tells the story. Roughly 33% of the float was sold short as of the most recent data, with about 11.7 days to cover. Short interest has risen 22% since August 2025. That level of bearish positioning against an accelerating revenue line is unusual, and it points to a specific concern: the market does not believe the Wuxi divestiture closes on time, and therefore discounts the clean balance sheet scenario that indie’s management is describing. A significant portion of the bears are betting on regulatory delay in China. If that approval arrives before the November 5 earnings call, the squeeze dynamic becomes interesting quickly.
Coverage is not thin. Fourteen analysts follow the name, and 79% carry a buy rating. The average 12-month price target sits around $5.87, implying roughly 75% upside from the current price of $3.35. The gap is not about analyst discovery. It is about the market assigning high probability to a bad outcome on the Wuxi deal, combined with fatigue from a stock that has underperformed for two years. What the price does not reflect is that core business revenue, independent of Wuxi, grew sequentially in both Q1 and Q2 2026, and management guided it to roughly $40 million in Q3, continuing that trend.
What breaks it
The Wuxi divestiture is the single most important thing to watch. The sale to United Faith Auto Engineering is valued at approximately $135 million in cash, but it requires Chinese regulatory approval that has been pending since October 2025. Geopolitical tension between the US and China, shifting trade policy, and local shareholder approvals all create paths to delay or failure. If the deal does not close, indie carries a lower margin, Chinese government subsidy dependent business unit, its cash runway tightens materially, and the bear case gets louder. Separately, stock based compensation was $17.9 million in Q2 and rising. That is not going away. Investors who care about GAAP dilution have a legitimate grievance, and anyone modeling the share count higher than 230 million for the Q3 print should be aware the trajectory is up.
What we are watching
- Wuxi divestiture close: Management expects completion by year end 2026. A formal announcement of Chinese regulatory clearance, likely to arrive before November 5, is the single biggest near term catalyst outside earnings.
- Q3 earnings, November 5, 2026: The first print showing 30% year over year growth, and the quarter where core business revenue is guided to reach $40 million. The Q3 gross margin directon and SBC trend are the two lines to check immediately.
- ams OSRAM CMOS sensor acquisition close: Expected by year end 2026, pending regulatory approval. Adds a fabless CMOS imaging sensor product line and is described by management as immediately accretive. Closing confirmation removes a second strategic uncertainty.
Not financial advice.
References
- indie Semiconductor, Inc. Form 10-Q for the quarterly period ended March 31, 2026. US Securities and Exchange Commission. Published May 11, 2026. Accessed September 11, 2026. https://www.sec.gov/Archives/edgar/data/0001841925/000119312526215104/indi-20260331.htm
- indie Semiconductor, Inc. Form 10-Q for the quarterly period ended June 30, 2026. US Securities and Exchange Commission. Published August 7, 2026. Accessed September 11, 2026. https://www.sec.gov/Archives/edgar/data/0001841925/000119312526340396/indi-ex32.htm
- indie Semiconductor, Inc. indie Reports Second Quarter 2026 Results. Published August 6, 2026. Accessed September 11, 2026. https://investors.indie.inc/news/news-details/2026/indie-Reports-Second-Quarter-2026-Results/default.aspx
- indie Semiconductor, Inc. indie to Acquire CMOS Image Sensor Product Line from ams OSRAM. Published May 11, 2026. Accessed September 11, 2026. https://investors.indie.inc/news/news-details/2026/indie-to-Acquire-CMOS-Image-Sensor-Product-Line-from-ams-OSRAM/default.aspx
- indie Semiconductor, Inc. indie to Acquire CMOS Image Sensor Product Line from ams OSRAM. Business Wire. Published May 11, 2026. Accessed September 11, 2026. https://www.businesswire.com/news/home/20260511959181/en/indie-to-Acquire-CMOS-Image-Sensor-Product-Line-from-ams-OSRAM
- StockTitan. Indie Semiconductor posts Q2 2026 revenue of $64M. INDI Quarterly Report (10-Q). Published August 7, 2026. Accessed September 11, 2026. https://www.stocktitan.net/sec-filings/INDI/10-q-indie-semiconductor-inc-quarterly-earnings-report-8b651a0e6bda.html
- StockTitan. indie Semiconductor updates Q2 2026 earnings deck. INDI 8-K Filing. Published August 7, 2026. Accessed September 11, 2026. https://www.stocktitan.net/sec-filings/INDI/8-k-a-indie-semiconductor-inc-amends-material-event-report-848dc01d4f33.html
- StockTitan. INDI Stock Price, News and Analysis. Accessed September 11, 2026. https://www.stocktitan.net/overview/INDI/
- Finsee. indie Semiconductor Q2 2026 Earnings Review. Published August 7, 2026. Accessed September 11, 2026. https://finsee.ai/earnings/indi/2026/q2/en/
- The Globe and Mail. Indie Semiconductor Earnings Call Highlights Growth And Risks. Accessed September 11, 2026. https://www.theglobeandmail.com/investing/markets/stocks/INDI-Q/pressreleases/4048924/indie-semiconductor-earnings-call-highlights-growth-and-risks/
- Yahoo Finance. indie Semiconductor, Inc. Q2 2026 Earnings Call Summary. Published August 7, 2026. Accessed September 11, 2026. https://finance.yahoo.com/markets/stocks/articles/indie-semiconductor-inc-q2-2026-123000077.html
- Yahoo Finance. indie Semiconductor, Inc. Q1 2026 Earnings Call Summary. Published May 8, 2026. Accessed September 11, 2026. https://finance.yahoo.com/markets/stocks/articles/indie-semiconductor-inc-q1-2026-123000189.html
- Investing.com. Earnings call transcript: Indie Semiconductor tops revenue view in Q2 2026. Published August 6, 2026. Accessed September 11, 2026. https://www.investing.com/news/transcripts/earnings-call-transcript-indie-semiconductor-tops-revenue-view-in-q2-2026-93CH-4844793
- Investing.com. indie Semiconductor (INDI) Earnings Date and Report. Accessed September 11, 2026. https://www.investing.com/equities/thunder-bridge-acquisition-ii-ltd-earnings
- ChartMill. INDI Forecast, Price Target and Analyst Ratings. Accessed September 11, 2026. https://www.chartmill.com/stock/quote/INDI/analyst-ratings
- StockAnalysis. indie Semiconductor (INDI) Market Cap and Net Worth. Accessed September 11, 2026. https://stockanalysis.com/stocks/indi/market-cap/
- INDmoney. indie Semiconductor (INDI) Live Share Price. Accessed September 11, 2026. https://www.indmoney.com/us-stocks/indie-semiconductor-inc-share-price-indi
- GuruFocus. Indie Semiconductor (INDI) to Divest Stake in Wuxi Unit for $135M. Published October 28, 2025. Accessed September 11, 2026. https://www.gurufocus.com/news/3164630/indie-semiconductor-indi-to-divest-stake-in-wuxi-unit-for-135m