
The 30 second version
- What it does: Mitek Systems sells digital identity verification and check fraud prevention software to more than 7,000 financial institutions worldwide.
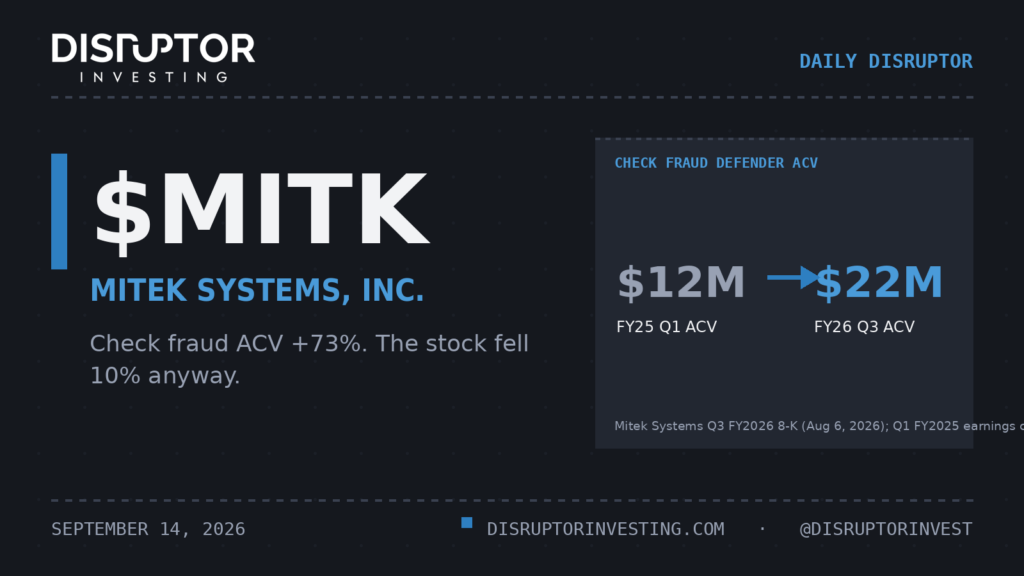
- The number: Check Fraud Defender annual contract value grew 73% year over year to $22M+, and the data consortium now covers 70% of U.S. checking accounts, up from 18% fourteen months ago.
- The catalyst: Q4 fiscal 2026 earnings plus FY2027 guidance, expected in early November 2026. Fiserv went live as a reseller in Q3, extending the network to thousands of institutions it had never reached directly.
- The main risk: The stock has already run 70%+ in twelve months, Q4 is guided soft at $42-47M, and the secular decline in paper checks remains a long term headwind.
- Market cap: Approximately $800 million at the current share price of roughly $18.
Mitek’s stock fell 10% after a quarter in which it beat revenue by 6.4% and EPS by 30%. That is the setup in one sentence. The market looked at management’s Q4 guide of $42-47M, compared it to the $54M quarter that just printed, and sold. What it appears to have missed is that the number fell because of seasonal renewal timing in the check business and a temporary spike in European age verification demand that is not expected to repeat. The underlying network is larger than it was the day of the print.
The reason this matters this week rather than last year is Fiserv. In August 2026, Fiserv went live as a reseller of Check Fraud Defender, extending the consortium’s reach to thousands of institutions that Mitek’s direct sales team, which focuses on the top 100 financial institutions, could never have reached efficiently. The ACV of CFD went from roughly $12 million in early fiscal 2025 to more than $22 million in Q3 fiscal 2026. The network effect is not linear and the Fiserv channel is brand new. The Q4 print will be the first quarter where Fiserv sourced logos could begin showing up in revenue.
What just happened
Mitek reported Q3 fiscal 2026 results on August 6, 2026. Revenue of $54 million came in 6.4% above the consensus estimate of $50.8 million. Non GAAP EPS of $0.34 beat the $0.26 consensus by 31%. Adjusted EBITDA margin expanded to approximately 38%, with operating expenses declining year over year despite the higher revenue, which is exactly the fixed cost leverage the model has been promising for two years. Management raised the full year revenue guidance for the third consecutive quarter to $195-200 million, above the then consensus of roughly $194 million.
The stock fell anyway. Management flagged that Q4 would be soft, guided $42-47M, and noted that the European age verification surge that inflated Q3 fraud and identity numbers was a regulatory timing event unlikely to repeat at the same level. That is a fair warning. But the market appears to have sold the seasonal noise and ignored the structural signal: a top five U.S. bank completed its pilot and joined the full consortium during Q3, and Check Fraud Defender ACV grew 73% to more than $22 million. The consortium data network now covers approximately 70% of U.S. checking accounts. Fourteen months ago it covered 18%.
The business
Mitek sells two things. The first is identity verification, used by financial institutions, fintechs, and digital enterprises to confirm that the person opening an account or authenticating is who they say they are. The second is check fraud prevention, anchored by Check Fraud Defender, a cloud hosted consortium that uses AI and computer vision to analyze check attributes and share fraud intelligence across participating banks in real time. More than 7,000 organizations rely on Mitek globally, and the majority of North American financial institutions use its mobile check deposit technology.
The detail most investors skip: Check Fraud Defender reviews checks against a shared pool of data from across its member institutions, meaning every new member both draws on the network and strengthens it for everyone else. This is a classic network effect business embedded inside a payments infrastructure company. The CFD product analyzes 24 distinct check attributes and can reduce bank agent review times from up to 10 minutes down to 90 seconds, according to Datos Insights. Fiserv’s product page confirms the reseller relationship and describes how the solution layers patented imaging science with handwriting analysis and shared consortium intelligence.
SaaS revenue now makes up 46% of total revenue, up from 43% in fiscal 2025, and management has said publicly that SaaS revenue was expected to approach half of total revenue. It is there. That shift matters because SaaS revenue carries higher margins and greater predictability than the legacy transaction based deposit business.
The numbers
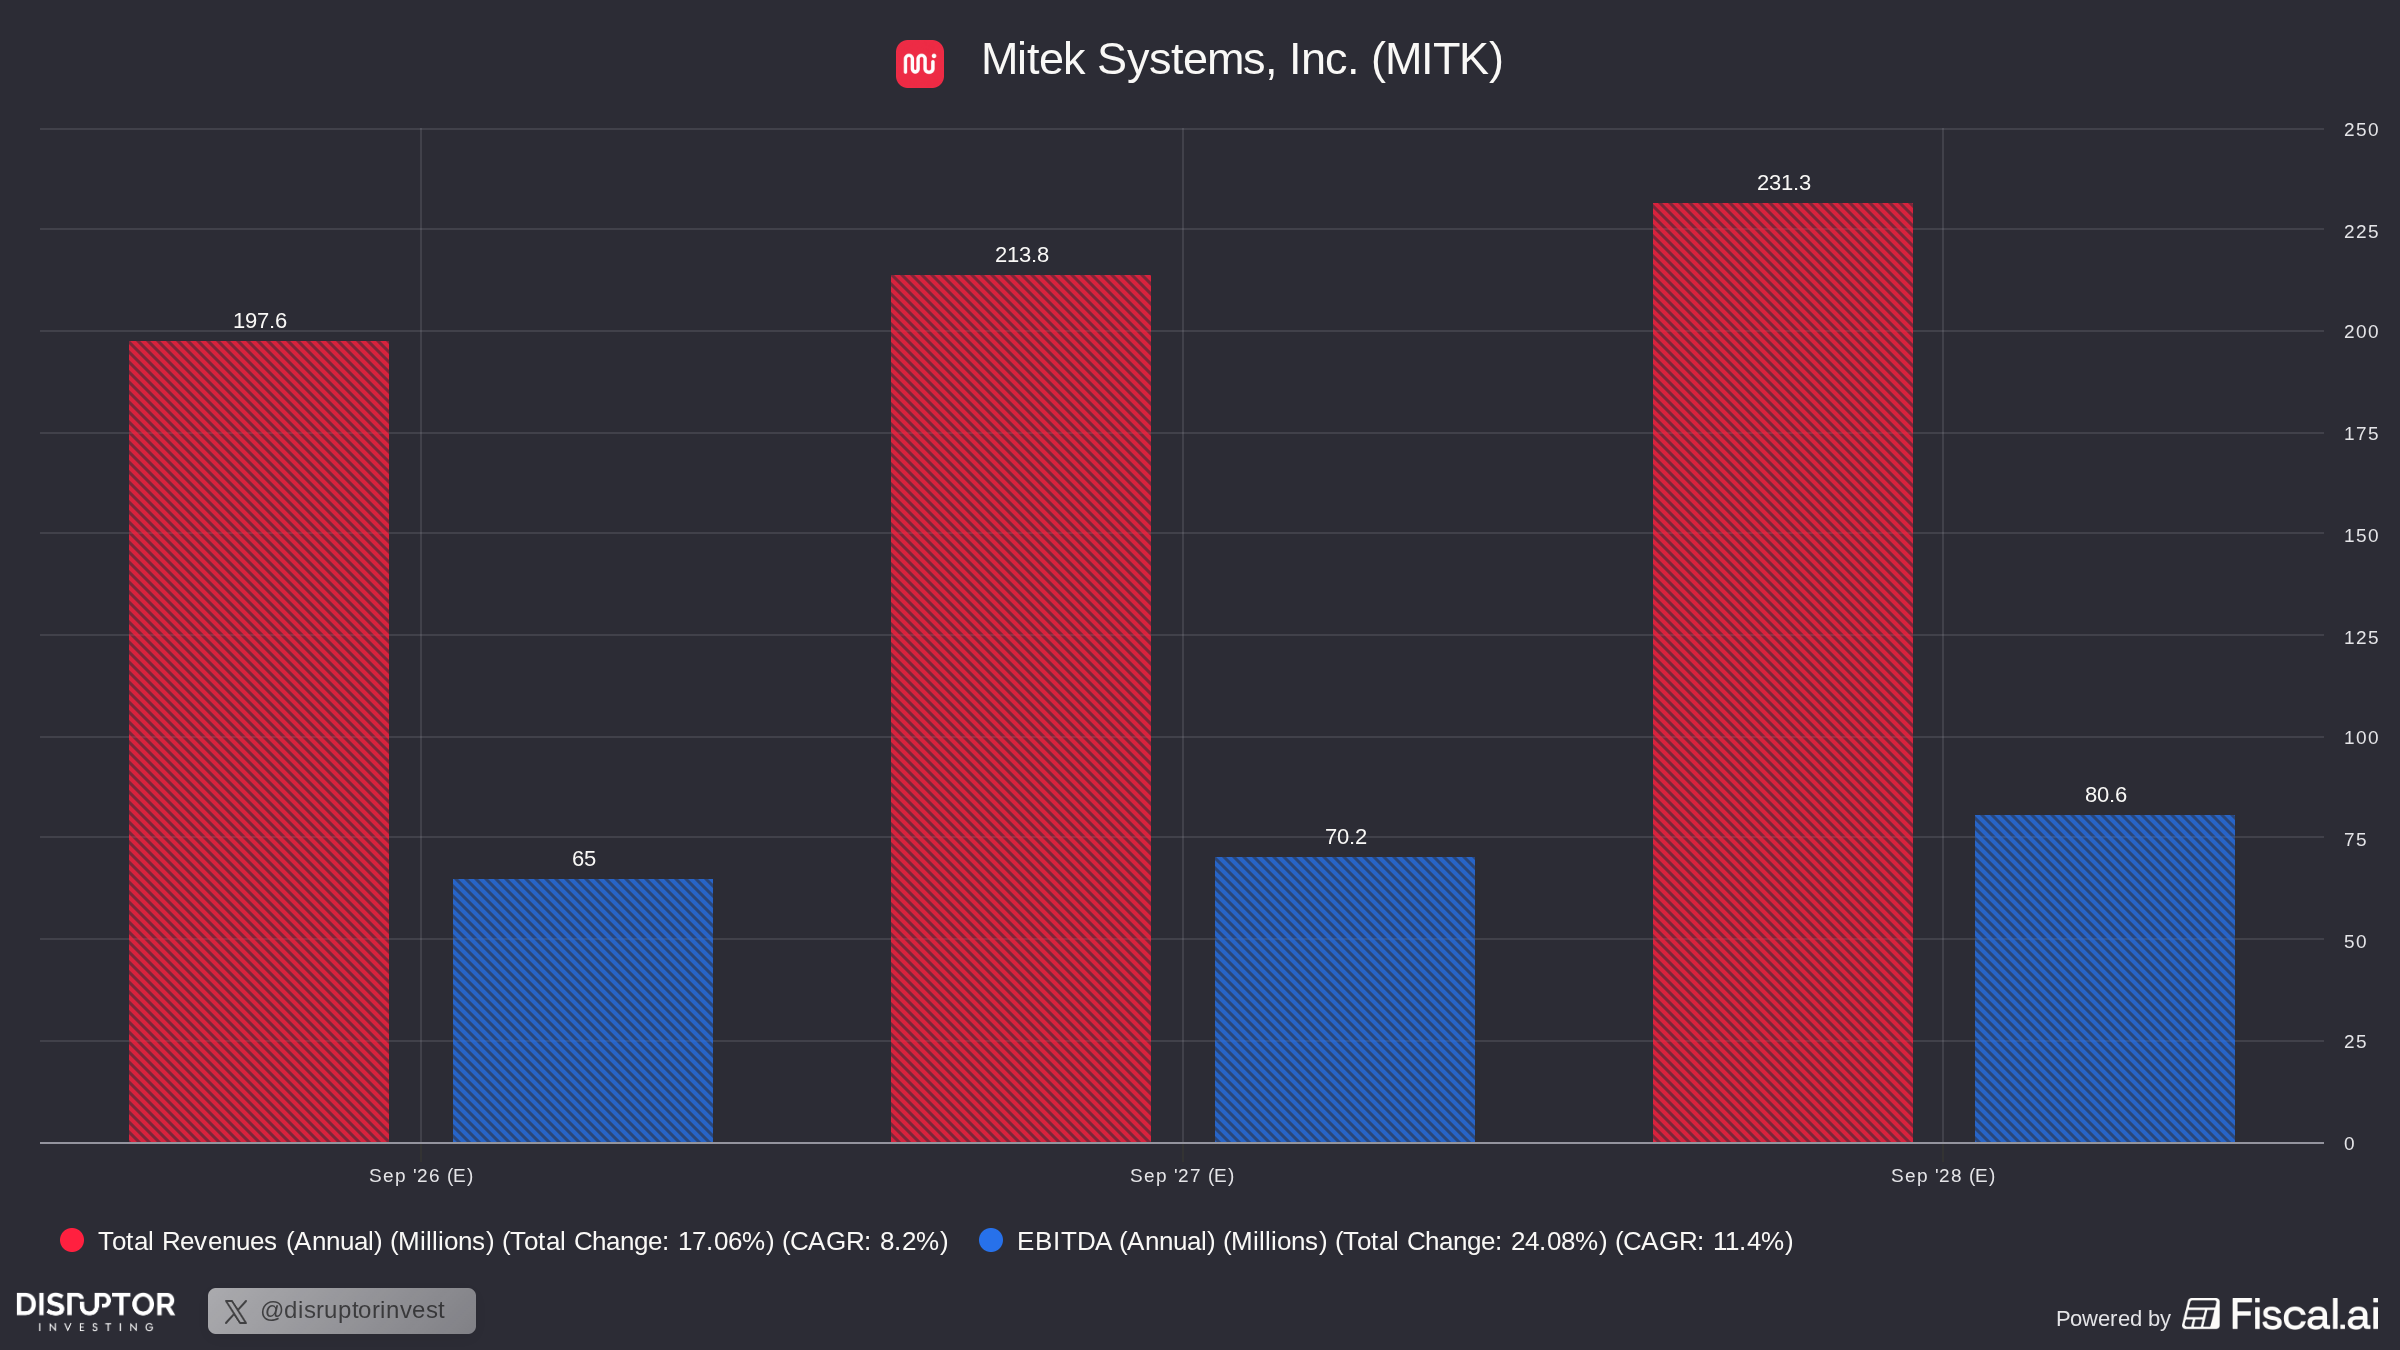
For the first three quarters of fiscal 2026, revenue grew 19%, then 6%, then 18% year over year. The Q2 comparison was tough because of an unusually strong Q2 in fiscal 2025. Strip that out and the trend is consistent acceleration in the fraud and identity segment, which grew 30%, 28%, and 14% in Q1, Q2, and Q3 respectively. SaaS revenue within that segment grew 21%, 18%, and 37%. Fraud and identity now represents just over half of total revenue. Full year management guidance sits at $195-200 million, with the midpoint above the analyst consensus of roughly $194 million. Adjusted EBITDA margin is guided at 32-34% for the full year, versus 21% one year ago.
The balance sheet is clean. Mitek ended Q3 fiscal 2026 with approximately $46 million in net cash, having retired its $155 million convertible notes earlier this fiscal year. Free cash flow for Q3 alone was $25.3 million. The company has repurchased approximately $21 million of stock over the trailing twelve months and has $29 million remaining on its current buyback authorization. There is no dilution concern and no need to raise capital. Gross margin in Q3 was in the low 80s on a non GAAP basis. The one structural watch: check verification revenue faces a long term secular decline in check volumes, though management notes it has held in the $90 million range for two years. The CFD overlay is converting what would otherwise be a melting asset into a growing network.
Why the market has not caught up
The stock dropped 10% on Q3 earnings and has traded sideways since. Eleven analysts cover it, with targets ranging from around $17 to $26. Institutional ownership sits at roughly 84%, meaning the incremental buyer is not a large fund discovering a new name. Short interest is at 7.36% of shares outstanding, elevated enough to create some mechanical pressure if the Q4 print surprises. The consensus is pricing the Q4 guide at face value, and the estimates for fiscal 2027 have not yet reflected what a Fiserv reseller channel, now live, could add to Check Fraud Defender ACV. Management addressed this directly on the Q3 call: the Fiserv relationship extends the network to thousands of institutions, each of which is already integrated with Fiserv’s infrastructure and can join the consortium without a separate sales or onboarding process.
The gap between what the filings show and what the price implies is this: the market is focused on a soft Q4 and a check secular headwind. The filings show that CFD ACV grew from $12 million to $22 million in under five quarters, that the consortium now covers 70% of U.S. checking accounts, that EBITDA margins hit 38% in Q3, and that Fiserv just became a distribution arm for a product that was previously sold only through Mitek’s direct team. The FY2027 guide, which lands on the Q4 earnings call in early November, is what the market is not yet pricing.
What breaks it
The thesis breaks in two ways. First, if the Fiserv reseller channel produces slower adoption than management’s direct sales history suggests, CFD ACV growth could decelerate below 50%, removing the main re rating argument. Second, the stock has already moved a long way. The forward PE is around 16x, which is not cheap for a company where one business line is structurally declining. If Q4 revenue prints at the low end of the $42-47M guide and management guides FY2027 conservatively, the stock could give back more of the run. The secular decline in paper checks is real, not manageable in perpetuity, and the check verification business at roughly $90 million in annual revenue is eventually a headwind to the blended growth rate. Investors should also note that three analysts have revised estimates upward recently, meaning some of the consensus beats are already anticipated.
What we are watching
- Early November 2026: Q4 fiscal 2026 earnings print and, more importantly, the FY2027 revenue and margin guide. This is the moment where the Fiserv distribution channel shows up in backlog language, if it is working.
- October November 2026: Check Fraud Defender ACV disclosure in the Q4 call. If it exceeds $25 million, the market will have to reprice the trajectory. If it stalls below $22 million, the thesis is at risk.
- Ongoing: Positive Pay Plus, the adjacent product that added its first non bank design partner in Q3, is worth watching as a signal that CFD is moving beyond check fraud into broader payment assurance. A commercial contract here would be a separate catalyst.
Not financial advice.
References
- Mitek Systems, Inc. Form 8-K (Q3 Fiscal 2026 Earnings Release). US Securities and Exchange Commission. Published August 6, 2026. Accessed September 14, 2026. https://www.sec.gov/Archives/edgar/data/0000807863/000080786326000035/mitk-20260630xexx991xq326e.htm
- Mitek Systems, Inc. Form 10-Q for the quarterly period ended June 30, 2026. US Securities and Exchange Commission. Published August 6, 2026. Accessed September 14, 2026. https://www.sec.gov/Archives/edgar/data/0000807863/000080786326000036/mitk-20260630.htm
- Mitek Systems, Inc. Form 10-Q for the quarterly period ended March 31, 2026. US Securities and Exchange Commission. Published May 7, 2026. Accessed September 14, 2026. https://www.sec.gov/Archives/edgar/data/0000807863/000080786326000026/mitk-20260331.htm
- Mitek Systems, Inc. Form 8-K (Q1 Fiscal 2026 Earnings Release). US Securities and Exchange Commission. Published February 5, 2026. Accessed September 14, 2026. https://www.sec.gov/Archives/edgar/data/807863/000162828026003469/mitk-20260126.htm
- Investing.com. Earnings call transcript: Mitek beats Q3 2026 estimates, shares jump after hours. Published August 7, 2026. Accessed September 14, 2026. https://www.investing.com/news/transcripts/earnings-call-transcript-mitek-beats-q3-2026-estimates-shares-jump-after-hours-93CH-4844619
- GuruFocus. Mitek Systems Inc (MITK) Q3 2026 Earnings Call Highlights: Record SaaS Revenue and Check Fraud Defender Momentum Drive 18% Growth. Published August 7, 2026. Accessed September 14, 2026. https://www.gurufocus.com/news/9015226/mitek-systems-inc-mitk-q3-2026-earnings-call-highlights-record-saas-revenue-and-check-fraud-defender-momentum-drive-18-growth
- MarketBeat. Mitek Systems Q3 Earnings Call Highlights. Published August 7, 2026. Accessed September 14, 2026. https://finance.yahoo.com/markets/stocks/articles/mitek-systems-q3-earnings-call-040352239.html
- Fiserv. Check Fraud Defender. Accessed September 14, 2026. https://www.fiserv.com/en/solutions/deposit-solutions/check-risk-mitigation/check-fraud-defender.html
- Mitek Systems. Check Fraud Defender product page. Accessed September 14, 2026. https://www.miteksystems.com/products/check-fraud-defender
- StockAnalysis. Mitek Systems (MITK) Statistics and Valuation. Accessed September 14, 2026. https://stockanalysis.com/stocks/mitk/statistics/
- ChartMill. MITK Stock Profile. Accessed September 14, 2026. https://www.chartmill.com/stock/quote/MITK/profile
- Fintel. MITK Institutional Ownership. Accessed September 14, 2026. https://fintel.io/so/us/mitk
- Zacks. Compared to Estimates, Mitek Systems (MITK) Q3 Earnings: A Look at Key Metrics. Published August 7, 2026. Accessed September 14, 2026. https://finance.yahoo.com/markets/stocks/articles/compared-estimates-mitek-systems-mitk-230004862.html
- MarketBeat. Mitek Systems Q1 2025 Earnings Call Transcript. Accessed September 14, 2026. https://www.marketbeat.com/earnings/reports/2025-2-10-mitek-systems-inc-stock