
The 30 second version
- What it does: SOPHiA GENETICS runs a cloud based AI platform that lets hospitals and labs run standardized genomic analyses. Revenue is usage based, SaaS like, and sticks hard: net dollar retention is 117% and annual churn is under 1%.
- The number: Q2 2026 revenue of $23.3 million, up 27% year over year, beat the analyst consensus by 7.4%. Management immediately raised full year guidance to $94M-$96M, implying 22-24% growth.
- The catalyst: Q3 2026 earnings, expected around November 10, 2026, will be the first print where investors can measure H2 revenue acceleration and early AstraZeneca CDx milestones.
- The risk: The stock has nearly tripled from its 52-week low. The company raised $57.5 million in a dilutive equity offering just three months ago. Both things are true.
- Market cap: Approximately $650M-$700M. Daily dollar volume is adequate for small accounts. Liquidity thins above a few hundred thousand dollars per day.
A genomics software company that nobody covers properly just had AstraZeneca knock on its door. On August 4, SOPHiA GENETICS announced a multi year global collaboration with AstraZeneca to build two companion diagnostics from its existing platform. One covers solid tumors. The other targets blood cancer. Both will be decentralized, meaning any local lab in the 75 countries where SOPH already operates can run the test on day one of a drug approval, without routing samples to a central facility. That is the structural advantage that made AstraZeneca choose them, and the market mostly shrugged.
Why it matters now, rather than six months from now: the deal landed on the same day as a Q2 beat, a guidance raise, and the clearest language yet from management about the path to breakeven. The stock has moved, but the consensus earnings model barely has. The AstraZeneca revenue lands primarily in 2027, and most analysts appear to be waiting to pencil it in until the milestones are clearer. That lag between a confirmed pharma partnership and consensus catching up is exactly the kind of gap worth watching.
What just happened
On August 4, 2026, SOPHiA GENETICS announced a new global collaboration with AstraZeneca to develop, validate, and deploy two companion diagnostics supporting precision oncology therapies. The multi year agreement advances two separate companion diagnostic programs, bringing SOPHiA’s decentralized clinical trial assays and CDx capabilities to AstraZeneca therapies. One program converts SOPHiA’s Solid Tumor application into a decentralized companion diagnostic. The other develops and validates its Hematological Oncology application to support a program for patients with blood cancer.
Deployment runs through the SOPHiA DDM Platform and the MaxCare Program, enabling laboratories to bring testing in house and adopt new genomic applications across the company’s global network. That cloud based, technology agnostic platform lets healthcare institutions run the same validated, AI powered analysis locally, while sharing in the collective intelligence of more than 1,000 connected institutions across 75 countries. The decentralized approach is intended to make companion diagnostics available in local laboratories on the first day of a drug approval. That is not a small operational detail. Most CDx programs are centralized, which creates bottlenecks at launch. SOPH’s architecture removes the bottleneck. AstraZeneca, with one of the largest oncology pipelines in the world, clearly valued that.
The business
SOPHiA GENETICS operates as a cloud native software technology company in the healthcare space. It offers the SOPHiA DDM platform, a cloud native software platform for analyzing data and generating insights from multimodal datasets and diagnostic modalities. The platform and its related solutions are used by hospitals, laboratories, and biopharmaceutical companies through the company’s own sales force and distributor network across Europe, North America, Latin America, and Asia Pacific.
The revenue model is usage based. Labs pay per analysis run, which means revenue scales directly with patient volume and test breadth, not with how many accounts sales closes. Net dollar retention sits at 117%, with more than 537 core genomic customers versus 490 a year ago, annualized revenue churn under 1%, and a cumulative database of 2.5 million genomic profiles since inception. The detail that stands out in the filings: the company recorded a single month patient analysis record of more than 40,000 in March 2026. Monthly records are easy to dismiss, but a record in Q1, which management itself flagged as their seasonally weakest quarter, tells you something about the underlying rate of adoption.
SOPHiA’s companion diagnostic capabilities span the drug development and launch continuum, from clinical trial assay development, to identify and screen the right patients during a trial, through companion diagnostic development, validation, and regulatory submission in the US, EU, Japan, and beyond. That end to end CDx capability is rare among companies this size, and it is precisely what makes a pharma scale collaboration possible.
The numbers
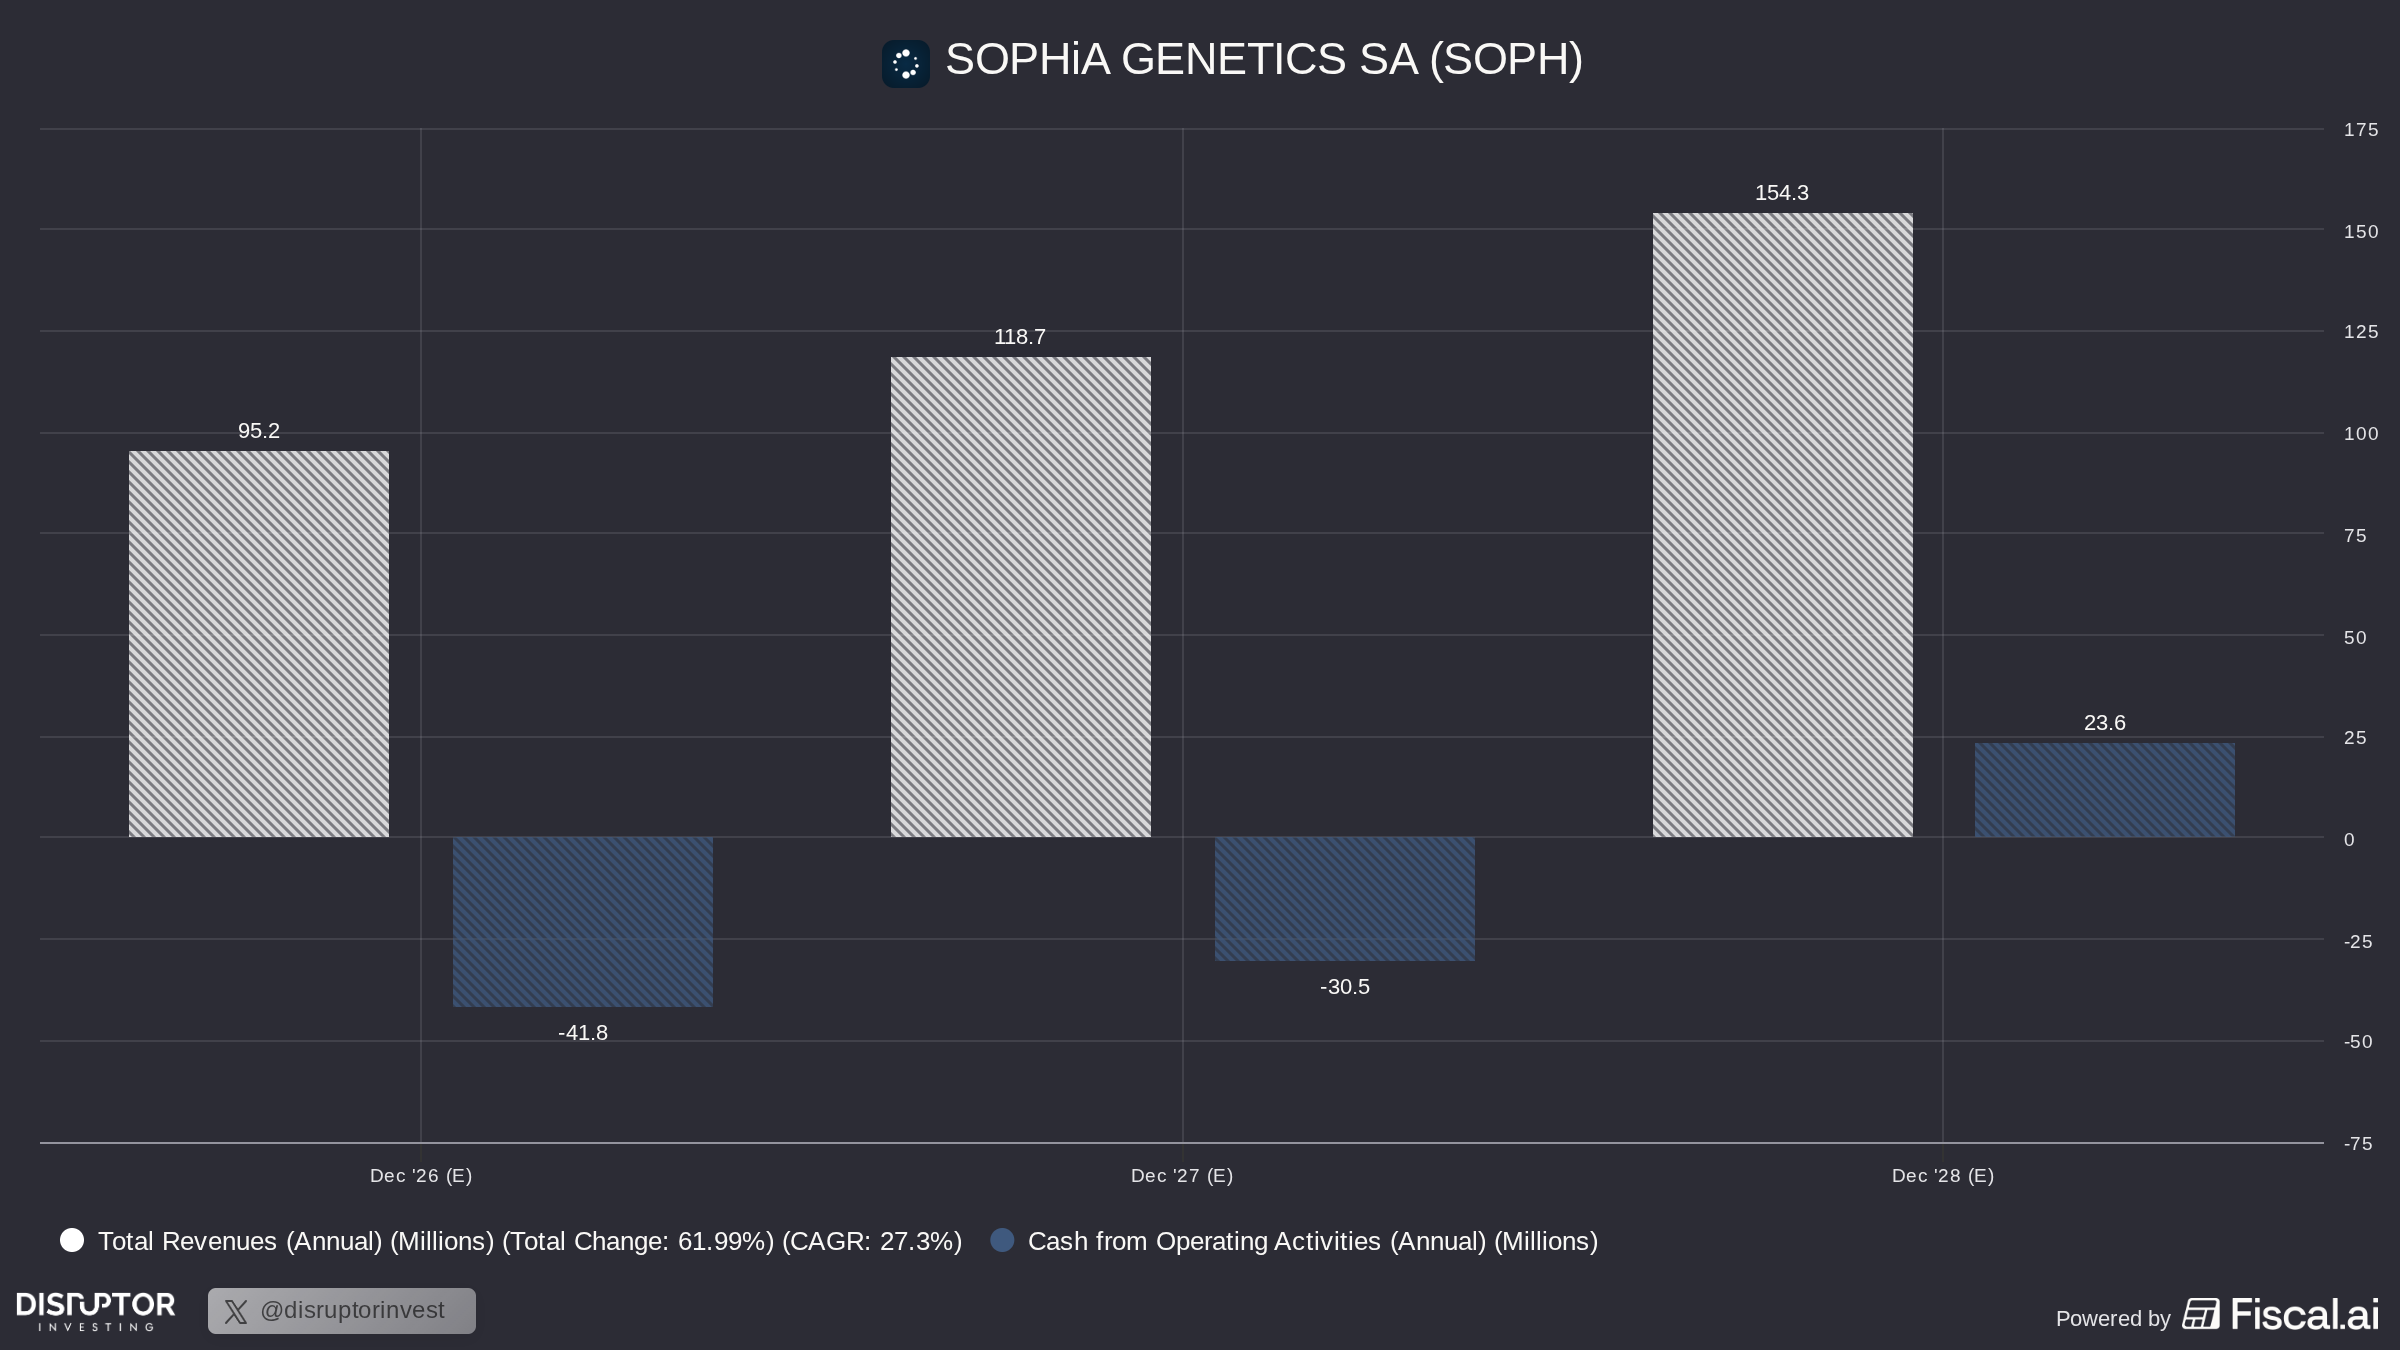
Q2 2026 revenue came in at $23.3 million, up 27% from the same quarter a year earlier, exceeding analyst estimates by 7.4%. Following that result, management raised full year 2026 revenue guidance from $92M-$94M to $94M-$96M, representing 22% to 24% year over year growth. Adjusted gross margin held at 75.4% in Q1 2026, with adjusted gross profit of $16.4 million, up 22% year over year. Management expects modest gross margin expansion for the full year.
On adjusted EBITDA, the company reaffirmed its full year loss guidance of $29 million to $32 million, compared to a loss of $41.5 million in 2025. Management stated they remain on track to approach adjusted EBITDA breakeven by the end of 2026 and expect to cross fully into positive adjusted EBITDA in the second half of 2027. The EBITDA inflection is the line that matters most in the next three quarters. Q1 cash burn was $19.5 million with cash on hand of $65.4 million. The June 2026 equity raise added roughly $57.5 million in gross proceeds, so the company enters H2 with a reasonable runway into the breakeven window without a near term forced raise. Management was explicit that the CDx deals announced with AstraZeneca will impact revenue growth primarily in 2027, as the programs reflect multi year agreements with tiered milestones.
On the estimate picture: HC Wainwright models Q3 2026 EPS at negative $0.12 and Q4 2026 at negative $0.05, with the company approaching breakeven inside this fiscal year. BTIG raised its price target following what it described as a strong Q2 beat and higher guidance. Analyst price targets currently cluster in a $9 to $12 range. Coverage remains thin. The name is followed by fewer than ten analysts, which is appropriate given the size, and the gap between the low and high targets is wide enough to suggest the market has not formed a firm view on what the AstraZeneca relationship is worth.
Why the market has not caught up
Short interest is 0.25% of shares outstanding, effectively nothing. This is not a short squeeze story. Institutional ownership data for a sub-$700M Swiss listed Nasdaq name is sparse, and that sparseness is itself the signal. Many US equity funds have size minimums that knock SOPH out of automatic consideration. Most genomics focused funds already own Illumina or Veracyte. SOPH sits in no obvious category, and that classification problem keeps the coverage thin and the price inefficiency intact.
The gap that interests us is this: the AstraZeneca announcement has been in the market for five weeks. Analysts have moved fair value estimates to around $9.75 from $9.00, a modest reset. But the AstraZeneca CDx programs, structured as multi year agreements with tiered milestones tied to regulatory submissions and commercial launches, represent recurring, high margin revenue that the consensus model does not yet carry. The broader companion diagnostics market for targeted therapies is forecast to reach $11.25 billion by 2030, expanding at a 14.4% compound annual rate. SOPH does not need the whole market. It needs the pharma CDx partnership model to work twice. It has now signed at least once, with the largest oncology drug developer in the world.
What breaks it
The dilution history is real and should not be waved away. SOPHiA GENETICS raised $57.5 million in gross proceeds via an underwritten public offering of 12.1 million shares at $4.75 per share in June 2026, with underwriters fully exercising their option. The stock now trades at roughly double the offering price, which means the raise looks well timed in retrospect, but the share count grew materially in one transaction. The company has an active F-3 shelf, and another raise is not out of the question if the EBITDA path slips. The company remains heavily dependent on equity issuance for funding, which carries ongoing dilution risk. That is the single most credible risk to the thesis. If the H2 revenue ramp toward the top of guidance disappoints, the EBITDA breakeven timeline slips, and the stock re rates down hard from these levels.
Foreign exchange is a secondary but genuine headwind. The company reports in USD but operates primarily in Europe and earns a significant share of revenue in euros and Swiss francs. Currency moves can distort the reported growth rate in either direction, and a dollar strengthening cycle would pressure the numbers on a reported basis even if volume is fine.
What we are watching
- November 10, 2026 (estimated): Q3 2026 earnings. This is the first print that will show whether the seasonal H2 ramp is materializing and whether guidance for Q4 implies the adjusted EBITDA loss is narrowing toward management’s target. Any language on AstraZeneca CDx milestone timing will move the stock.
- Q4 2026 (ongoing): Watch clinical ASP trajectory. Management guided for average selling price to climb as higher value pharma tests mix in. If clinical ASP moves from the Q1 level of roughly $195 toward the upper end of the $100-$500 range, margins follow.
- H1 2027: AstraZeneca CDx program regulatory submissions. Any formal filing in the US or EU marks the first hard milestone in the deal, converting a partnership announcement into a datable regulatory event.
Not financial advice.
References
- SOPHiA GENETICS. SOPHiA GENETICS Enters Collaboration to Develop Companion Diagnostics for Precision Oncology Therapies. Published August 4, 2026. Accessed September 8, 2026. https://www.sophiagenetics.com/news/sophia-genetics-enters-collaboration-to-develop-companion-diagnostics-for-precision-oncology-therapies/
- SOPHiA GENETICS. SOPHiA GENETICS Reports First Quarter 2026 Results. Published May 5, 2026. Accessed September 8, 2026. https://www.prnewswire.com/news-releases/sophia-genetics-reports-first-quarter-2026-results-302761826.html
- Motley Fool Transcribing. SOPHiA GENETICS (SOPH) Q2 2026 Earnings Call Transcript. The Motley Fool. Published August 11, 2026. Accessed September 8, 2026. https://www.fool.com/earnings/call-transcripts/2026/08/11/sophia-genetics-soph-q2-2026-earnings-call-transcript/
- TipRanks. SOPHiA GENETICS (SOPH) Earnings Dates, Call Summary & Reports. Accessed September 8, 2026. https://www.tipranks.com/stocks/soph/earnings
- Simply Wall St. SOPHiA GENETICS (NasdaqGS:SOPH) Earnings & Revenue Performance. Accessed September 8, 2026. https://simplywall.st/stocks/us/healthcare/nasdaq-soph/sophia-genetics/past
- StockTitan. SOPHiA GENETICS prices $50M share offering at $4.75. Published June 17, 2026. Accessed September 8, 2026. https://www.stocktitan.net/news/SOPH/sop-hi-a-genetics-announces-pricing-of-50-million-public-offering-of-zlce83ofsm7s.html
- StockTitan. SOPHiA GENETICS sells 12.1M shares after offering draws strong demand. Published June 19, 2026. Accessed September 8, 2026. https://www.stocktitan.net/news/SOPH/sop-hi-a-genetics-announces-closing-of-57-5-million-public-offering-0bbafu0jjj4p.html
- StockAnalysis. SOPHiA GENETICS (SOPH) Statistics & Valuation. Accessed September 8, 2026. https://stockanalysis.com/stocks/soph/statistics/
- Yahoo Finance. SOPHiA GENETICS SA (SOPH) Stock Price, News, Quote & History. Accessed September 8, 2026. https://finance.yahoo.com/quote/SOPH/
- Simply Wall St / Yahoo Finance. SOPHiA GENETICS (SOPH) Stock Sees Modest Fair Value Lift After Q2 Guidance Raise. Published September 4, 2026. Accessed September 8, 2026. https://finance.yahoo.com/markets/stocks/articles/sophia-genetics-soph-stock-sees-130832539.html
- The Cerbat Gem. Brokers Issue Forecasts for SOPHiA GENETICS Q2 Earnings. Published July 22, 2026. Accessed September 8, 2026. https://www.thecerbatgem.com/2026/07/22/brokers-issue-forecasts-for-sophia-genetics-q2-earnings.html
- StockEvents. SOPHiA Genetics SA (SOPH) Stock Price, Quote, News & Events. Accessed September 8, 2026. https://stockevents.app/en/stock/SOPH
- GlobeNewsWire. Companion Diagnostics for Targeted Therapies Market Outlook 2026-2030. Published September 3, 2026. Accessed September 8, 2026. https://www.globenewswire.com/news-release/2026/09/03/3356041/28124/en/companion-diagnostics-for-targeted-therapies-market-outlook-2026-2030-investment-trends-strategic-profiles-and-revenue-share-outlook.html
- Investing.com. Sophia Genetics earnings missed by $0.06, revenue topped estimates. Accessed September 8, 2026. https://in.investing.com/news/earnings/sophia-genetics-earnings-missed-by-006-revenue-topped-estimates-5268912