
The 30 second version
- Perpetua Resources develops the Stibnite Gold Project in Idaho, the only identified domestic antimony reserve in the United States, targeting 450,000 oz of gold and up to 35% of U.S. antimony demand annually in early production years.
- The U.S. Export Import Bank unanimously approved a $2.9 billion senior secured loan in May 2026; management expects to close the facility and make a final investment decision in H2 2026, meaning this quarter or next.
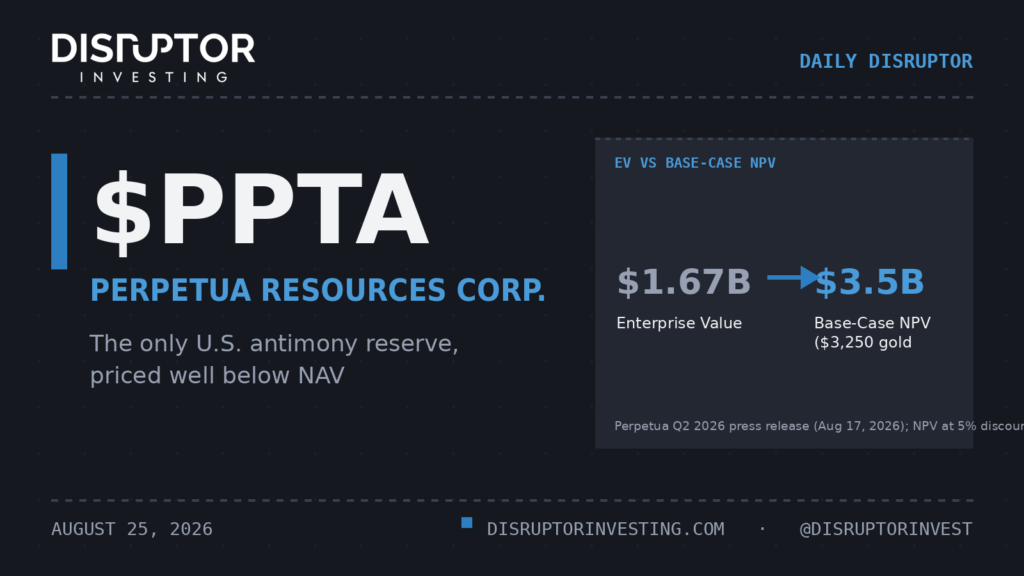
- The base case project NPV is $3.5 billion at $3,250 per ounce gold. Spot gold is trading near $4,365. The enterprise value sits at roughly $1.67 billion.
- Catalyst: EXIM loan closing and final construction decision, targeted H2 2026. Next earnings: November 12, 2026.
- Main risk: 58% share count growth over the past year, accelerating burn, and a pending environmental appeal that could complicate construction timing.
- Market cap approximately $3.1 billion, 7 analysts covering, Strong Buy consensus, average target $36.90.
The United States has not mined a single tonne of antimony since 2001. The country has mined no antimony since the closure of the Sunshine Mine in Idaho in 2001. That gap did not matter much until China announced export controls in August 2024 and then cut off shipments to the U.S. entirely. China’s outright ban on shipments to the United States sent prices to an all time record of approximately $59,750 per tonne by mid-2025. The number that made us look twice this morning is not the antimony price. It is the NPV.
Perpetua’s base case project economics use $3,250 per ounce gold. That number produces a post tax NPV of $3.5 billion. Gold spot was recently trading near $4,364.90 per ounce. At $4,500 gold, the company’s own updated economics push that NPV to $6.1 billion. The updated project economics show a base case after tax NPV of $3.5 billion at $3,250 per ounce gold, increasing to $6.1 billion at $4,500 per ounce. The enterprise value of the company right now is roughly $1.67 billion. That is the setup.
What just happened
The two events that changed Perpetua’s trajectory happened within eight days in May. On May 21, 2026, the board of the Export Import Bank unanimously approved a $2.9 billion senior secured long term loan under the Make More in America Initiative to support the Stibnite Gold Project. That is the largest loan in EXIM’s Make More in America program and the agency’s fourth largest on record. On May 29, the U.S. District Court of Idaho denied a motion for a preliminary injunction filed by special interest groups challenging the project’s approvals.
The CEO noted that the unanimous EXIM approval, combined with the company’s $574.2 million cash position at quarter end, positions the project well as it advances toward a final investment and construction decision in H2 2026, with the company continuing to work through definitive documentation and anticipating closing the facility later this year. Q2 results, filed August 17, confirmed the company is already on critical path construction activities: Burntlog Route upgrades under way, worker housing proceeding, and long lead procurement running. The FID, when it lands, converts this from a development company to a construction company. That is the inflection.
The business
Perpetua Resources Corp. is a Boise, Idaho headquartered mineral development company focused on the 100%-owned Stibnite Gold Project in central Idaho, aiming to redevelop and restore the historic Stibnite Yellow Pine mining district while producing gold alongside antimony, a designated U.S. critical mineral used in defense, energy, and manufacturing applications. At full capacity, the project is expected to be among the highest grade open pit gold mines in the country, averaging 450,000 ounces of annual production over its initial four years.
The antimony side is where the strategic moat lives. Stibnite is the only source of domestic antimony that can meet U.S. requirements for weapons production, with the ability to supply about 35% of U.S. demand within the first six years of production. Antimony is a critical input for the defense industry, particularly for armor piercing ammunition, night vision goggles, infrared sensors, bullets, and precision optics. One detail buried in the filings: Perpetua has received more than $80 million in federal support since 2022, including up to $22.4 million in Defense Ordnance Technology Consortium awards and $59.2 million through the Defense Production Act Title III program. The federal government has already bet on this project across multiple agencies before the EXIM loan even closes.
The numbers
Q2 2026 net loss was $97.5 million, versus a $6.0 million loss in the prior year quarter, mainly from higher exploration and pre development spending ahead of the planned final investment and construction decision. That is not a deterioration to worry about in isolation: it is spending money to be construction ready. The company ended the quarter with $574.2 million in unrestricted cash and $60.9 million in restricted cash. At roughly $73 million per quarter in net spending, that represents more than seven quarters of runway before the EXIM loan has funded a single dollar.
After quarter end, the company paid $28.9 million for gold put options covering up to 158,016 ounces in 2031 at a $3,000-per ounce strike price, designed to retain upside above the strike while limiting downside exposure. That is disciplined treasury management from a pre revenue company. On estimates: seven analysts polled by S&P Global rate PPTA a Strong Buy with an average price target of $36.90. The lowest target is $30 and the highest is $43.50, representing 19% to 72% upside from recent prices. The flag here is dilution: shares outstanding have increased 58.74% over the past year. That growth has funded the capital program but it compresses per share NAV and deserves weight.
Why the market has not caught up
Coverage is thin and the project has no revenue. Seven analysts is not a small number for a development stage miner, but the name does not appear in most screens because it generates zero operating income. Short interest stands at 9.26% of outstanding shares. That is meaningful but not extreme, and the short thesis is likely centered on EXIM documentation risk and construction timeline slippage rather than the underlying project quality. Institutional ownership sits at roughly 70%, which means the float is not loose. The market is not ignoring this company. It is discounting the catalysts.
The discount is specific: the enterprise value of roughly $1.67 billion compares to a base case NPV of $3.5 billion modeled at $3,250 gold, and spot gold is now roughly $1,100 per ounce above that assumption. The market appears to be pricing in a meaningful probability that the FID slips, the EXIM loan does not close on schedule, or the environmental appeal reopens permitting risk. Any one of those scenarios would delay the value realization. But the cash runway covers them. And the $2.9 billion EXIM approval, which is unanimous and board level, is not a letter of interest. The documentation work is the remaining friction, and management says it closes this year.
What breaks it
There are two things that kill this trade. First, the EXIM loan documentation process: investors should be aware that funding under the EXIM loan is subject to completion of definitive documentation, and there is no assurance that definitive loan documents can be successfully negotiated to close the loan. A slip into 2027 is not the same as a project failure, but it would push the FID out and likely reprice the stock. Second, the environmental appeal: the Idaho district court rejected the preliminary injunction, finding plaintiffs failed to show irreparable harm, but plaintiffs subsequently filed an appeal with the U.S. Court of Appeals. If an appellate court grants an injunction, construction stops. That is low probability given the district court’s ruling, but it is real. The dilution trajectory is worth watching too. Shares are up nearly 59% in a year. Another large raise would further dilute the per share NAV argument even if the project itself is sound.
What we are watching
- EXIM loan closing announcement, expected Q3 or Q4 2026: this is the single most important binary event for the stock.
- Final investment and construction decision, also H2 2026: management has held to this timeline through Q2; any delay in the Q3 update (around November 12 earnings) would be the tell.
- U.S. Court of Appeals ruling on the environmental injunction appeal: no timeline has been given, but any ruling before FID could move the stock sharply in either direction.
Not financial advice.
References
- Perpetua Resources Corp. News Release: Second Quarter 2026 Financial Results. Published August 17, 2026. Accessed August 25, 2026. https://perpetuaresources.com/perpetua-resources-announces-second-quarter-2026-financial-results/
- Perpetua Resources Corp. Q2 2026 News Release (PDF). Published August 17, 2026. Accessed August 25, 2026. https://perpetuaresources.com/wp-content/uploads/2026/08/Perpetua-Resources-Q2-2026-PR.pdf
- Perpetua Resources Corp. Antimony page. Accessed August 25, 2026. https://perpetuaresources.com/antimony/
- Perpetua Resources Corp. Investor news and press releases. Accessed August 25, 2026. https://www.investors.perpetuaresources.com/investors/news/
- Faulkner B. Perpetua Resources Q2 2026 Earnings: Net Loss Widens to $97.5 Million as Stibnite Development Spending Accelerates. Sci Tech Today. Published August 2026. Accessed August 25, 2026. https://www.sci-tech-today.com/news/perpetua-resources-q2-2026-earnings/
- Perpetua Resources Q2 Net Loss Widens to $97.5M. StockTitan. Published August 17, 2026. Accessed August 25, 2026. https://www.stocktitan.net/news/PPTA/perpetua-resources-announces-second-quarter-2026-financial-4p7xe90iig2u.html
- Mufson S. Miner Perpetua Resources secures $2.9 billion U.S. loan for Idaho gold, antimony project. CNBC. Published May 21, 2026. Accessed August 25, 2026. https://www.cnbc.com/2026/05/21/miner-perpetua-resources-secures-2point9-billion-us-loan-for-idaho-gold-antimony-project.html
- Idaho Gold Antimony Developer Wins $2.9B EXIM Loan Approval. Streetwise Reports. Published August 20, 2026. Accessed August 25, 2026. https://www.streetwisereports.com/article/2026/08/20/idaho-gold-antimony-developer-wins-2-9b-exim-loan-approval.html
- Perpetua Resources (PPTA) Stock Forecast and Analyst Price Targets. Stock Analysis. Accessed August 25, 2026. https://stockanalysis.com/stocks/ppta/forecast/
- Perpetua Resources (PPTA) Statistics and Valuation. Stock Analysis. Accessed August 25, 2026. https://stockanalysis.com/stocks/ppta/statistics/
- Critical Minerals: Global Antimony Supply and Demand. Geopolitical Monitor. Published March 26, 2026. Accessed August 25, 2026. https://www.geopoliticalmonitor.com/critical-minerals-global-antimony-supply-demand/
- Lewis J. China’s Antimony Export Restrictions: The Impact on U.S. National Security. Center for Strategic and International Studies. Accessed August 25, 2026. https://www.csis.org/analysis/chinas-antimony-export-restrictions-impact-us-national-security
- Perpetua Resources moves to bolster United States antimony production. Mugglehead Investment Magazine. Published December 10, 2025. Accessed August 25, 2026. https://mugglehead.com/perpetua-resources-moves-to-bolster-united-states-antimony-production/
- US Military Supply Chain Secures Domestic Antimony Breakthrough. Streetwise Reports. Published December 12, 2025. Accessed August 25, 2026. https://www.streetwisereports.com/article/2025/12/12/u-s-military-supply-chain-secures-domestic-antimony-breakthrough.html
- B. Riley Financial Begins Coverage on Perpetua Resources (NASDAQ:PPTA). MarketBeat. Published August 3, 2026. Accessed August 25, 2026. https://www.marketbeat.com/instant-alerts/b-riley-financial-begins-coverage-on-perpetua-resources-nasdaqppta-2026-08-03/