
The 30 second version
- Clearfield designs and manufactures fiber connectivity hardware for broadband networks and, as of last week, hyperscale data centers.
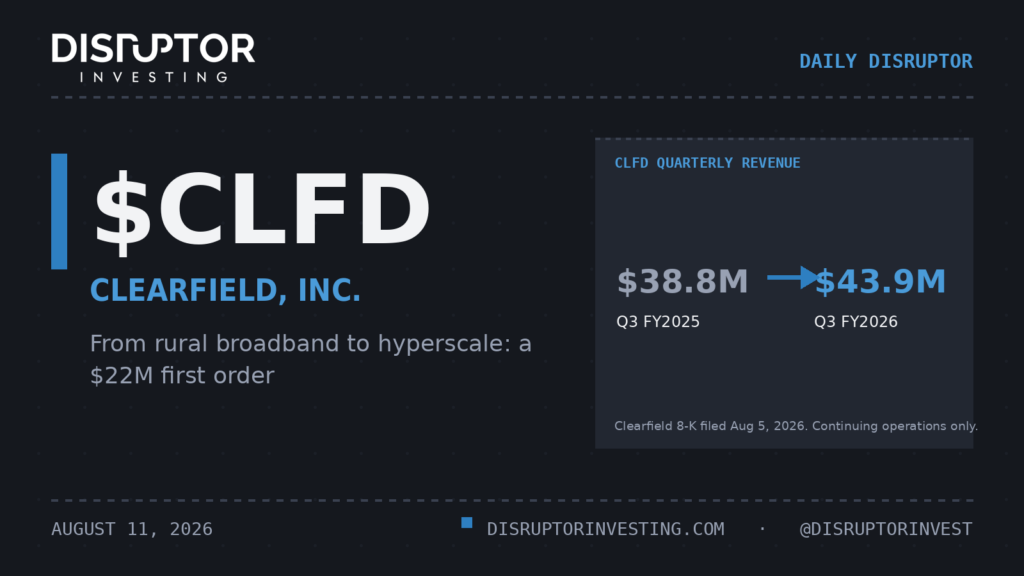
- Revenue grew 13% year over year and 28% sequentially in Q3 FY2026, to $43.9 million, while the company ended the quarter with $155 million in cash and no debt.
- Days after quarter close, management announced a $22 million hyperscale data center order, the first in Clearfield’s history, with shipments starting in early FY2027 (October 2026).
- Catalyst: data center shipments commence October 2026; Q4 FY2026 earnings expected early November 2026.
- Main risk: broadband end market remains soft, BEAD funding delays continue to push out revenue, and Q4 guidance is well below prior consensus.
- Market cap approximately $450 million; short interest at roughly 12% of float.
Clearfield just landed a $22 million order from a hyperscale data center customer. That is not a line item. For a company that did $150 million in total revenue last fiscal year, it is close to a semester’s worth of a new market. The market has not moved to reflect it.
The timing matters. Broadband deployment in the United States has been stuck in slow motion all year, pinned down by BEAD program delays, constrained domestic fiber supply, and cautious spending from community broadband operators. Clearfield’s stock has shed roughly 30% from its 52-week high as those headwinds compounded. The guide down is fresh, the short sellers are comfortable, and almost nobody is writing about the data center pivot. That is the setup.
What just happened
On August 5, Clearfield reported Q3 FY2026 results and simultaneously disclosed that it had received its first significant hyperscale data center order, valued at approximately $22 million, with shipments expected to begin in early fiscal 2027. The quarter itself beat EPS estimates by three cents, $0.22 versus $0.19, on revenue of $43.9 million, slightly in line with consensus. Management then guided Q4 revenue of $38 to $42 million, well below the prior Street estimate of $52 million, citing ongoing BEAD delays and a backlog reduction from a community broadband customer cancellation.
The surface read is ugly. The deeper read is that the same earnings call introduced two things the broadband story could not: a named hyperscale customer, a co designed product, and a shipment date inside one quarter. Management said the new NOVA platform panel developed for this customer will be standardized and introduced to the broader data center market later this calendar year. That is not vague. It is a product launch on a timeline.
The business
Clearfield designs, manufactures, and sells fiber optic management and delivery hardware: the enclosures, cassettes, patch panels, and distribution hubs that sit between the fiber cable and the equipment it connects. The company has built this business largely serving community broadband operators, municipal co ops, MSOs, and national carriers trying to close the digital divide. Its core value proposition is labor savings: the FieldSmart platform and now the NOVA platform are engineered for tool less installation and high density, meaning a crew can turn up fiber ports faster than with competing solutions.
What most investors have missed is the NOVA platform, launched in January 2026, which was explicitly designed for hyperscale and colocation data centers alongside broadband central offices. The 4U NOVA panel supports up to 384 LC fiber ports. For context, as AI driven workloads push fiber counts per rack higher, that density matters. The detail buried in the Q3 shareholder letter is that the $22 million data center order was won through a collaborative design process with the end customer, and the resulting panel will now be standardized for the broader market. This is how fiber infrastructure vendors enter hyperscale: one design win at a time, then replication.
The numbers
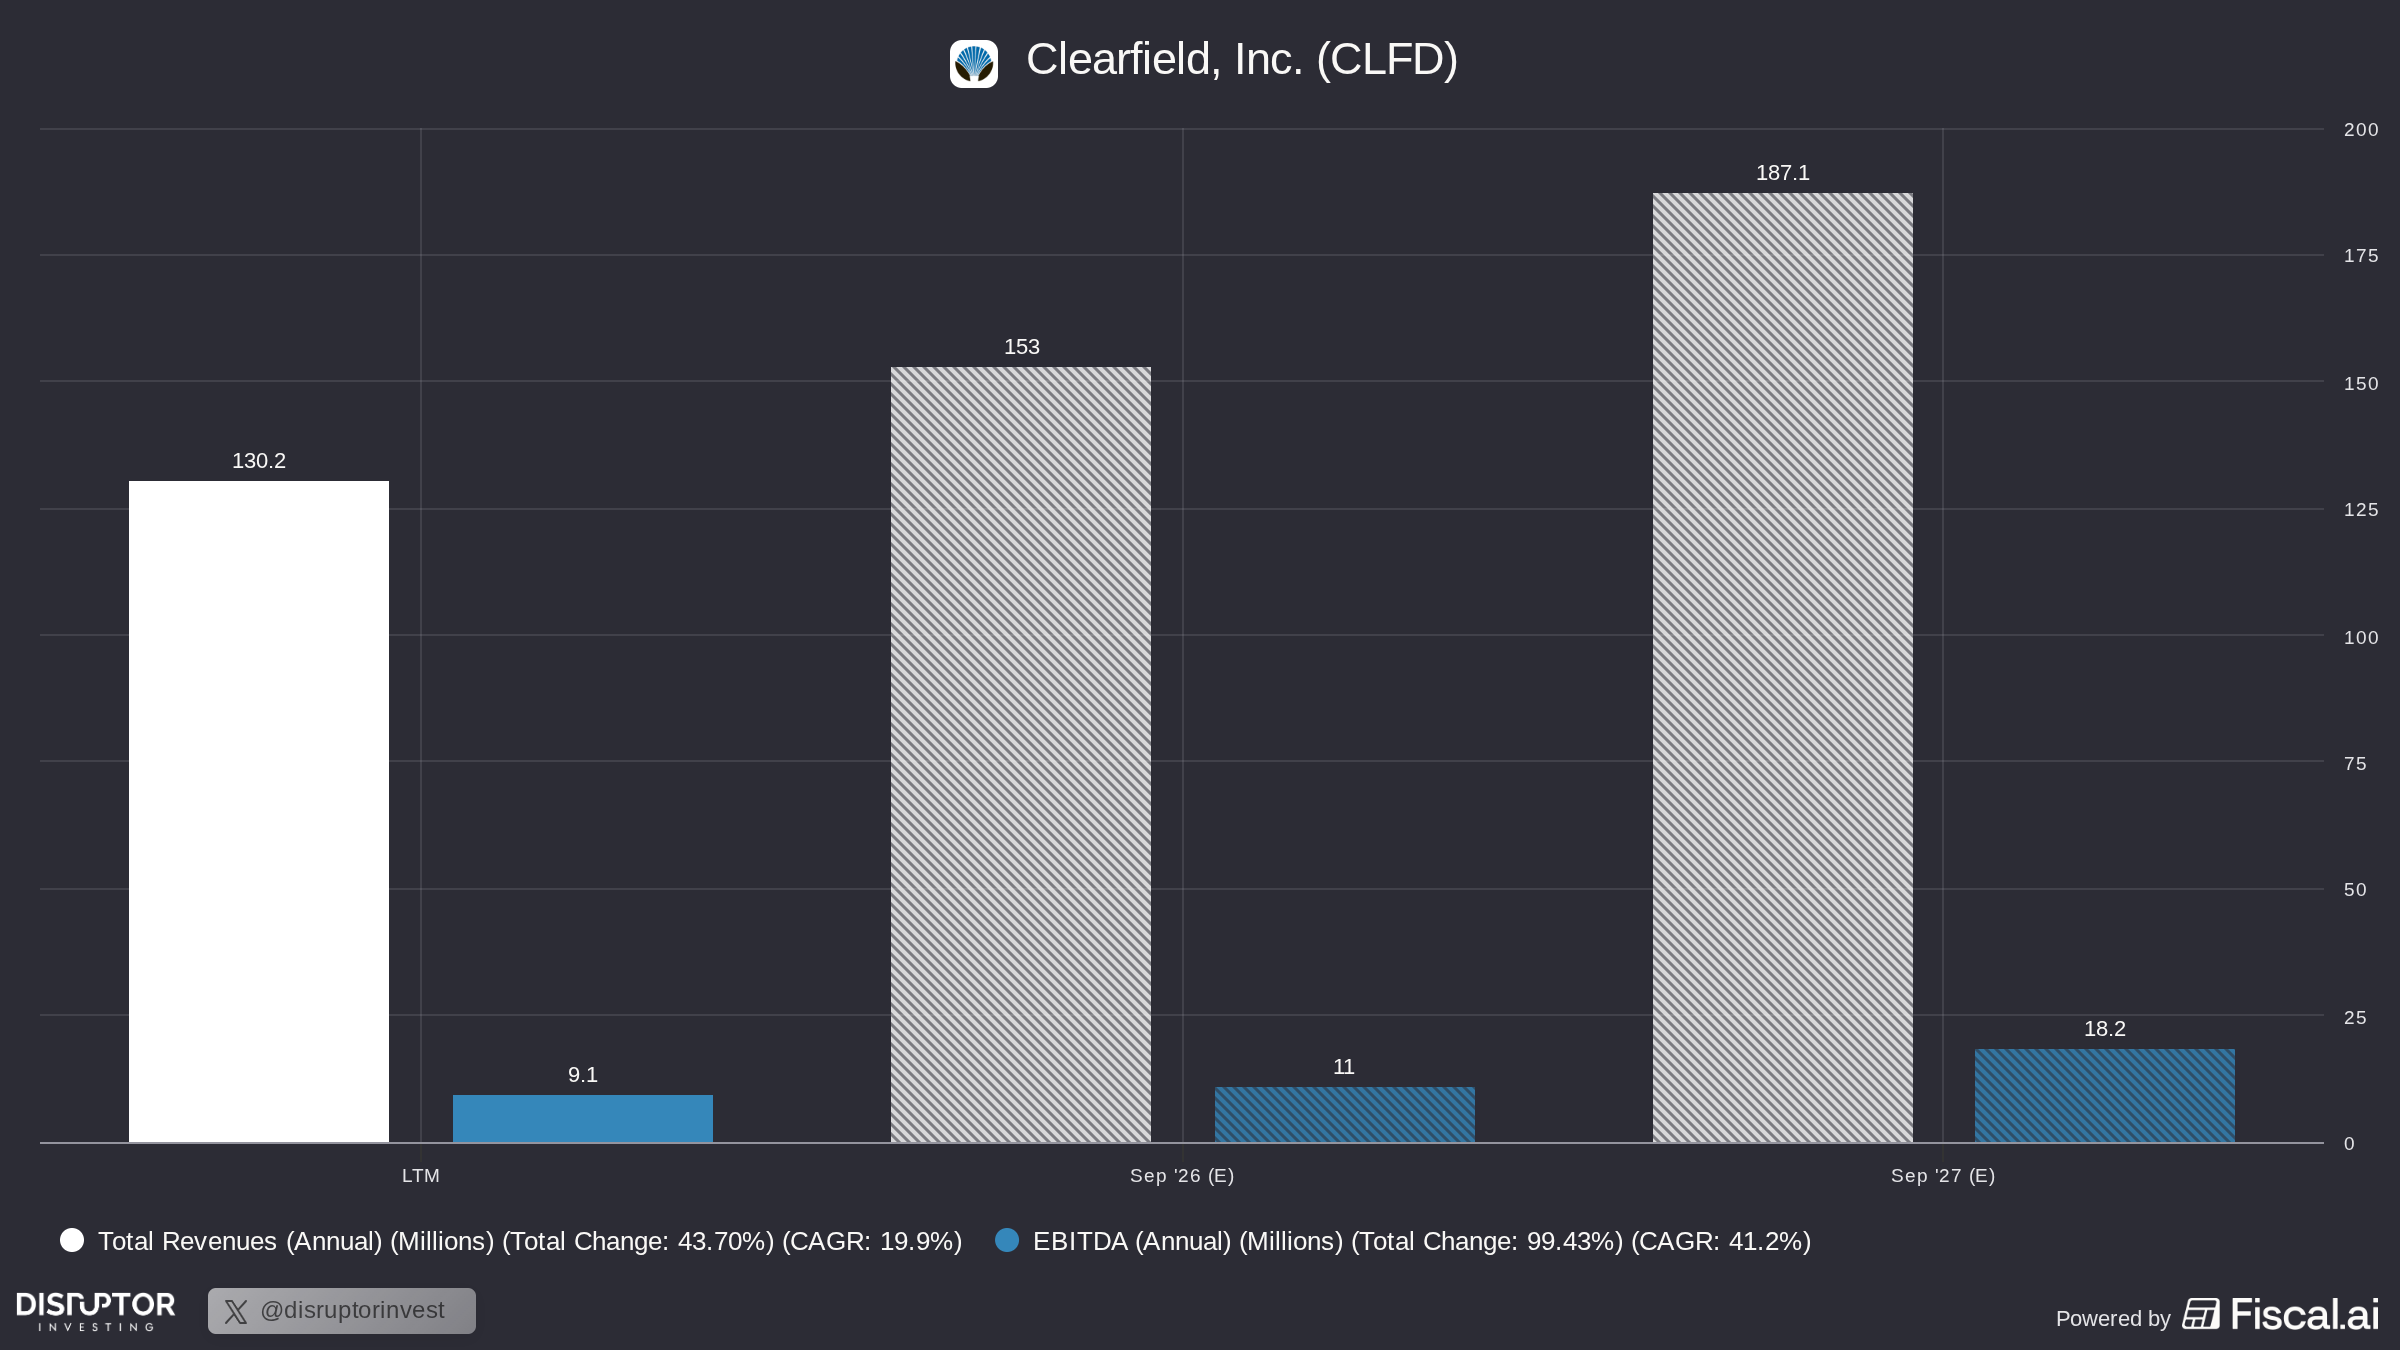
Revenue for Q3 FY2026 was $43.9 million, up 13% year over year and 28% sequentially from Q2’s $34.2 million. Gross margin came in at 31.8%, down from 35.3% in the prior year quarter, partly due to one time items management said reduced margin by roughly 1.8 percentage points. Operating expenses fell 6% year over year and 14% sequentially, so the margin compression is being partially offset by cost discipline. The company holds approximately $155 million in cash and investments with no debt, and the share count has actually declined year over year as the company repurchases stock.
For Q4 FY2026, management guided revenue of $38 to $42 million against a prior consensus of $52 million, and EPS of $0.00 to $0.07 against a consensus of $0.41. That gap is enormous and the stock has already absorbed most of the news. The more interesting number is the forward quarter. The $22 million data center order ships in early FY2027, which starts in October 2026, and it lands on a balance sheet with $155 million in cash and no dilution risk. There is no Q1 FY2027 consensus yet for analysts to anchor to, which means the market is still arguing over a quarter that is almost over rather than the one that includes the new revenue.
Why the market has not caught up
Short interest sits at roughly 12% of the float, up from low single digits two years ago when Clearfield was a broadband darling. Institutional ownership is high at about 89%, but that population has been trimming, with outflows outpacing inflows last quarter. The stock is largely owned by small and mid cap value managers who bought the broadband recovery thesis and are now staring at a guidance cut. The data center pivot is not yet large enough to move the price targets of analysts who still model it as a fiber hardware supplier to ISPs and co ops.
The gap is simple. The market is pricing a company still dependent on BEAD program timing and rural broadband spending. The filings show a company that just co designed a proprietary data center panel with a hyperscale customer, has $155 million in cash to invest in production capacity, and is sitting on a product line that Dell’Oro Group says addresses a market set to grow at double digits through the end of the decade. When the Q1 FY2027 numbers land in November or December with $22 million of that data center order booked, the model changes in one print.
What breaks it
The broadband end market could stay soft longer than expected. BEAD program delays have already been running longer than anyone predicted, and a second consecutive fiscal year of depressed community broadband spending would compress margins further. The guide down to $38 to $42 million for Q4 tells you management sees no near term relief from that channel. If the data center order slips by even one quarter, the thesis goes quiet until Q2 FY2027. There is also the gross margin question: at 31.8%, Clearfield is operating well below the 40%-plus levels it posted during the 2022 to 2023 broadband boom, and a shift toward data center hardware does not automatically restore that margin until volumes justify better fixed cost absorption. The stock has beta above 2.0. It will move harder than the market, in both directions.
What we are watching
- October 2026: First shipments from the $22 million hyperscale data center order begin, per management guidance. Any shipping confirmation or delay is the first observable data point on the pivot.
- Late October to early November 2026: Q4 FY2026 earnings print. Key items are whether the new NOVA data center panel has been introduced to additional customers and whether Q1 FY2027 guidance reflects data center revenue ramp.
- November 2026 (calendar year): Management committed to introducing the co developed NOVA data center panel to the broader market before year end. A product launch announcement would be an independent catalyst.
Not financial advice.
References
- Clearfield, Inc. Form 8-K for the period ended June 30, 2026. US Securities and Exchange Commission. Published August 5, 2026. Accessed August 11, 2026. https://www.sec.gov/Archives/edgar/data/0000796505/000117184326005241/exh_991.htm
- Clearfield, Inc. Q3 Fiscal 2026 Earnings Call Highlights. Yahoo Finance. Published August 5, 2026. Accessed August 11, 2026. https://finance.yahoo.com/markets/stocks/articles/clearfield-q3-earnings-call-highlights-000408184.html
- Clearfield, Inc. Q3 2026 Earnings Call Highlights: Strategic Data Center Win Offsets Headwinds. Yahoo Finance. Published August 6, 2026. Accessed August 11, 2026. https://finance.yahoo.com/markets/stocks/articles/clearfield-inc-clfd-q3-2026-050444796.html
- Clearfield, Inc. Clearfield Reports Third Quarter Fiscal 2026. StockTitan. Published August 5, 2026. Accessed August 11, 2026. https://www.stocktitan.net/news/CLFD/clearfield-reports-third-quarter-fiscal-2026-rz3p211r84n1.html
- Clearfield, Inc. Clearfield Introduces NOVA Platform, Optimizing Scalability and Installation Simplicity for High Density Fiber Connectivity. Fiber Broadband Association. Published January 15, 2026. Accessed August 11, 2026. https://fiberbroadband.org/2026/01/15/clearfield-introduces-nova-platform-optimizing-scalability-and-installation-simplicity-for-high-density-fiber-connectivity/
- Clearfield Launches NOVA Platform for High Density Fiber Connectivity in Data Centers and Broadband Networks. Cabling Installation and Maintenance. Published January 30, 2026. Accessed August 11, 2026. https://www.cablinginstall.com/connectivity/press-release/55354209/clearfield-launches-nova-platform-for-high-density-fiber-connectivity-in-data-centers-and-broadband-networks
- Clearfield (NASDAQ:CLFD) Updates Q4 2026 Earnings Guidance. Daily Political. Published August 6, 2026. Accessed August 11, 2026. https://www.dailypolitical.com/2026/08/06/clearfield-nasdaqclfd-updates-q4-2026-earnings-guidance.html
- Clearfield (CLFD) Statistics and Valuation. Stock Analysis. Accessed August 11, 2026. https://stockanalysis.com/stocks/clfd/statistics/
- Clearfield (CLFD) Institutional Ownership. MarketBeat. Accessed August 11, 2026. https://marketbeat.com/stocks/NASDAQ/CLFD/institutional-ownership