
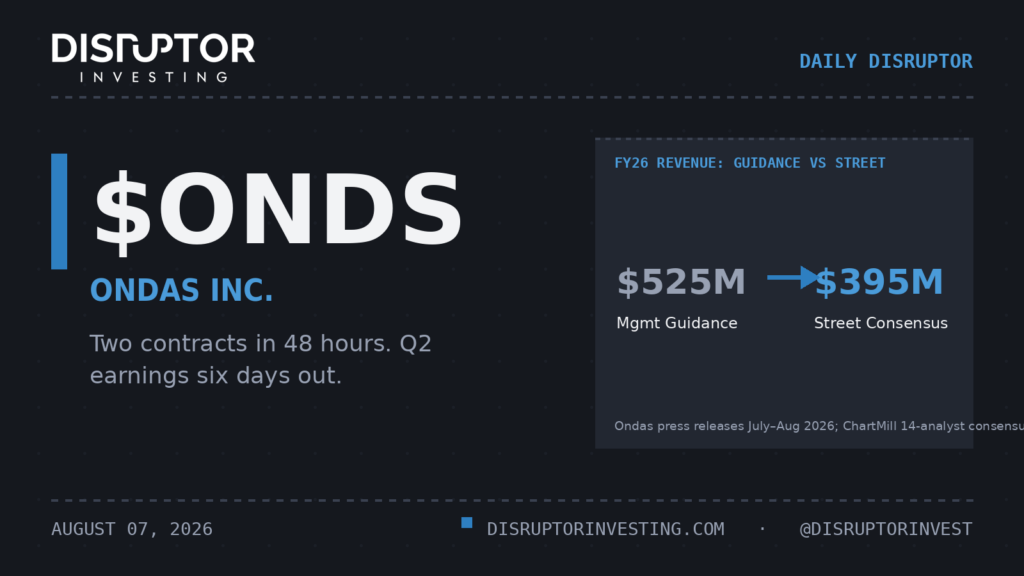
Yesterday morning the Air Force Research Laboratory handed Ondas a contract worth more than $6 million to advance an autonomous precision delivery drone called the Long Range Grasshopper. The morning before that, the U.S. Army added a second order to an existing Mistral program, pushing that contract vehicle’s total awards past $240 million. Two contracts in 48 hours, neither of which moved the stock much. That quiet tells you something about where the market’s attention is sitting right now.
Six days from today, on August 13, Ondas reports Q2 results before the open. Management has guided the full year to at least $525 million, a figure that sits roughly $130 million above the current Street consensus of $395 million. That gap is not a rounding error. It reflects a company that has changed shape faster than analysts have remodeled their spreadsheets, and it is the arithmetic reason this print matters.
The 30 second version
- Ondas builds autonomous defense systems: counter drone kits, loitering munitions, ISR platforms, and private wireless networks for rail and utilities
- Q1 2026 revenue of $50.1M, up more than ten fold from $4.3M a year earlier; Q2 orders alone exceeded $150M
- Catalyst: Q2 2026 earnings, August 13, 2026 pre market, confirmed
- Main risk: serial acquisition integration, with DZYNE ($875.8M deal) closed July 2 and Cyberhawk pending; plus 21 insider sales against zero purchases in six months
- Market cap approximately $4.97B; ~570M shares outstanding; average daily volume around 86M shares
What just happened
On August 5, Ondas announced that its subsidiary Mistral received an additional order of more than $50 million from the U.S. Army under a previously awarded $982 million Lethal Unmanned Systems IDIQ. Mistral is already building systems under the initial $190.8 million award, with deliveries starting Q3 2026. The new order extends that production runway on the same vehicle. The following day, August 6, the Air Force Research Laboratory awarded DZYNE Technologies, now part of Ondas, a contract of more than $6 million to develop the Long Range Grasshopper, an autonomous runway independent delivery system for logistics in contested environments.
Both awards flow through Ondas Sentinel, the dedicated U.S. defense division created after Ondas closed its acquisition of DZYNE Technologies on July 2. Ondas Sentinel now houses ISR, counter UAS, precision strike, autonomous logistics, and AI enabled mission orchestration under one roof. The pace of contract announcements since that closing is not casual: the company has booked roughly $70 million in new orders in the four weeks ending July 22, and Q2-to date bookings across autonomous defense exceeded $150 million before the quarter closed.
The business
Ondas operates through two segments. Ondas Networks supplies private wireless broadband via its FullMAX software defined radio platform, serving rail operators, utilities, and public safety agencies. Ondas Autonomous Systems, built through a string of acquisitions completed mostly in 2026, covers commercial and defense drone solutions. The defense side now includes Mistral for loitering munitions, World View for high altitude ISR, DZYNE for autonomous logistics and counter UAS, and Sentrycs for cyber over RF counter drone technology. Sentrycs’ system is being integrated into Lockheed Martin’s Sanctum counter UAS platform, a reference that matters when competing for large government tenders.
One detail buried in the Q1 10-Q: product level companies within Ondas Autonomous Systems reached adjusted EBITDA profitability in Q1, six months ahead of internal targets. That is a meaningful signal about unit economics at the subsidiary level, even as the consolidated group still burns cash on integration and overhead.
The numbers
Q1 2026 revenue was $50.1 million, up from $4.3 million in Q1 2025, a more than 1,000 percent year over year increase driven almost entirely by acquisitions. Gross margin came in at 49%, up from 35% a year ago, as the product mix shifted toward software heavy defense platforms. Adjusted EBITDA loss was $10.9 million for the quarter. Cash and equivalents stood at $1.48 billion as of March 31, following a roughly $1 billion equity raise completed in January 2026. That balance sheet gives the company room to absorb integration costs and close pending deals without an immediate dilutive raise, though the January offering itself was substantial.
Pro forma backlog at the end of Q1 stood at $457 million, up 570% from $68.3 million at year end 2025. Management subsequently raised full year 2026 revenue guidance twice: first to $390 million in May, then to at least $525 million in July, incorporating DZYNE and Omnisys but not the pending Cyberhawk acquisition. The Street has not kept up. ChartMill shows a 14-analyst consensus at $69.33 million for Q2 alone, with a full year consensus near $395 million. The gap between guidance and consensus is the trade. Consensus EPS for Q2 is negative $0.09.
Why the market has not caught up
Short interest stood at 43.9% of the float as of July 15, per data cited at ts2.tech, a level that Ondas’ own coverage calls extraordinary even relative to peers like Red Cat. The stock is down roughly 30% year to date despite what is, on paper, a dramatic acceleration in orders and revenue. That combination of heavy short positioning, a lagging analyst consensus, and a stock sitting 43% below the median analyst target of $20.53 per ChartMill describes something specific: the market does not believe the guidance. Earnings six days from now will either confirm or deny that skepticism in one session. On July 30, BlackRock filed a Schedule 13G disclosing a 7.2% passive stake covering 38.1 million shares, a new filing that arrives precisely as the short side is most exposed.
Fourteen analysts cover ONDS with an 86% buy consensus and a median target of $20.53, but the revenue model for most of them predates the DZYNE close and the second guidance raise. When a company’s management guidance sits $130 million above the Street on a full year basis and an earnings catalyst is days away, the revision cycle that follows is usually sharp in one direction or the other. The filings show $1.48 billion in cash, a clean product level EBITDA story, and a backlog that was 570% larger at March 31 than it was three months prior. The price, at roughly $8.72, implies the street thinks the $525 million number is a fiction.
What breaks it
The single biggest risk is integration velocity. Ondas has acquired Mistral, World View, DZYNE, Rotron Aerospace, Bird Aero, and others in roughly twelve months. DZYNE alone cost $875.8 million. The Q2 report will include Mistral and World View but not DZYNE, which closed July 2 after the quarter ended. That means the reported Q2 revenue will land well below the updated guidance run rate, and management will have to carry the argument on backlog and order commentary rather than recognized revenue. Any sign of slipping integrations, revenue recognition timing, or difficulty converting the $457 million backlog will hand the short side fresh ammunition. Separately, insiders have sold 21 times in six months with zero purchases. That is not disqualifying by itself, but it sits in the room alongside a stock that has lost 30% this year.
What we are watching
- August 13, 2026: Q2 earnings pre market, 8:30 AM ET. The key figures are recognized revenue, backlog conversion rate, and any updated FY26 guidance that incorporates DZYNE and Cyberhawk closing timelines
- Q3 2026 (September): First quarter in which DZYNE consolidates fully into reported revenue, giving the first clean look at whether the $525M guidance is achievable
- Q3 2026: Cyberhawk acquisition close, targeted for Q3 per company statements, which would add a third revenue stream not yet in the model
Not financial advice.
The setup
ONDS is trading at 8.74, below both its 50 day and 200 day moving averages, with the 50 day itself sitting below the 200 day. That is a downtrend by standard definition. The stock is 37.6% off its 52 week high and sits at roughly the midpoint of its annual range. The 14 day RSI has reached 70, which is elevated and somewhat unusual for a stock that is still below both averages, and reflects the recent one month surge of 14.2%. Volume over the past 10 days has been running at 0.79 times its 50 day average, so that recent price recovery has not been accompanied by above average participation. Against the broader market, ONDS has lost 6.8 points of relative strength over the past three months, and the three month absolute return of negative 1.7% underscores that the longer trend has not turned. The daily average true range of 8.6% of price means this is a high volatility name where positions move fast in both directions.
The historical base rate on this ticker covers 15 prior days when ONDS sat in a comparable technical position. That is a very small sample and should carry little weight on its own. In those instances, the stock was higher one month later only 7% of the time, with a median one month move of negative 16.9%. The quarterly picture looked different, with the stock higher 73% of the time and a median gain of 121.1%, though outcomes ranged from negative 16.9% to positive 175.2%. The wide spread in those quarterly results reflects the volatility of the name rather than anything reliable. The near term base rate is bluntly negative, and the RSI reading combined with a still broken trend structure is not a flattering setup for anyone thinking about the next few weeks specifically.
References
- Ondas Inc. Press Release: Ondas Secures U.S. Army Order for Lethal Unmanned Systems for Over $50 Million. Published August 5, 2026. Accessed August 7, 2026. https://ir.ondas.com/press-releases/detail/321/ondas-securesu-s-army-order-for-lethal-unmanned-systems
- Ondas Inc. Press Release: Ondas Announces New Air Force Research Laboratory (AFRL) Contract Award to Advance Long Range Grasshopper Autonomous Aerial Delivery System. Published August 6, 2026. Accessed August 7, 2026. https://ir.ondas.com/press-releases/detail/322/ondas-announces-new-air-force-research-laboratory-afrl
- Ondas Inc. Press Release: Ondas Reports Record First Quarter 2026 Financial Results: Raises Full Year 2026 Revenue Forecast to $390 Million. Published May 14, 2026. Accessed August 7, 2026. https://ir.ondas.com/press-releases/detail/306/ondas-reports-record-first-quarter-2026-financial-results
- Ondas Inc. Form 10-Q for the quarterly period ended March 31, 2026. US Securities and Exchange Commission. Published May 14, 2026. Accessed August 7, 2026. https://www.sec.gov/Archives/edgar/data/1646188/000121390026056235/ea029069001ex99-1.htm
- TS2.tech. Ondas (NASDAQ:ONDS) Stock Near $7.50 as 44% Reported Short Interest Raises Earnings Stakes. Published August 3, 2026. Accessed August 7, 2026. https://ts2.tech/en/ondas-nasdaqonds-stock-near-7-50-as-44-reported-short-interest-raises-earnings-stakes/
- Tickeron. Ondas Inc. (ONDS) Q1 2026 Earnings Recap: Revenue Explodes 10-Fold. Published June 29, 2026. Accessed August 7, 2026. https://tickeron.com/earnings/ONDS/
- ChartMill. ONDS Forecast, Price Target and Analyst Ratings. Accessed August 7, 2026. https://www.chartmill.com/stock/quote/ONDS/analyst-ratings
- Benzinga. Ondas Analyst Ratings and Price Targets. Accessed August 7, 2026. https://www.benzinga.com/quote/ONDS/analyst-ratings
- Quiver Quantitative. Ondas Holdings Stock (ONDS) Opinions on Earnings and Short Interest Surge. Accessed August 7, 2026. https://www.quiverquant.com/news/Ondas+Holdings+Stock+(ONDS)+Opinions+on+Earnings+and+Short+Interest+Surge
- GuruFocus. ONDS Looks 24.3% Overvalued on GF Value. Published July 30, 2026. Accessed August 7, 2026. https://www.gurufocus.com/news/8989959/onds-looks-243-overvalued-on-gf-value
- Morningstar. Ondas Inc (ONDS). Accessed August 7, 2026. https://www.morningstar.com/stocks/xnas/onds/quote
- StocksToTrade. ONDS Stock Rallies As DZYNE Deal Resets Growth Story. Published July 20, 2026. Accessed August 7, 2026. https://stockstotrade.com/news/ondas-inc-onds-news-2026_07_20/