
← All sectors / The AI transformation
110 · Pet care & companion animal health
Spending that does not fall in a recession
Curve position
Binding constraint
Veterinarian supply, which limits how much care can be delivered.
Heatmap / How this sector's stocks are moving
| Stock | Price | 1 Day | 1 Week | 1 Month | Year to date |
|---|---|---|---|---|---|
| $ZTS | $89.20 | +7.48% | +14.65% | +25.05% | −29.11% |
| $IDXX | $698.55 | +3.94% | +24.10% | +35.53% | +3.25% |
| $CHWY | $23.40 | +6.12% | +13.37% | +29.00% | −29.20% |
| $FRPT | $71.29 | +2.43% | +9.58% | +13.57% | +17.00% |
| $TRUP | $33.67 | +8.21% | +14.08% | +36.45% | −9.89% |
| Sector average | +5.64% | +15.16% | +27.92% | −9.59% |
Prices as of November 5, 2026. The sector's move is the equal-weighted average of these listed companies, a market proxy for context, not recommendations. See it on the full heatmap →
Sentiment / The mood in this sector's stocks
Since 2018, Pet care & companion animal health has been in Euphoria and steady 15 separate times. After those, its stocks beat their usual three months 5 times (33%), by a median of −7.3 points.
Confidence: low, a split like this is common by chance, so no edge is called.
Pet spending held up through every recent downturn better than almost any other consumer category. Households treat companion animals as family, and the medical spending follows human patterns with roughly a decade of lag.
Historically veterinary care was basic and price sensitive. Insurance penetration, corporate consolidation of practices, and a widening range of available treatments changed both the volume and the sophistication of what gets bought.
The structural driver is demographic and behavioural: more single person households, delayed family formation, and an expectation that a pet receives real medical care rather than palliative treatment.
The technology layer spans point of care diagnostics, companion animal pharmaceuticals including monoclonal antibodies and long acting pain treatments, imaging, telehealth triage, practice management software, and insurance claims processing.
Adoption economics work through the practice. A diagnostic run in the clinic rather than sent to a laboratory generates revenue immediately and improves the visit, which practices adopt readily.
The beneficiaries include animal health pharmaceutical companies, diagnostics makers, practice consolidators, pet insurance underwriters, and the software vendors serving clinics.
The value chain runs from pharmaceutical and diagnostic manufacturers through distributors to practices and owners. Consumables and pharmaceuticals recur; equipment does not.
The overlooked layer includes veterinary distribution, laboratory services, insurance claims administrators, and the staffing platforms addressing the veterinarian shortage.
Competitive dynamics favour firms with clinic relationships and approved products, since veterinary approval pathways are shorter than human ones but still real barriers.
Risks: veterinarian shortage caps volume growth, consumer trade down affects elective procedures, practice consolidation pressures supplier pricing, and pet adoption normalised after its recent surge.
What to watch: practice visit volumes, insurance penetration rates, new companion animal drug approvals, and veterinarian graduation numbers.
Coverage / Daily Disruptor issues in this sector
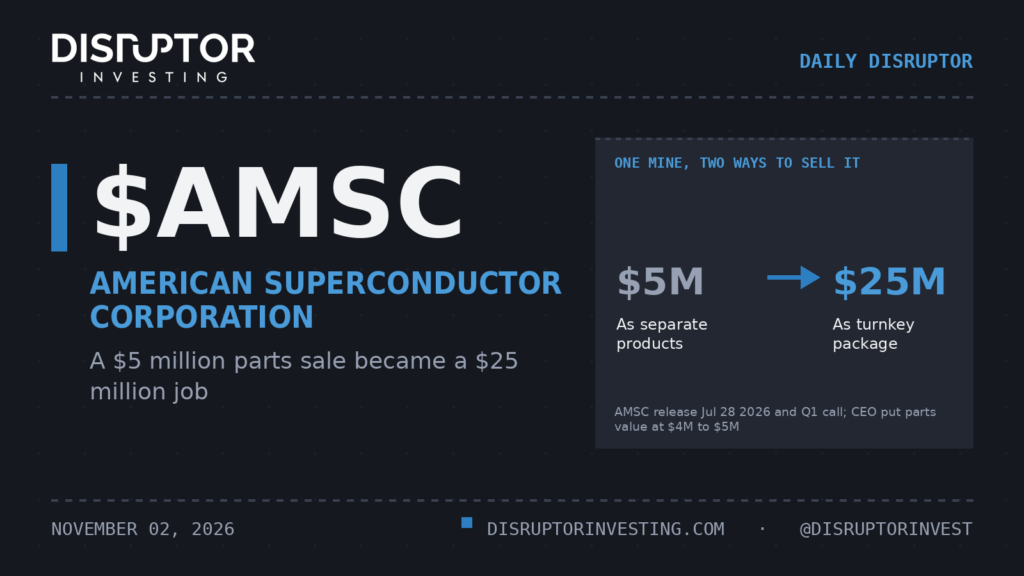
November 2, 2026
Daily Disruptor: $AMSC, the $25 million mine hookup behind a margin scare
AMSC now sells utilities the whole grid connection for new mines and fabs, and Wednesday's results show whether its record order book turns into revenue at…
Read the issue →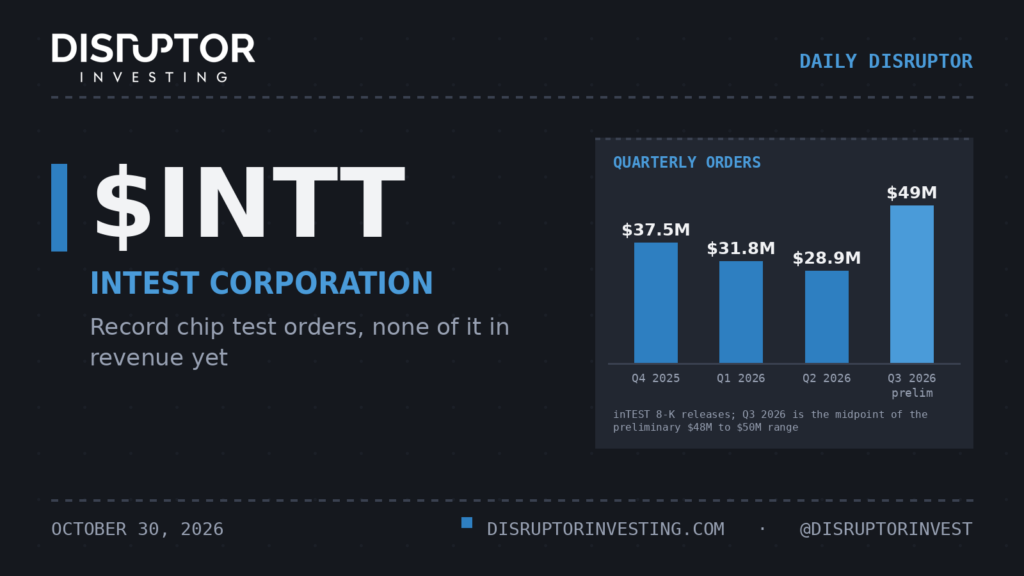
October 30, 2026
Daily Disruptor: $INTT, record chip test orders not yet in revenue
inTEST booked a record $48 to $50 million of orders last quarter, led by chip test hardware, and the full numbers arrive November 6.
Read the issue →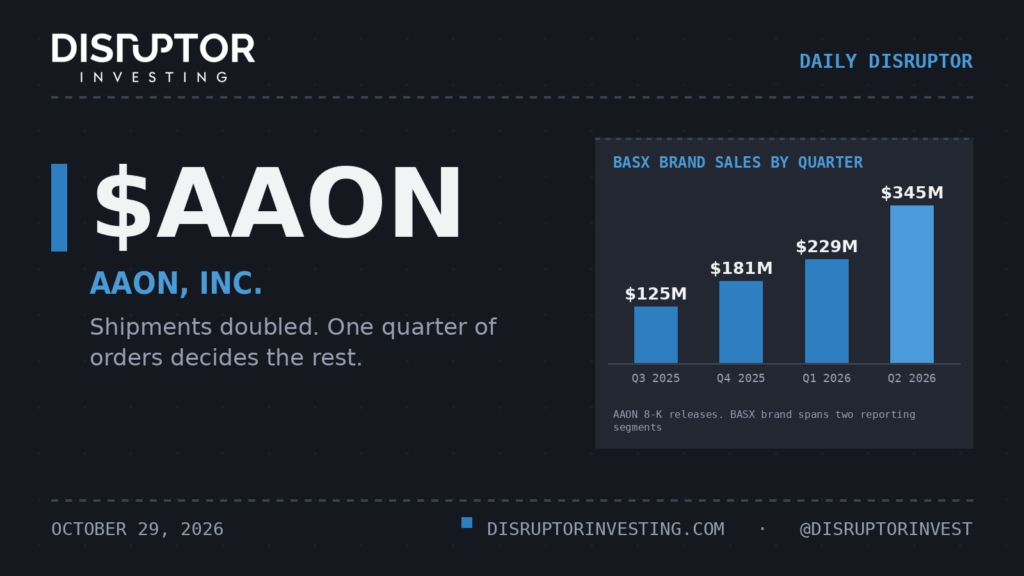
October 29, 2026
Daily Disruptor: $AAON, the factory caught up, now the orders have to
AAON's BASX data centre cooling business has broken its factory limit, but a thin June order book means November's report is the real test.
Read the issue →