
The 30 second version
- MP Materials mines and refines rare earths at Mountain Pass, California, and is starting up Independence, a Fort Worth plant that turns its own oxide into finished magnets for GM and Apple.
- The magnet line is at Liftoff: GM got qualification magnets in the second quarter, and first commercial shipments are still guided for the fourth quarter of 2026.
- Independence is sold out between GM and Apple, the planned 10X plant is fully contracted to the Department of War, and the precursor work it replaces earned margins above 40%.
- Next test: third quarter results after the close on November 5. We want NdPr output above 1,000 tonnes and the GM date held.
- It breaks if GM shipments slip into 2027, or if the business loses money again once the price floor payments are stripped out.
In the first half of 2026, MP Materials reported $65.1 million of adjusted EBITDA. Payments under its price floor agreement with the Department of War made up $59.9 million of that.
That is the bear case in one sentence, and it is a fair one. Split the half into quarters, though, and something else shows up. Without the floor, adjusted EBITDA went from a loss of about $5.7 million in the first quarter to a profit of about $10.9 million in the second, while the magnet plant that should carry the next leg sat in start up, burning costs the company keeps outside that measure.
This morning the setup is unusually tight. MP reports on November 5, and it has promised commercial magnets to GM before December 31. Two tests, one quarter.
What just happened
MP set its third quarter release for after the US close on Thursday November 5, with a call that afternoon. In September, local reporting on the first Fort Worth magnets delivered to GM for in vehicle testing repeated the plan: commercial shipments later this year.
The backdrop moved the other way. After the Trump and Xi summit in Washington in late September, the suspension of China’s October 2025 export controls was pushed out to January 10, 2027, with no jointly documented settlement on critical minerals. Rare earth shares sold off as a group through October; on October 12 MP fell about 6% alongside USA Rare Earth while the broad market barely moved. On Thursday the stock traded around $38.57, a market value near $6.9 billion.
A suspension with an expiry date leaves a carmaker’s purchasing team exactly where it was. GM still needs a second, qualified source of magnets that a licence decision in Beijing cannot switch off, and that need is what the November report speaks to.
The business
MP has two segments. Materials runs the Mountain Pass mine and separation plant and sells NdPr oxide and metal by the tonne. In the second quarter it sold 1,006 tonnes and booked $94.4 million of NdPr revenue, roughly $94 a kilogram. The Department of War tops that up to a $110 floor, and the top up is booked below revenue as price protection income. For the third quarter, management guided realised oxide prices in the high $90s and floor income of roughly $10 a kilogram.
Magnetics is the Independence plant. GM signed on as its foundational customer in April 2022, under a long term agreement covering magnets and the precursor products that come before them. Today almost all of the segment’s revenue is precursor metal and alloy sold to GM against an earlier prepayment. About $46 million of that prepayment remains to be earned over the next three to four quarters, falling a little each quarter. After that, the metal goes into MP’s own magnets.
The unit economics are better than the headline suggests. Precursor production earned adjusted EBITDA margins above 40% in the second quarter, according to management. Independence has an initial nameplate of 1,000 tonnes of magnets a year, and the chief executive told analysts it is fully sold between GM and Apple. 10X, a $1.25 billion campus in Northlake, Texas, is meant to lift total magnet capacity to roughly 10,000 tonnes and is fully contracted to the Department of War, though management expects to sell most of it to industry when it comes online.
One detail from the filing is easy to miss. Adjusted EBITDA adds back $13.6 million of initial start up costs at Independence in the second quarter alone, money spent running trial and rate test batches. Competitors outside China are few: Japanese and European incumbents, and newer American entrants such as USA Rare Earth, whose government funding is tied to milestones. None of them owns the mine.
Where it sits on our curve
Rare earth magnets and motor supply sits at Liftoff on our Disruption Map, and that matters now: the first Western magnet lines are crossing from samples to paid volume. MP’s own magnet business fits the same stage. The binding constraint for GM is a qualified magnet made outside China, at volume, at a price that holds through a cycle. MP’s threshold is narrower and more physical: pass GM’s in vehicle and regulatory testing, then run lines at yield. The $110 floor on its oxide is what keeps the input price financeable for both sides.
On our evidence sequence, the furthest step is paid deployment. GM has paid for precursor products for more than a year, and magnets went to GM for qualification in the second quarter. Behind that sit commitments from three unrelated buyers: GM, Apple, and the Department of War for 10X. In July MP also signed a multiyear gadolinium supply deal with a US aerospace and defence manufacturer, which management sized in nine figures, and drone makers signed subscription agreements under a scheme MP calls Project Swarm. For the curve to steepen, we need commercial magnets to GM and then Apple’s volume on the same lines with less start up effort than GM needed.
The strongest alternative is simple. Profit came back because of the floor and a firmer NdPr price, and magnets have yet to contribute a dollar of finished product revenue. The way to tell the two apart is EBITDA excluding floor income in the third quarter, and then actual magnet revenue in the fourth.
The numbers
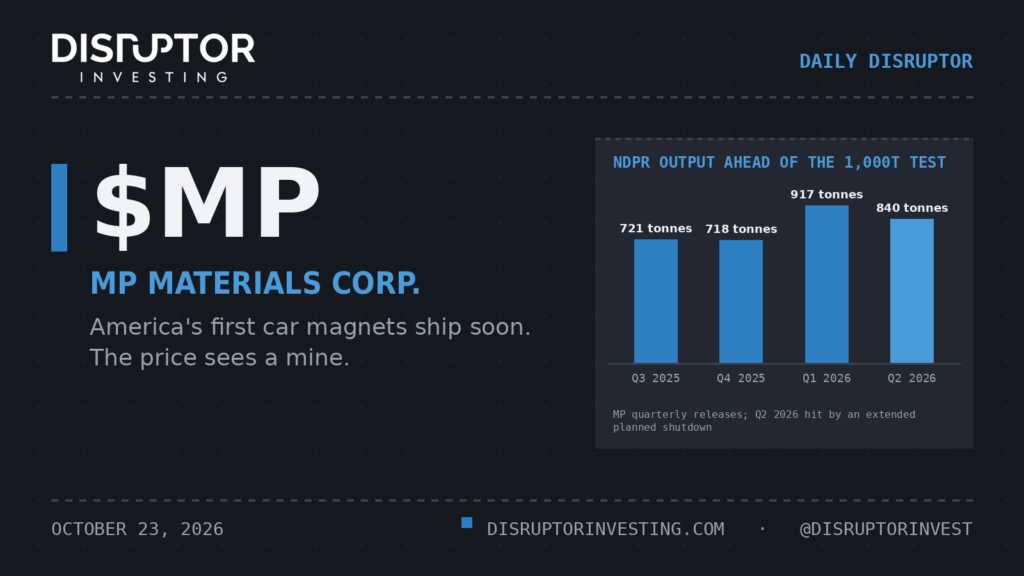
Production shows the turn better than revenue does. NdPr output was 721 tonnes in the third quarter of 2025, 718 in the fourth, a record 917 in the first quarter of 2026 and 840 in the second, when a planned April shutdown ran long. The operations chief expects third quarter output above 1,000 tonnes. Revenue followed: $57.4 million a year ago, $90.6 million in the first quarter, $108.5 million in the second, up 89%.
Margins are improving, slowly. Second quarter adjusted EBITDA was $28.5 million against a loss of $12.5 million a year earlier, and Materials earned about $32 a kilogram sold, floor income included. The GAAP net loss was still $20.3 million. Magnetics revenue fell 17% to $16.5 million, as expected while precursor sales wind down, yet the segment kept $7.5 million of adjusted EBITDA.
The balance sheet carries the build. MP held $1.45 billion of cash and short term investments at June 30, against $935 million of long term debt and preferred stock held by the Department of War whose liquidation preference rose from $413 million to $428 million in six months as dividends accrued. Operating cash flow was a positive $4.9 million in the half; capital spending was $308 million, with $500 to $600 million guided for the year. Weighted diluted shares were 8.9% above a year earlier, and the company’s adjusted count, which includes the preferred and a warrant, was 198.9 million.
We could not confirm the current consensus from a primary source, so we will not lean on it. Our own estimate is revenue growth of roughly 58% in 2026 and 40% in 2027.
What the price already requires
At $38.57 the equity is worth about $6.9 billion on basic shares and $7.7 billion on the adjusted diluted count. Add debt and the preferred, subtract cash, and enterprise value is near $6.8 billion today, closer to $7 billion once the rest of this year’s capital spending leaves the bank. At 14 to 15 times EBITDA, which we think a contracted, floor protected domestic supplier can hold, that needs about $470 to $500 million of adjusted EBITDA by 2029. At 12 times it needs about $580 million.
Our downside: 10X slips two years, NdPr sits at the floor and output stalls near 3,600 tonnes a year, leaving something like $150 to $200 million in 2029 and an enterprise value well under half of today’s. Our central case: about 5,000 tonnes of NdPr at the floor with unit margins rising from $32 toward $50 a kilogram as fixed costs spread, Independence full, the first stages of 10X shipping, plus heavy rare earths, for $420 to $520 million. Our upside adds market prices above the floor and a faster 10X ramp, for $750 to $900 million.
So the central case covers the price at the multiple we think is fair and leaves little to spare. The gap is what the market’s model omits. It values MP as a mine with a government put, and reads the falling Magnetics line as weakness. That line is shrinking because a 40% margin precursor business is being retired on purpose to feed a sold out magnet plant, and none of the magnet earnings from Independence or 10X appear in any reported number yet.
What breaks it
We wrote the break before the test. If the November 5 report or call moves first commercial GM shipments into 2027 or later, the thesis is broken; a deadline that moves cannot be tested. It also breaks if third quarter NdPr output comes in below 900 tonnes in a quarter with no planned shutdown, or if adjusted EBITDA excluding floor income turns negative again.
The next most likely failure is slower and duller: yield. Management has said a handful of circuits at Mountain Pass still cause reliability problems, and magnet lines can stall the same way. Financing is less of a worry. With operating cash near break even and capital spending running about $150 million a quarter, $1.45 billion lasts roughly nine quarters, and management says it fully funds the long term capital plan. The real risk is a 10X overrun that forces new equity at today’s price.
What we are watching
- November 5, 2026, third quarter results. Stronger: NdPr output of 1,000 tonnes or more, GM shipments reaffirmed for the fourth quarter, EBITDA excluding floor income of $15 million or more. Broken: GM pushed to 2027, output under 900 tonnes, or EBITDA excluding floor income below zero.
- December 31, 2026, end of the shipment window, reported with fourth quarter results in early 2027. Stronger: finished magnet revenue recognised and dysprosium and terbium from Mountain Pass shipped to Independence. Broken: no finished magnet revenue for the quarter.
- January 10, 2027, China’s suspension of its export controls lapses or is extended. Stronger: new magnet contracts signed regardless of what Beijing does. Broken: GM or Apple trims committed volumes because Chinese supply is flowing again.
- May 2027, first quarter results. Stronger: Magnetics revenue above its $21.1 million precursor peak from the first quarter of 2026. Broken: the segment still below $15 million.
Not financial advice.
References
- MP Materials Corp. Form 8-K, Exhibit 99.1: MP Materials Reports Second Quarter 2026 Results. US Securities and Exchange Commission. Published August 6, 2026. Accessed October 22, 2026. https://www.sec.gov/Archives/edgar/data/0001801368/000180136826000047/mpmcq22026er.htm
- MP Materials Corp. Form 8-K, Exhibit 99.1: MP Materials Reports First Quarter 2026 Results. US Securities and Exchange Commission. Published May 7, 2026. Accessed October 22, 2026. https://www.sec.gov/Archives/edgar/data/0001801368/000180136826000027/mpmcq12026er.htm
- MP Materials Corp. MP Materials Announces Date for Third Quarter 2026 Financial Results and Webcast. Published October 8, 2026. Accessed October 22, 2026. https://investors.mpmaterials.com/investor-news/news-details/2026/MP-Materials-Announces-Date-for-Third-Quarter-2026-Financial-Results-and-Webcast/default.aspx
- The Dallas Morning News. MP Materials delivers rare earth magnets made in Fort Worth to GM. Published September 24, 2026. Accessed October 22, 2026. https://www.dallasnews.com/business/technology/article/mp-materials-fort-worth-magnets-used-gm-evs-22422778.php
- Bloomsbury Intelligence and Security Institute. China’s Rare Earth Processing Dominance and What the Trump Xi Summit Didn’t Change. Published October 1, 2026. Accessed October 22, 2026. https://bisi.org.uk/reports/chinas-rare-earth-processing-dominance-and-what-the-trump-xi-summit-didnt-change
- 24/7 Wall St. USA Rare Earth Drops 6% With Milestone Based Government Funding Still Ahead of It; MP Materials Falls 6%, Critical Metals Holds Steady. Published October 12, 2026. Accessed October 22, 2026. https://247wallst.com/investing/2026/10/12/usa-rare-earth-drops-6-with-milestone-based-government-funding-still-ahead-of-it-mp-materials-falls-6-critical-metals-holds-steady/
- Robinhood. MP Materials (MP) stock quote and key statistics, trading on October 22, 2026. Accessed October 22, 2026. https://robinhood.com/us/en/stocks/MP/
- Motley Fool Transcribing. MP Materials (MP) Q2 2026 Earnings Call Transcript. The Motley Fool. Published August 14, 2026. Accessed October 22, 2026. https://www.fool.com/earnings/call-transcripts/2026/08/13/mp-materials-mp-q2-2026-earnings-call-transcript/
- MP Materials Corp. Form 10-K for the fiscal year ended December 31, 2024. US Securities and Exchange Commission. Published February 2025. Accessed October 22, 2026. https://www.sec.gov/Archives/edgar/data/1801368/000180136825000009/mp-20241231.htm
- CNBC. MP Materials selects Texas for rare earth magnet manufacturing site. Published February 26, 2026. Accessed October 22, 2026. https://www.cnbc.com/2026/02/26/mp-materials-selects-texas-for-rare-earth-magnet-manufacturing-site.html
- Fort Worth Report. MP Materials building $1.25B magnet plant just north of Fort Worth. Published February 26, 2026. Accessed October 22, 2026. https://fortworthreport.org/2026/02/26/mp-materials-building-1-25b-magnet-plant-just-north-of-fort-worth/
- MP Materials Corp. Form 8-K, Exhibit 99.1: MP Materials Reports Third Quarter 2025 Results. US Securities and Exchange Commission. Published November 2025. Accessed October 22, 2026. https://www.sec.gov/Archives/edgar/data/1801368/000180136825000052/mpmcq32025er.htm
- MP Materials Corp. Fourth Quarter 2025 Results Presentation, as republished by MarketScreener. Published February 26, 2026. Accessed October 22, 2026. https://www.marketscreener.com/news/mp-materials-fourth-quarter-2025-results-presentation-ce7e5cd9d08bff21