
The 30 second version
- CLEAR runs biometric identity lanes at 62 US airports and sells the same verified identity to companies and agencies through CLEAR1.
- The airport network is in Flight, and the constraint easing is labor: self service eGates let revenue grow while lane staffing costs stay flat.
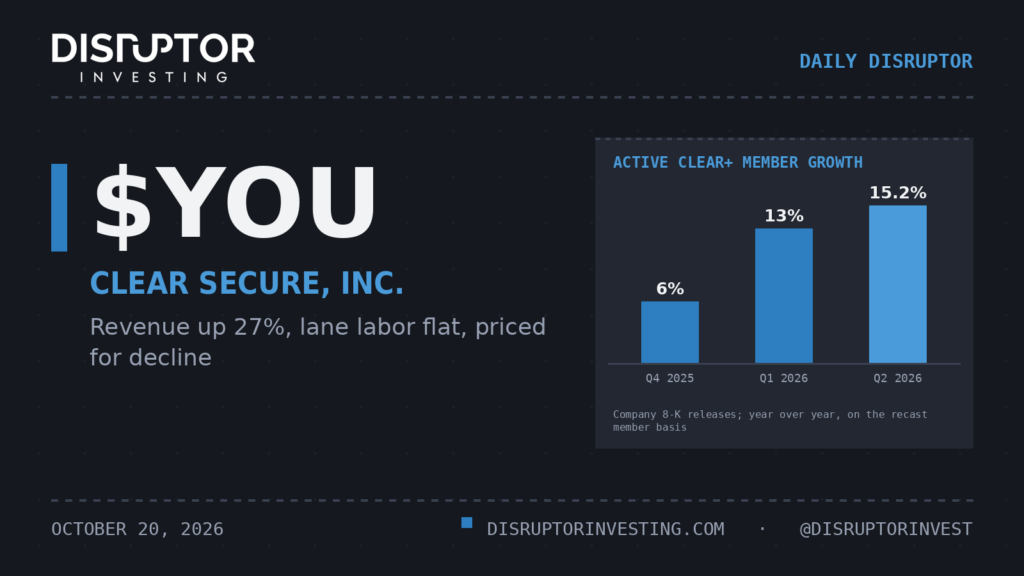
- Q2 2026: revenue up 26.6%, paying members up 15.2% after a 6.0% pace in Q4 2025, lane staff costs up just $0.3 million.
- The test is Q3 results, expected in early November, against a guide of $284M to $287M revenue and $311M to $316M bookings.
- The thesis breaks if paying members drop below June’s 8.33M after the July price rise, or the free cash flow guide is cut below $450M.
CLEAR took in $58.3 million more revenue last quarter than a year earlier. The bill for the people who staff its airport lanes rose by $0.3 million.
That gap is the whole story in two numbers. Across the first half of 2026, direct salaries and benefits actually fell, from $98.4 million to $96.2 million, while revenue climbed 23%. The machines doing that work are eGates, kiosks where a member looks at a camera and walks through in seconds, and they now sit in 50 of the 62 airports.
Why this morning: Q3 results land in about two weeks, and the cash flow line will print negative. That is scheduled. Every third quarter CLEAR settles a large annual liability with its credit card partner, about $315 million this year, so the numbers worth reading that day are members, bookings and the full year cash guide.
What just happened
On August 5 CLEAR reported a second quarter that beat its own guidance by a wide margin. Management had guided revenue of $268 million to $271 million and delivered $277.8 million; bookings had been guided at $280 million to $285 million and came in at $295.9 million. Adjusted EBITDA margin reached 36.4%, up nine points in a year and past the 35% target the company set when it listed five years ago.
Two things inside that report matter more than the beat. The standard CLEAR+ price went from $209 to $219 on July 1, and the finance chief said on the call that retention showed no impact. And the full year free cash flow guide went up for the second time in 2026, from at least $440 million in February to $465 million in May to at least $480 million in August.
Then on October 7 the Department of Veterans Affairs began a pilot that lets veterans use CLEAR1 to create and access VA.gov accounts. It is free for veterans and optional, so it brings no revenue worth modeling yet. What it brings is a federal agency running CLEAR’s identity check on a consumer website, which is the market management keeps pointing to.
The business
CLEAR has two businesses on one identity platform. CLEAR Travel sells CLEAR+, an annual subscription that lets a member skip the ID check at airport security; family members pay $125, and airline and card partners sell discounted tiers. American Express renewed its arrangement in the fourth quarter of 2025, keeping CLEAR+ as a built in benefit on its Platinum cards. CLEAR also enrolls travelers in TSA PreCheck, at 280 retail locations in June, down from 340 at the end of 2025.
The unit economics are simple to sketch. Trailing twelve month bookings of $1.13 billion over 8.33 million active members works out to roughly $136 per member a year on our arithmetic, a ceiling because it also includes CLEAR1 and PreCheck. Against that, airports took a revenue share equal to 14.1% of Q2 revenue and lane staff cost 17.3%, down from 21.7% a year earlier. Members pay upfront, which is why deferred revenue stood at $573 million in June: customers fund the business before CLEAR serves them.
CLEAR1 sells verification to companies, health systems and government. A worker or customer who already verified with CLEAR at an airport does not start from scratch, so each new enterprise customer draws on a base of 43.5 million total members, up 30% in a year, a rise the finance chief tied mainly to business demand. CLEAR1 bookings grew about fivefold year over year in Q1, and in Q2 new customer signings and pipeline each rose more than 50% from the prior quarter.
The competitor that matters at airports is the government itself. TSA PreCheck Touchless ID, an opt in facial match for PreCheck travelers flying participating airlines, was at 65 airports by late May. CLEAR’s answer is that it removes the ID step for every airline and adds concierge escorts, wayfinding and food orders through an app averaging 1 million monthly users.
Where it sits on our curve
Digital identity sits at Liftoff on our Disruption Map, and the reason it matters now is fraud. AI has made fake documents and synthetic people cheap, and an executive order on fraud, which management cited on its last call, pushes agencies to check eligibility before money goes out. That puts reusable, already verified identity in front of buyers who never had a budget line for it.
The airport network itself is in Flight. The binding constraint was never demand; it was the cost and consistency of serving each lane, and the chief executive admitted on the Q2 call that the experience degraded in 2023 and 2024 and members left. eGates fix both at once. The evidence runs all the way along our sequence: new airports (Indianapolis and Bentonville in Q2), renewals holding at a higher price, and cash collected before service, with first half free cash flow of $374.5 million. CLEAR1 is the Liftoff curve inside it, with paid customers expanding but no revenue line reported yet.
The strongest alternative explanation is a catch up. Some of the member growth is lapsed customers coming back to a fixed product, some is the price rise, and air travel has been strong. A recovery like that fades within a year. What separates the two is the member count after July’s price rise: adoption keeps adding members in Q3 and Q4, a one time recovery stalls while revenue per member carries the growth.
The numbers
The turn shows in the sequence. Revenue growth went from 16.7% in Q4 2025 to 19.7% in Q1 2026 to 26.6% in Q2, with 24.6% guided for Q3. Active CLEAR+ member growth, on the recast basis, went from 6.0% to 13.0% to 15.2% over the same three quarters. That second series is the one that says adoption, not pricing.
Bookings are the soft spot. They grew 25.4%, then 40.8%, then 32.8%, and the Q3 guide of 20.5% is a clear slowdown even against a weak Q3 2025, when bookings grew about 14%. Management mentioned that bigger CLEAR1 contracts make timing lumpy. We would rather see it in the number.
Margins are where eGates show. Adjusted EBITDA margin rose from 27.4% to 36.4% year over year, with roughly 70% of incremental revenue flowing to EBITDA in Q2. Q2 free cash flow was $189.0 million, up 60%. The balance sheet held $959 million of cash and marketable securities in June with no borrowings, enough to absorb the $315 million settlement. Last year the same payment turned Q3 free cash flow negative by about $53 million on our arithmetic from the annual and half year figures.
On dilution, reported diluted Class A shares rose 8.8% year over year, but that mostly reflects holders swapping LLC units for Class A stock. Counting every class, shares went from 133.2 million in December to 134.7 million in June, close to flat. Stock compensation was $22.4 million in the half, a real cost that free cash flow does not deduct.
What the price already requires
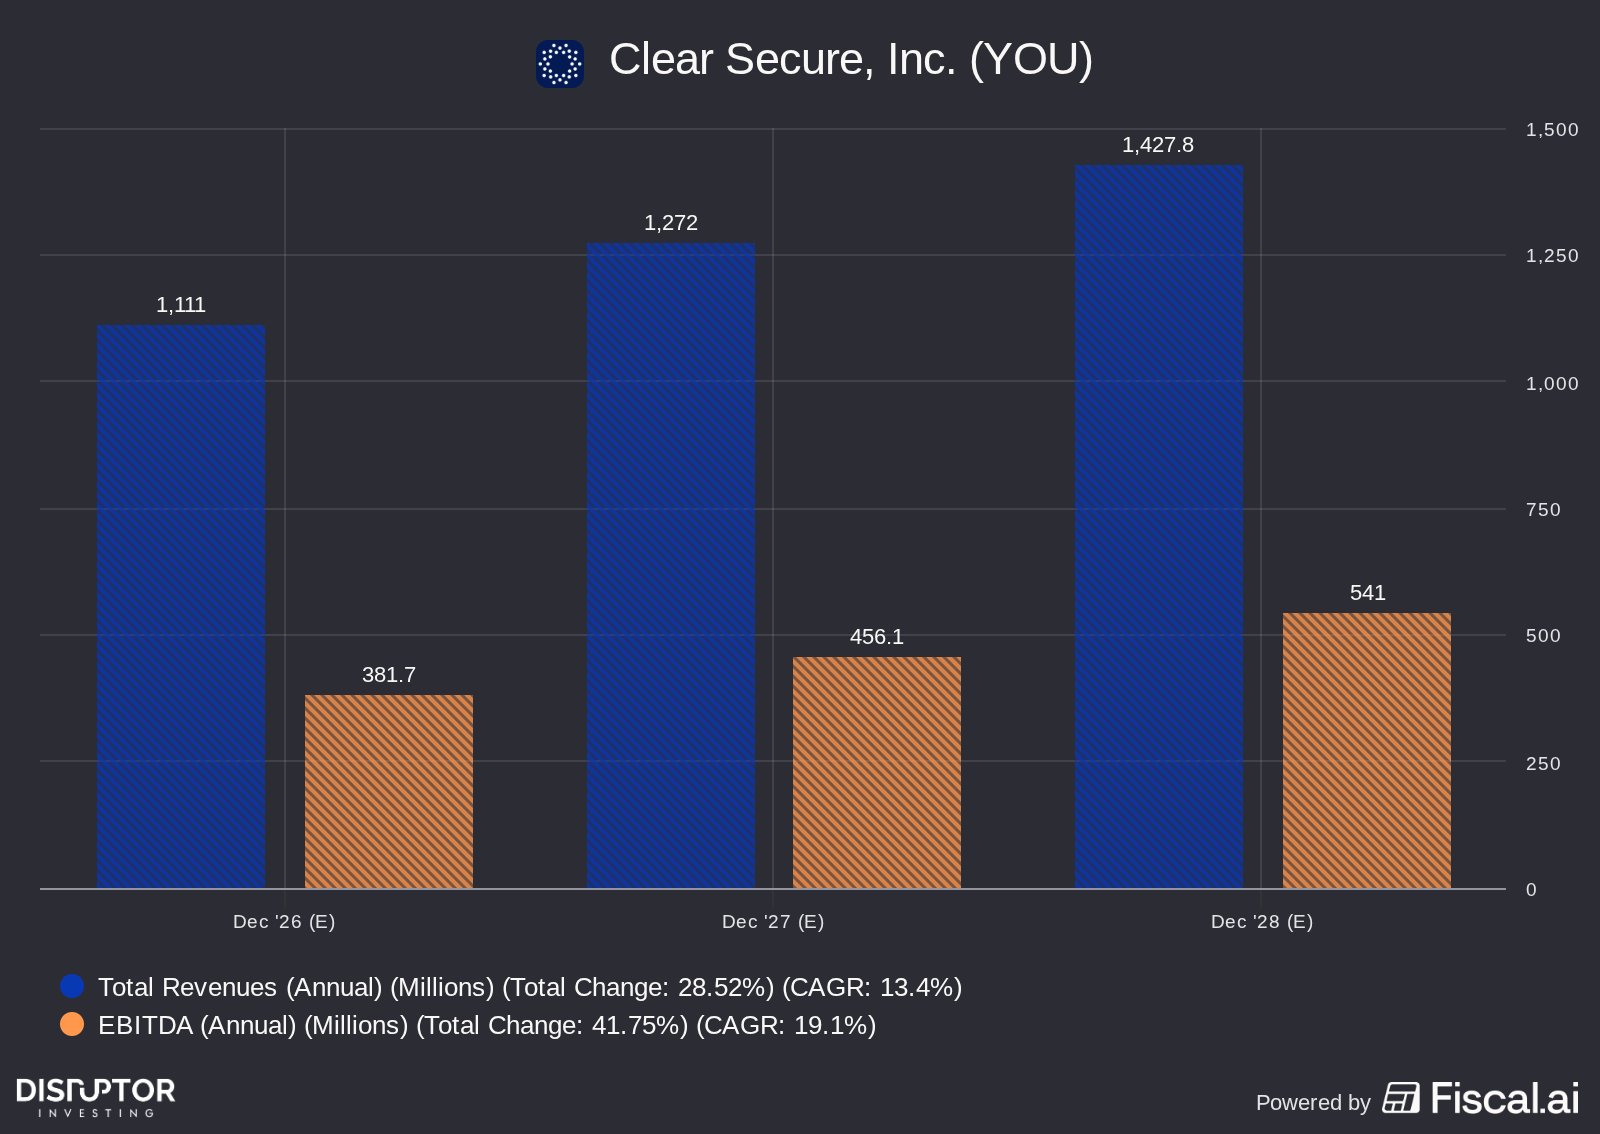
At about $45.20 and 134.7 million shares across all classes, the equity is worth roughly $6.1 billion. After the Q3 payment we estimate net cash near $0.8 billion, so the business carries an enterprise value around $5.3 billion. That is 12.7 times the free cash flow guide and about 14 times our estimate of 2026 adjusted EBITDA near $383 million.
Run it backwards. Discounting at 10% with 3% growth after year five, today’s price fits free cash flow that shrinks about 4% a year for five years from $480 million. Our downside, where Touchless ID caps member growth and deferred revenue stops building, has free cash flow settling at $400 million on 13 times plus cash, about $6.0 billion, roughly today. The central case, revenue growing about 15% in 2027 and free cash flow near $540 million on 15 times plus cash, gives about $9.0 billion. Upside, with CLEAR1 large enough to report on its own, is $620 million on 18 times, about $12.2 billion.
The gap sits in the cost line. The market prices CLEAR as an airport toll booth facing a government rival, and toll booths do not grow revenue 27% on flat labor. CLEAR1 is not in any reported revenue figure, yet it is the reason total members grew twice as fast as paying ones. A price that assumes decline while members reaccelerate is the setup we look for.
What breaks it
We will treat the thesis as broken if Q3 revenue comes in below $284 million, bookings below $305 million, or active CLEAR+ members fall below June’s 8.33 million, which would mean the July price rise cost members rather than adding margin. A cut to the free cash flow guide below $450 million breaks it too, because cash collected upfront is the cleanest read on demand this company offers. Losing a top ten airport concession or TSA authority to enroll PreCheck would break it outright.
The next most likely failure is slower and quieter: Touchless ID spreading airport by airport until the government option is good enough for most PreCheck travelers, showing up first as fewer new members at those airports. Financing is not the risk. CLEAR funds itself, holds close to a billion dollars, and pays a dividend, so it reaches every test on this list with its own money.
What we are watching
- Early November 2026, Q3 results: revenue of $287 million or more, bookings of $316 million or more and at least 8.43 million active members (up 14%) strengthen the thesis; members below 8.33 million or bookings under $305 million break it.
- Same report, full year cash guide: held or raised from at least $480 million strengthens it; a cut below $450 million breaks it.
- December 31, 2026, eGates across the whole network: Q4 direct salaries at or below 17% of revenue strengthen the labor case; a move back above 19% says the savings were a one off.
- Late February 2027, Q4 results and 2027 guidance: a free cash flow guide of $540 million or more, or a first CLEAR1 revenue disclosure, strengthens it; a guide below $480 million means growth has stopped.
Not financial advice.
References
- Clear Secure, Inc. CLEAR Announces Second Quarter 2026 Financial Results, Exhibit to Form 8-K. US Securities and Exchange Commission. Published August 5, 2026. Accessed October 19, 2026. https://www.sec.gov/Archives/edgar/data/0001856314/000185631426000039/clearq22026pressreleaseear.htm
- Motley Fool Transcribing. Clear Secure (YOU) Q2 2026 Earnings Call Transcript. The Motley Fool. Published August 12, 2026. Accessed October 19, 2026. https://www.fool.com/earnings/call-transcripts/2026/08/12/clear-secure-you-q2-2026-earnings-call-transcript/
- Clear Secure, Inc. CLEAR Announces First Quarter 2026 Financial Results, Exhibit to Form 8-K. US Securities and Exchange Commission. Published May 6, 2026. Accessed October 19, 2026. https://www.sec.gov/Archives/edgar/data/0001856314/000185631426000013/clearq12026pressreleaseear.htm
- Clear Secure, Inc. CLEAR Announces Fourth Quarter and Full Year 2025 Financial Results, Exhibit to Form 8-K. US Securities and Exchange Commission. Published February 25, 2026. Accessed October 19, 2026. https://www.sec.gov/Archives/edgar/data/1856314/000185631426000004/clearq42025pressreleaseear.htm
- Clear Secure, Inc. U.S. Department of Veterans Affairs Selects CLEAR for New Pilot Initiative to Modernize the Veteran Experience on VA.gov. PR Newswire via Morningstar. Published October 7, 2026. Accessed October 19, 2026. https://www.morningstar.com/news/pr-newswire/20261007ny65446/us-department-of-veterans-affairs-selects-clear-for-new-pilot-initiative-to-modernize-the-veteran-experience-on-vagov
- FedScoop. VA piloting CLEAR identity verification on its website. FedScoop. Published October 7, 2026. Accessed October 19, 2026. https://fedscoop.com/va-piloting-clear-identity-verification-on-its-website/
- Transportation Security Administration. TSA PreCheck Touchless ID now available at Albuquerque International Sunport. Published May 28, 2026. Accessed October 19, 2026. https://www.tsa.gov/news/press/releases/2026/05/28/tsa-precheckr-touchless-id-now-available-albuquerque-international
- Robinhood. Clear Secure (YOU) stock snapshot, share price for the October 19, 2026 session. Accessed October 19, 2026. https://robinhood.com/us/en/stocks/YOU/